

Rate Markets Update · Wednesday, October 14, 2026
Rates Increase on Higher-Than-Expected CPI Data
- PPI & Retail Sales Data Prints Tomorrow
- Brent Crude Oil at $106
Flash Update: US RATE MARKETS – WEDNESDAY OCTOBER 14, 2026
US Treasury yields and SOFR swap rates are moving higher on hotter-than-expected September CPI results
September CPI advanced at the fastest pace in five months on rising fuel costs
The report suggests fear of higher inflation will remain front and center for markets as we head towards the FOMC meeting and Midterm elections
The US-Iran conflict and the price of crude oil, and resultant fear of higher inflation continue to be a primary focus for the rate markets
The price of Brent crude oil rose to ~$106 per barrel overnight on renewed attacks in the Middle East
Houthi missiles struck Aramco Headquarters overnight, further escalating tensions in the Middle East
Interest rates are likely to continue to be highly correlated to the direction of oil prices for the near term
“Big” Bank and tech sector corporate earnings reports are due this week and remain a key focus for markets
Note: FOMC Chair Kevin Warsh speaks on 10/15 at a Fireside chat with the IMF’s Georgieva
The next FOMC rate decision is due Wednesday, October 28th at 2:00 PM
Next up for “key” economic data: September PPI & Retail Sales data prints tomorrow, 10/15 at 8:30 AM
Short-term SOFR swap rates are trading up ~10-12 bps this morning, depending on tenor
Medium-term SOFR swap rates are up ~10-12 bps currently, depending on tenor
Long-end SOFR swap rates are trading up ~6-8 bps this morning, depending on tenor
Good morning – US Treasuryyields and SOFR swap rates rose materially this morning as US consumer prices climbed at the fastest pace in five months, reinforcing market concerns that the FOMC will continue to raise rates amid elevated oil prices. Headline CPI rose 0.6% in September from a month earlier and advanced 3.7% year-over-year. The hot CPI data forced traders to increase bets on an October rate hike, and to project a total of three rate increases by the end of 2027. (In fact, current rate hike odds imply the possibility of three rate hikes by March 2027.) Market implied odds for an October rate hike have jumped to ~58.5% this morning - those odds were ~23.8% yesterday. From my perspective it is clear we are facing stubborn inflation that is moving in the wrong direction – the Fed may be forced to act sooner rather than later, which is why an October rate hike is firmly back in play.
Escalating hostilities in the Middle East between the Houthi and Saudi Arabia are keeping pressure on crude oil prices, which is also contributing to the “high inflation” mood currently permeating the market. I expect high crude oil prices to continue to keep upward pressure on interest rates.
Traders will continue to track key economic data closely as they determine what is next for the Fed. September PPI and Retail Sales results are due tomorrow, 10/15 at 8:30 AM. Expectations for tomorrow’s release of the September PPI and Retail Sales data are as follows: Headline PPI MoM, 0.6% (vs. 0.4% the prior month); Headline PPI YoY, 5.4% (vs. 5.4% prior); Core PPI MoM, 0.3% (vs. 0.2% prior); Core PPI YoY, 4.4% (vs. 4.6% prior); Retail Sales Advance MoM, 0.3% (vs. 1.2% prior); Retail Sales Ex Autos, 0.5% (vs. 1.4% prior); Retail Sales Ex Autos and Gas, 0.2% (vs. 1.2% prior).
CHARTS OF THE DAY:
A: September CPI Recap
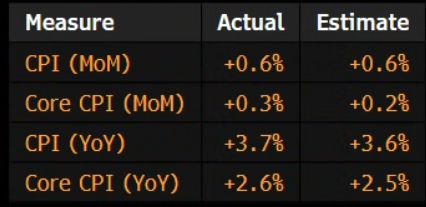
Source: Bloomberg, LLP | September CPI Recap
B: Hotter-Than-Expected CPI Points to More Fed Rate Increases
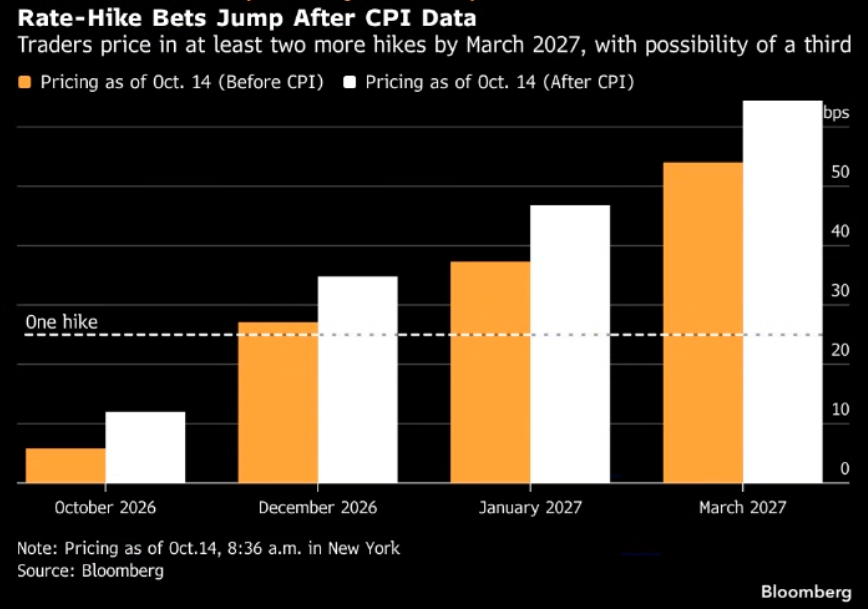
Source: Bloomberg, LLP | Market Implied Fed Rate Hike Expectations Through March 2027
C: Direction of Inflation a Concern for Consumers & Traders
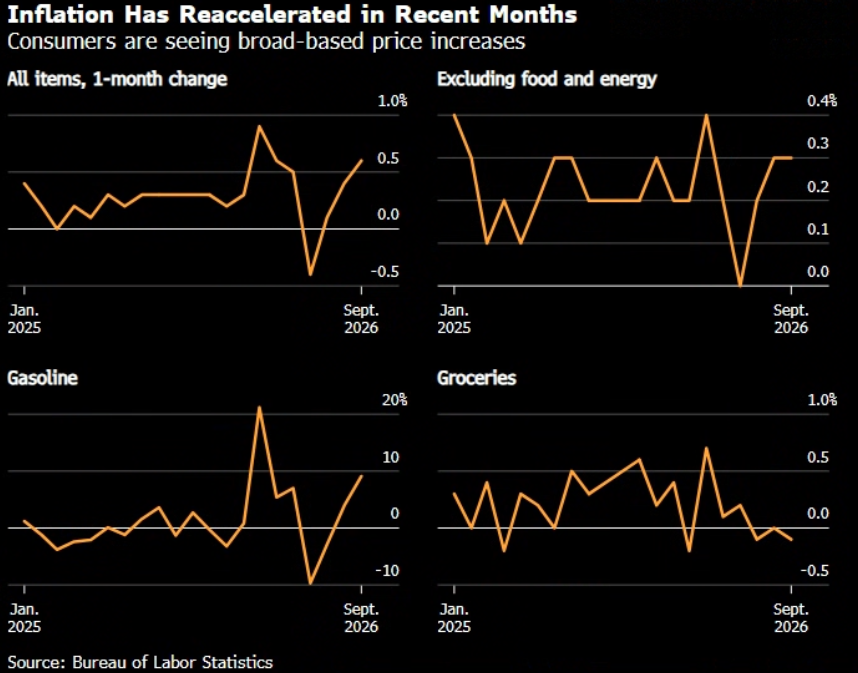
Source: Bloomberg, LLP | YTD HISTORICAL INFLATION DATA – CPI
D: Crude Oil Prices Remain Elevated, Keeping Pressure on Medium- and Long-Term Rates
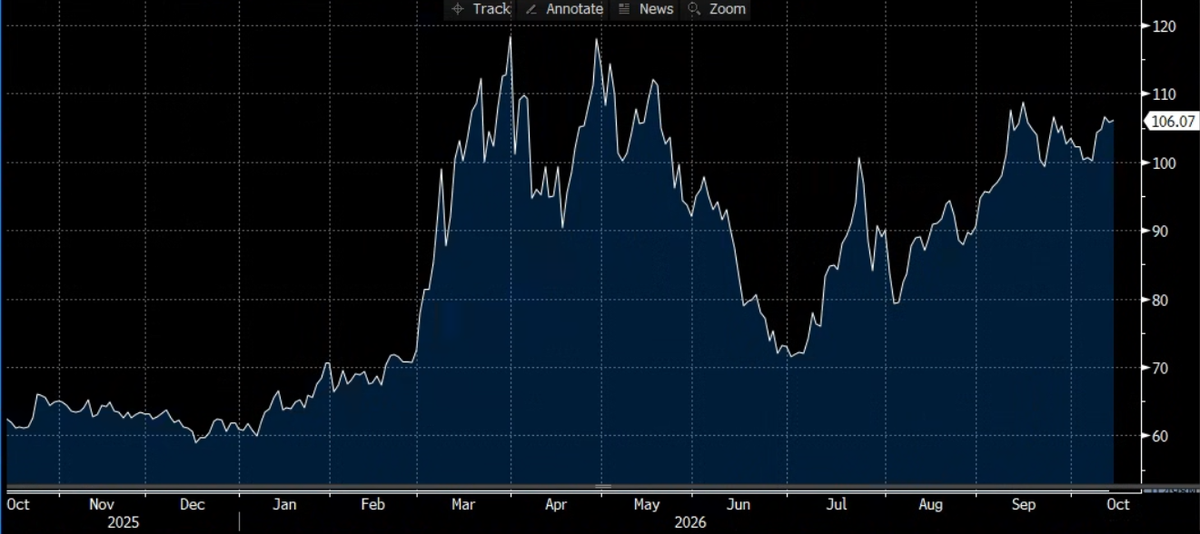
Source: Bloomberg, LLP | Price of Brent Crude Oil, Prior 12-Months
SOFR Swap Market - Quick Summary:
The 1Y SOFR swap rate is trading up ~10-11 bps this morning. 2Y and 3Y SOFR swap rates are currently trading up ~10-12 bps. 5Y and 10Y SOFR swap rates are trading up ~10-12 bps this morning. The very back-end of the swap curve (20Y and 30Y) is currently trading up ~6-8 bps from yesterday’s closing levels.
“Key News” the market is tracking includes:
Geopolitical developments continue to weigh on markets.Developments in the US/Iran “war” will continue to captivate the market’s attention. l
Lack of forward guidance from the Fed is forcing traders to pay more attention to economic data – this may fundamentally change the way markets position for and react to Fed rate decisions going forward.
There is still a sharp focus on the performance of the growing AI sector and more broadly, on what AI really “means” for the US and global economies. Overall market sentiment, and perhaps even economic performance, may be impacted by AI for the foreseeable future.
Tariffs remain in focus, particularly the “trade war” situation between the US and Canada. US/China relations are always in focus.
CHART 1:US RATES SNAPSHOT: 9:30 AM Eastern
Chart 1 Key:
Far Left Columns:US Treasury Yields & Change on Day (bps)
Center Columns:SOFR OIS Swap Spreads (bps) & Change on Day (bps)
Far Right Columns:SOFR OIS Swap Rates & Change on Day (bps)
Please note: Market levels can change rapidly – rate cap premiums are subject to a dynamic market that can change frequently.
UST YIELDS | SWAP SPREADS | SOFR SWAP RATES
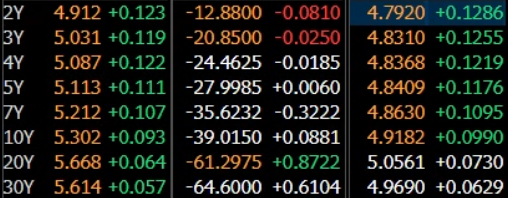
Source: Bloomberg, LLP | 9:30 AM NY Rates Snapshot
CHART 2 & 2A: SOFR SWAP RATES SURGE ON HOT SEPTEMBER CPI PRINT
SOFR swap rates gapped higher this morning after a hotter-than-anticipated September CPI print. The hot CPI pint will keep the market’s focus squarely on inflation as we wait for tomorrow’s PPI data and the looming FOMC policy meeting. I expect rates to remain biased to the upside for the near term. I think rates had drifted lower in recent days on hopes that CPI would post considerably lower than expected. That was not the case. Inflation remains the primary market concern.
US-IRAN WAR IMPACT: Key SOFR Swap Rate Movements Since the Onset of the US-Iran War
The 1-Year SOFR swap rate closed at 3.42% on Friday 2/27/2026 – it is currently trading at ~4.620%(+120.0 bps)
The 2-year SOFR swap rate closed at 3.21% on Friday 2/27/2026 – it is currently trading at ~4.792%(+158.2 bps)
The 3-year SOFR swap rate closed at 3.22% on Friday 2/27/2026 – it is currently trading at ~4.831%(+161.1 bps)
The 5-year SOFR swap rate closed at 3.22% on Friday 2/27/2026 – it is currently trading at ~4.841%(+162.1 bps)
The 10-year SOFR swap rate closed at 3.52% on Friday 2/27/2026 – it is currently trading at ~4.919%(+139.9 bps)
CHART 2:SOFR OIS Swap Rates – Prior 12-Months
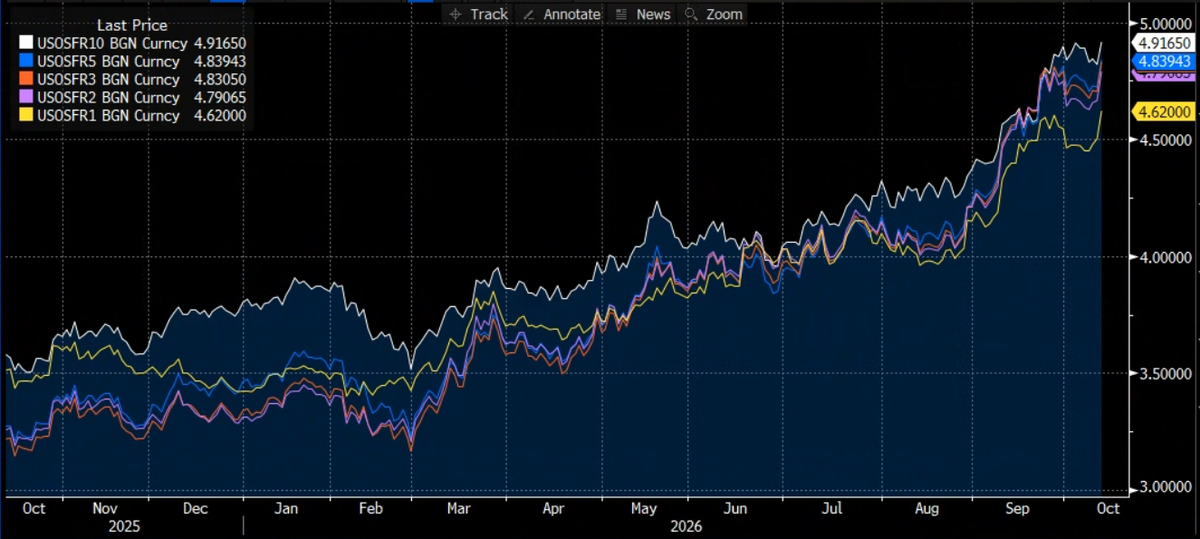
Source: Bloomberg, LLP | 1Y (gold line), 2Y (violet), 3Y (orange), 5Y (blue) and 10Y (white) SOFR ANNUAL OIS SWAP RATES; Year-To-Date 2026
CHART 2A:US Treasuries: Yield Overview – Prior 6-Months
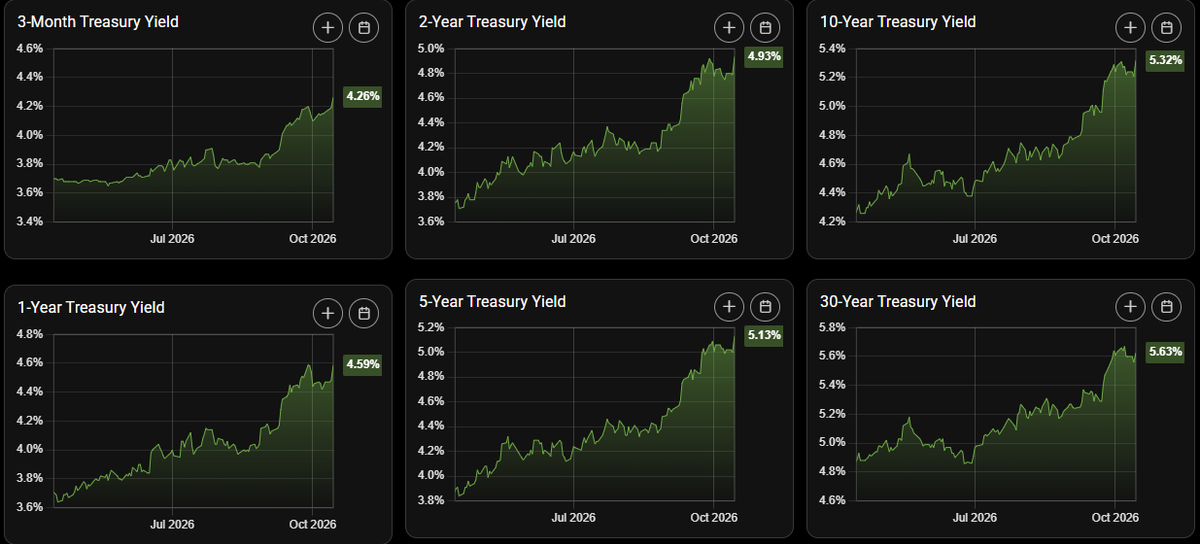
Source: StreetStats | US Treasury Yields – Prior Six Months
RCA Product & Pricing Update:
Product Spotlight: What We Are Seeing in the Rates & Derivatives Markets
The market is once again facing tremendous uncertainty surrounding the path forward for interest rates. Borrowers should be as nimble as possible in this market environment. Cap purchasers should onboard as quickly as possible – there is no cost to onboard. It is important to be in a position to take advantage of market opportunities quickly and efficiently.
There is an increasing interest in exploring interest rate swaps as a possible hedge alternative. IR Swaps lock in a synthetic fixed rate and do not require an upfront premium. Unlike an interest rate cap, however, swaps are secured derivatives, so the counterparty selection process is more challenging with a swap. It is often challenging to place a swap away from the lender or incumbent relationship bank. There are also additional variables that factor into the decision to pursue an interest rate swap, or to unwind an existing swap. With the uptick in swap rates recently, we are also seeing an increase in swap termination requests. Please let us know if you would like to learn more about interest rate swaps, or swap terminations. RCA offers a full range of Derivative Advisory services.
Given the high-level of uncertainty surrounding forward rates, many clients are grappling with when or if to extend. This is a difficult question – our advice has been to monitor the market closely and be on-boarded and ready to trade, should the market move in your favor. We also advise borrowers to check the market pricing for extensions. Market price discovery is a key component to any cap transaction – new caps, extensions, or terminations.
We are still seeing some residual demand for interest rate floor indications – to offset high loan floors or simply to benefit from declining variable rates. Borrowers who have “floors” embedded in their loans have been considering purchasing a separate, stand-alone interest rate floor to offset the loan floor.
Interest Rate Cap Hub: Cap Pricing & Rate Volatility Update for 10/14/2026
Current 1-Month SOFR = 3.92465% (Prior Day’s Reset: 3.92490%)
Market uncertainty surrounding the path forward for interest rates remains elevated
Cap Pricing Matrix:1-Month Term SOFR Cap Premiums: Week-On-Week
Notional Amount | Tenor | Strike Rate | ~Cap Premiums 10/7/26 | ~Cap Premiums 10/14/26 Open* |
,$25,000,000 | 1-Year | 3.50% | ~$252k | ~$249k |
$25,000,000 | 1-Year | 4.50% | ~$78k | ~$73k |
$25,000,000 | 2-Year | 3.50% | ~$602k | ~$582k |
$25,000,000 | 2-year | 4.50% | ~$249k | ~$234k |
$25,000,000 | 3-Year | 3.50% | ~$966k | ~$924k |
$25,000,000 | 3-Year | 4.50% | ~$459k | ~$432k |
*Indications as of Market Open. Premium levels provided are indications only and subject to frequent change.
CHART 3:Historical Volatility: MOVE Composite US Treasury Yield Volatility Index – Year-To-Date 2026
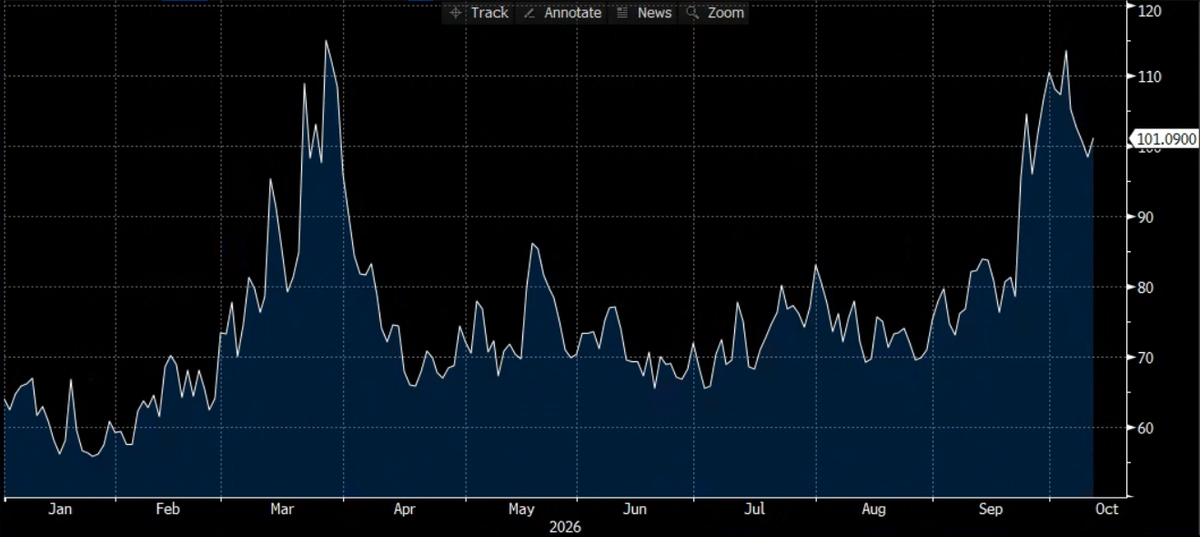
Source: Bloomberg, LLP | HISTORICAL US TREASURY YIELD VOLATILITY, “MOVE” INDEX – YTD 2026
^NOTE:RATE MARKETS CAN BE VOLATILE - MARKET DYNAMICS AND PRICING CAN CHANGE VERY QUICKLY IN THIS MARKET ENVIRONMENT.
**WE RECOMMEND YOU CALL US FOR ACCURATE, UP-TO-THE-MINUTE CAP INDICATIONS.**
Please contact us if you would like to discuss an upcoming rate cap or rate cap extension, explore ways to reduce or eliminate escrow deposits for replacement caps or learn more about interest rate Caps, Floors, Swaps or Swaptions. RCA can also assist you with the voluntary early termination of your cap or swap.
HedgeWithAnEdge-TheRCAEdge!
Disclaimer: The information provided in this communication is intended for discussion purposes only. Nothing presented in this communication should be taken as a recommendation or forecast. All market data shown is indicative only and subject to change depending on current market conditions. The information in this publication is confidential and is intended for the recipient only.