Rate Markets Update · Thursday, November 19, 2026
Rates Tick Higher as Market Prepares to Absorb Anthropic IPO
- Traders Monitor Crude Oil Prices and Prepare for Key Economic Data Due Next Week
Flash Update: US RATE MARKETS – THURSDAY NOVEMBER 19, 2026
US Treasury yields and SOFR swap rates are ticking slightly higher this morning as markets prepare to absorb the highly anticipated Anthropic IPO
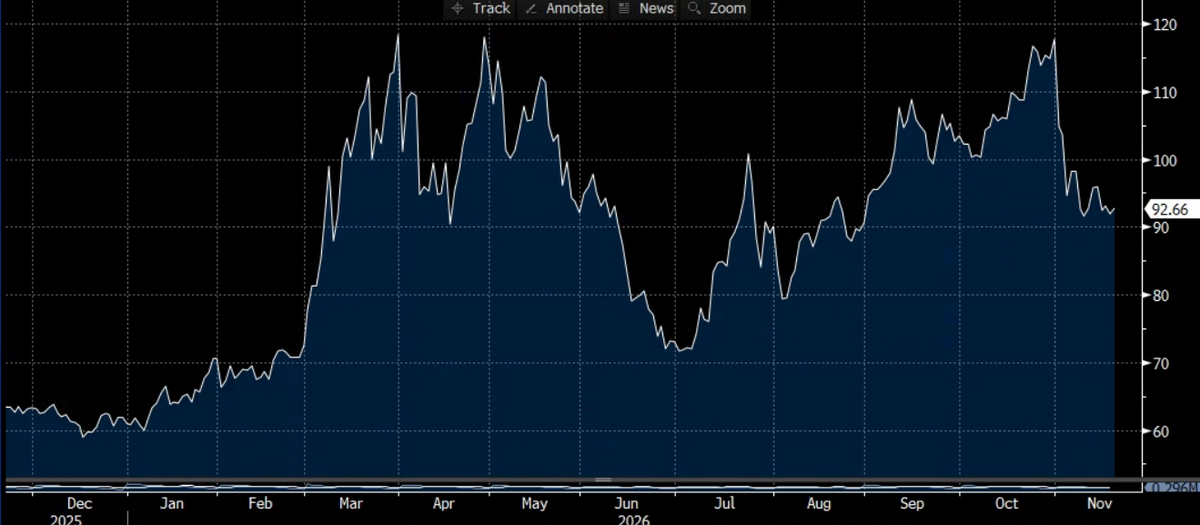
The price of Brent crude oil slid a touch lower this morning on a positive supply outlook, but so far, we have not seen a meaningful dip in term rates
Performance in the AI-led tech sector will continue to be a major market theme that I expect to impact markets for the near term
There is a full plate of Fed speakers scheduled to speak between now and 11/25/2026; The Fed’s “pre-meeting” external blackout period begins on 11/25
Odds for a 25 bp rate increase in December have stabilized at ~99.0%, Odds for a consecutive 25 bp rate hike in January have crept up to ~74.4%
Longer term, the results of the US midterm elections are likely to have significant US policy ramifications, which in turn could impact the outlook for interest rates and monetary policy
Next up for economic data: October PCE and 3Q GDP (2ND revision) are due for release on Wednesday, 11/25 at 8:30 AM
Short-term SOFR swap rates are trading up ~1-3 bps this morning, depending on tenor
Medium-term SOFR swap rates are up ~1-2 bps currently, depending on tenor
Long-end SOFR swap rates are trading up ~1-2 bps this morning, depending on tenor
Good morning – US Treasury yields and SOFR swap rates are a touch higher this morning as trader’s focus on the highly anticipated Anthropic IPO. The record setting Anthropic IPO breathed new life into the faltering “AI trade”. As such traders and investors may shun Treasuries to take advantage of attractive dip buying, which could lead to slightly higher rates today as Treasuries sell-off. Get ready!
Market participants are also bracing for the release of key economic data due next week, and for new developments in the evolving situation in the Middle East. The price of Brent crude oil continues to tick lower, but so far, we are not seeing a meaningful dip in rates. I think traders need to be convinced the dip in oil will hold. Progress on the diplomatic front would bolster that sentiment significantly. Headlines today show the opposite – tensions are once again intensifying in the Middle East.
I expect rates to remain volatile, but mostly range bound, as the market continues to monitor the myriad market forces at work currently. There is a full plate of Fed speakers scheduled before the pre-meeting communications blackout begins on 11/25. I also anticipate that markets will continue to focus on the price of crude oil, the outlook for inflation and tech sector (AI) performance for the remainder of this week. We will see some key data released next week (PCE. GDP) that may help solidify the path forward for the Fed.
As anticipated, minutes of the October FOMC meeting showed the vast majority of participants saw further rate hikes as a matter of when, not if. The recent “hold” decision basically bought the Fed time to assess September’s rate hike and changes in financial conditions. The minutes showed that support for an immediate hike extended beyond the two dissents — two non-dissenting officials were open to a jumbo move in December if inflation stayed hot. The minutes further revealed that “almost all” participants judged that further tightening would likely be appropriate. Some said market pricing for a December hike and additional tightening next year was broadly consistent with their preferred path. The FOMC debate centered mainly on the pace of tightening. Bottom line: prepare for a 25 bp rate hike in December and for a possible consecutive 25 bp rate hike in January.
CHARTS OF THE DAY:
A: Hawkish Fed-Speak Shows FOMC Ready to Hike
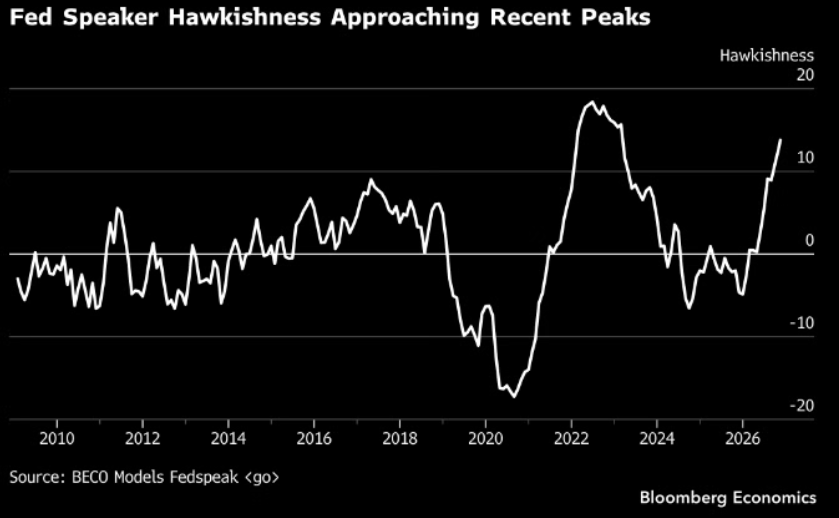
Source: Bloomberg, LLP | BLOOMBERG FED-SPEAK INDEX SINCE 2009
B: Schedule of Fed Speeches Through 11/25/2026
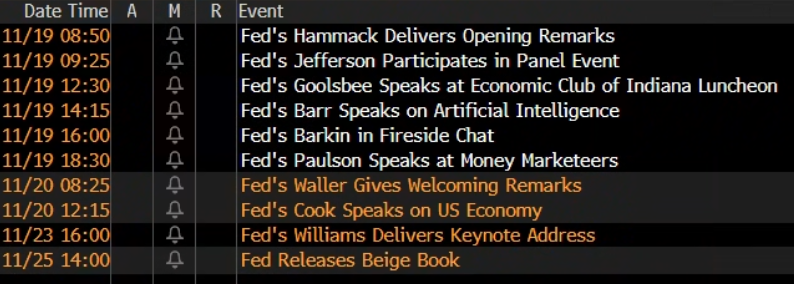
Source: BLOOMBERG, LLP | SCHEDULE OF FED SPEECHES THROUGH 11/25/2026
C: Brent Crude Oil Declines but So Far, No Meaningful Dip in Rates as AI Grabs the Spotlight
Source: BLOOMBERG, LLP | PRICE OF BRENT CRUDE OIL – PRIOR 12-MONTHS
SOFR Swap Market - Quick Summary:
The 1Y SOFR swap rate is trading up ~1-2 bps this morning. 2Y and 3Y SOFR swap rates are currently trading up ~1-3 bps. 5Y and 10Y SOFR swap rates are trading up ~1-3 bps this morning. The very back-end of the swap curve (20Y and 30Y) is currently up ~1-2 bps from last night’s closing levels.
“Key News” the market is tracking includes:
Geopolitical developments will continue to weigh on markets. Developments in the US/Iran “war”, and the direction of crude oil prices, will continue to captivate the market’s attention.
Lack of forward guidance from the Fed is forcing traders to pay more attention to economic data – this may fundamentally change the way markets position for and react to Fed rate decisions going forward. FOMC Chair Warsh’s vague and ambiguous press conference last week confused markets and is likely to lead to increase volatility as we approach the next Fed meeting.
Market participants will now shift focus to the policy and economic ramifications of the US midterm elections.
Traders are also focused on the performance of the AI sector and more broadly, on what AI “really means” for the US and global economies. Overall market sentiment, and perhaps even economic performance, may be impacted by AI for the foreseeable future.
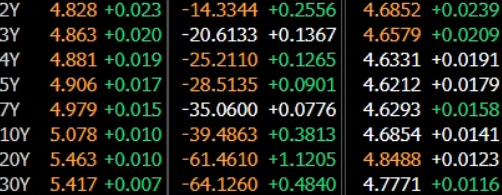
CHART 1: US RATES SNAPSHOT: 9:00 AM Eastern
Chart 1 Key:
Far Left Columns: US Treasury Yields & Change on Day (bps)
Center Columns: SOFR OIS Swap Spreads (bps) & Change on Day (bps)
Far Right Columns: SOFR OIS Swap Rates & Change on Day (bps)
Please note: Market levels can change rapidly – rate cap premiums are subject to a dynamic market that can change frequently.
UST YIELDS | SWAP SPREADS | SOFR SWAP RATES
Source: Bloomberg, LLP | 9:00 AM NY Rates Snapshot
CHART 2 & 2A: SOFR SWAP RATES SLIGHTLY HIGHER AS MARKET PREPARES TO ABSORB ANTHROPIC IPO
SOFR swap rates are ticking a touch higher on the open this morning, as traders prepare to absorb the Anthropic IPO, which has revitalized appetite for the AI sector. Rates may drift higher today if portfolio managers reallocate assets from US Treasuries into equities. Traders will continue to hear from Fed officials throughout the day. I expect traders to be paying close attention to the Fed-speak we hear between now and the “quiet period” for clues about forward monetary policy. Right now, traders are unsure if a 50 bp hike is really on the table for December (current market implied odds for a 50 bp hike in December are steady at ~9.5%. We will see if the upcoming Fed-speak and key economic data help to sharpen the market’s outlook.
Prepare for increased levels of rate volatility in the coming weeks.
US-IRAN WAR IMPACT: Key SOFR Swap Rate Movements Since the Onset of the US-Iran War
The 1-Year SOFR swap rate closed at 3.42% on Friday 2/27/2026 – it is currently trading at ~4.628% (+120.8 bps)
The 2-year SOFR swap rate closed at 3.21% on Friday 2/27/2026 – it is currently trading at ~4.683% (+147.3 bps)
The 3-year SOFR swap rate closed at 3.22% on Friday 2/27/2026 – it is currently trading at ~4.656% (+143.6 bps)
The 5-year SOFR swap rate closed at 3.22% on Friday 2/27/2026 – it is currently trading at ~4.619% (+139.9 bps)
The 10-year SOFR swap rate closed at 3.52% on Friday 2/27/2026 – it is currently trading at ~4.684% (+116.4 bps)
CHART 2: SOFR OIS Swap Rates – Prior 12-Months
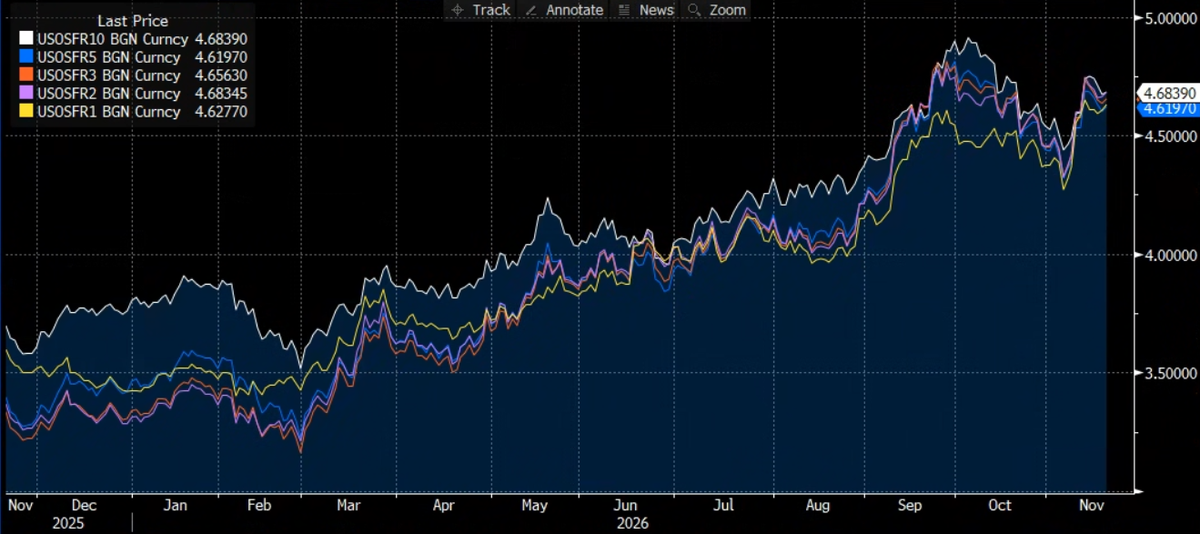
Source: Bloomberg, LLP | 1Y (gold line), 2Y (violet), 3Y (orange), 5Y (blue) and 10Y (white) SOFR ANNUAL OIS SWAP RATES; Year-To-Date 2026
CHART 2A: US Treasuries: Yield Overview – Prior 6-Months
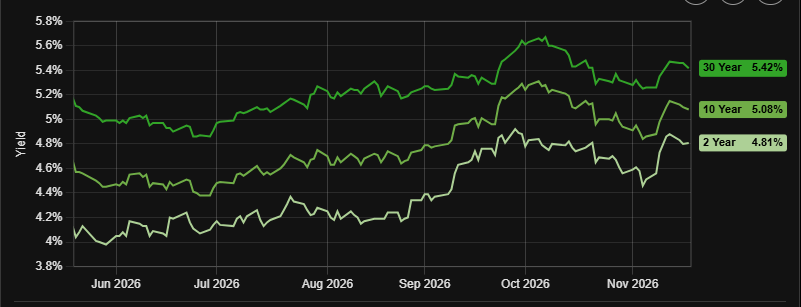
Source: StreetStats | US Treasury Yields – Prior Six Months
RCA Product & Pricing Update:
Product Spotlight: What We Are Seeing in the Rates & Derivatives Markets
The market is once again facing tremendous uncertainty surrounding the path forward for interest rates. Borrowers should be as nimble as possible in this market environment. Cap purchasers should onboard as quickly as possible – there is no cost to onboard. It is important to be in a position to take advantage of market opportunities quickly and efficiently.
There is an increasing interest in exploring interest rate swaps as a possible hedge alternative. IR Swaps lock in a synthetic fixed rate and do not require an upfront premium. Unlike an interest rate cap, however, swaps are secured derivatives, so the counterparty selection process is more challenging with a swap. It is often challenging to place a swap away from the lender or incumbent relationship bank. There are also additional variables that factor into the decision to pursue an interest rate swap, or to unwind an existing swap. With the uptick in swap rates recently, we are also seeing an increase in swap termination requests. Please let us know if you would like to learn more about interest rate swaps, or swap terminations. RCA offers a full range of Derivative Advisory services.
Given the high-level of uncertainty surrounding forward rates, many clients are grappling with when or if to extend. This is a difficult question – our advice has been to monitor the market closely and be on-boarded and ready to trade, should the market move in your favor. We also advise borrowers to check the market pricing for extensions. Market price discovery is a key component to any cap transaction – new caps, extensions, or terminations.
We are still seeing some residual demand for interest rate floor indications – to offset high loan floors or simply to benefit from declining variable rates. Borrowers who have “floors” embedded in their loans have been considering purchasing a separate, stand-alone interest rate floor to offset the loan floor.
Interest Rate Cap Hub: Cap Pricing & Rate Volatility Update for 11/19/2026
Current 1-Month SOFR = 4.00691% (Prior Day’s Reset: 4.00170%)
1-Month Term SOFR continues to tick higher on expectations the Fed will raise rates 25 bps in December
SOFR swap rates have held mostly steady and rate volatility has ticked slightly higher so far this week, holding cap premiums mostly in check
Market uncertainty surrounding the path forward for interest rates remains elevated
Cap Pricing Matrix: 1-Month Term SOFR Cap Premiums: Week-On-Week
Notional Amount | Tenor | Strike Rate | ~Cap Premiums 11/12/26 | ~Cap Premiums 11/19/26 Open* |
,$25,000,000 | 1-Year | 3.50% | ~$261k | ~$274k |
$25,000,000 | 1-Year | 4.50% | ~$81k | ~$89k |
$25,000,000 | 2-Year | 3.50% | ~$566k | ~$595k |
$25,000,000 | 2-year | 4.50% | ~$224k | ~$247k |
$25,000,000 | 3-Year | 3.50% | ~$868k | ~$910k |
$25,000,000 | 3-Year | 4.50% | ~$390k | ~$423k |
*Indications as of Market Open. Premium levels provided are indications only and subject to frequent change.
CHART 3: Historical Volatility: MOVE Composite US Treasury Yield Volatility Index – Year-To-Date 2026
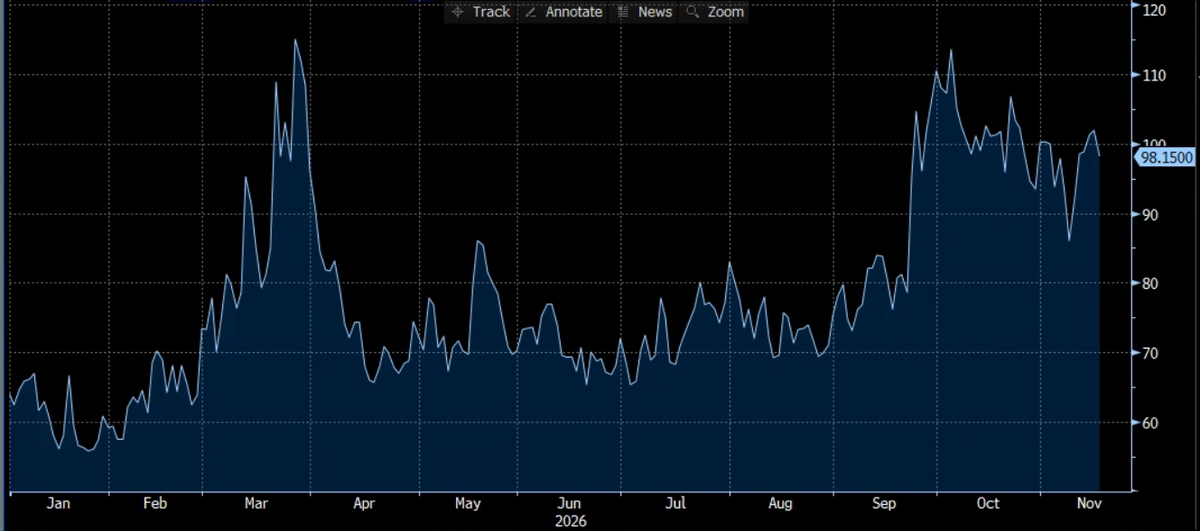
Source: Bloomberg, LLP | HISTORICAL US TREASURY YIELD VOLATILITY, “MOVE” INDEX – YTD 2026
^NOTE: RATE MARKETS CAN BE VOLATILE - MARKET DYNAMICS AND PRICING CAN CHANGE VERY QUICKLY IN THIS MARKET ENVIRONMENT.
**WE RECOMMEND YOU CALL US FOR ACCURATE, UP-TO-THE-MINUTE CAP INDICATIONS.**
Please contact us if you would like to discuss an upcoming rate cap or rate cap extension, explore ways to reduce or eliminate escrow deposits for replacement caps or learn more about interest rate Caps, Floors, Swaps or Swaptions. RCA can also assist you with the voluntary early termination of your cap or swap.
Hedge With An Edge - The RCA Edge!
Disclaimer: The information provided in this communication is intended for discussion purposes only. Nothing presented in this communication should be taken as a recommendation or forecast. All market data shown is indicative only and subject to change depending on current market conditions. The information in this publication is confidential and is intended for the recipient only.