

Rate Markets Update · Monday, January 12, 2026
US Central Bank Served Grand Jury Subpoenas
- Geopolitical Tensions Rise
- Rates Tick Higher, Yield Curve Steepens
Flash Update: US RATE MARKETS – MONDAY JANUARY 12, 2026
UST yields and SOFR swap rates are drifting higher and the yield curve is steepening this morning
Traders mostly shrugged-off Friday’s release of the December jobs data – the market’s reaction was muted
Traders continue to closely monitor geopolitical developments in multiple “hot spots”
Geopolitical tensions ticked higher over the weekend as the unrest in Iran intensified
The US justice department announced a criminal investigation into Chairman Powell and the US Central Bank
The market reaction to the Powell announcement has been somewhat minimal so far, but market jitters escalated
The “Powell news” was the primary catalyst for higher rates this morning – global markets will be tracking this developing story closely
The Supreme Court did not rule on “tariffs” Friday – the decision was postponed; A ruling could come this week
The tariff ruling could potentially create additional rate volatility as the market digests the Supreme Court’s decision
We are tracking developments with Fannie Mae and Freddie Mac, which could have ramifications for the rates market
Next up for data: December CPI data prints tomorrow, 1/13 at 8:30 AM
The next FOMC rate decision is due Wednesday, January 28, 2026 at 2:00 PM
Short-end SOFR swap rates are trading up ~1 bp this morning, depending on tenor
Long-end SOFR swap rates are currently trading up ~2-4 bps, depending on tenor
Good Morning – US Treasury yields and SOFR swap rates ticked higher this morning and the yield curve steepened after Fed Chairman Jerome Powell announced last night that the US Central Bank had been served grand jury subpoenas, an unprecedented occurrence. On Sunday evening, Powell said the US central bank had been served grand jury subpoenas that were related to his congressional testimony on ongoing renovations of the Fed’s headquarters. The justice department investigation is the latest in a series of confrontations between the Fed and the Trump Administration, which include efforts to fire Governor Lisa Cook and repeated calls for aggressive interest rate cuts. So far the market reaction has been minimal, but rates are now biased higher and the yield curve is steepening.
Other news the market is tracking:
Geopolitical developments. Geopolitical tensions are running high, and that is not likely to abate anytime soon. Markets are paying particular attention to the situations in Venezuela and Iran. So far, the market’s reaction has been relatively muted.
The Supreme Court ruling on tariffs was not released on Friday. The decision was postponed and is now expected to come at some point this week. The SCOTUS ruling could definitely have market implications. Currently, the market believes the Supreme Court will rule against the President. Economists are unsure about the market impact of the decision – either way, the ruling is likely to be a catalyst for elevated rate volatility.
President Trump has “asked” Fannie Mae and Freddie Mac to purchase ~$200 billion in mortgage-backed securities in order to facilitate lower mortgage rates. The market impact is uncertain at the moment, but if this does happen, it could certainly impact rates and the shape of the yield curve, at least in the short-term. We will continue to track this developing story.
The US Justice Department investigation into the US Central Bank and Chairman Powell could be a key market catalyst this week, and beyond. Chairman Powell has pushed back hard on the subpoenas, saying they are “political retribution” for not lowering rates and amount to “intimidation”. He has stated he will not resign. Ultimately, we are in uncharted waters on this – at the least, it is likely to increase volatility and uncertainty while the situation plays out.
Bottom-line, there are many potential market catalysts for traders to monitor and manage at the moment.
SOFR Swap Rate Summary: The 1Y SOFR swap rate is trading up ~1 bp this morning. 2Y and 3Y SOFR swap rates are currently trading up ~1 bp. 5Y and 10Y SOFR swap rates are currently trading up ~1-2 bps. The very back-end of the swap curve is currently trading up ~2-4 bps from Friday’s closing levels. Please note: Market levels can change rapidly – rate cap premiums are subject to a dynamic market that can change frequently.
CHART 1:US RATES SNAPSHOT: 9:30 AM Eastern
*For SOFR Swap Rates & Change-On-Day (In Bps): Refer Two Far Right Columns (SOFR Swap Rates)
UST YIELDS | SWAP SPREADS | SOFR SWAP RATES
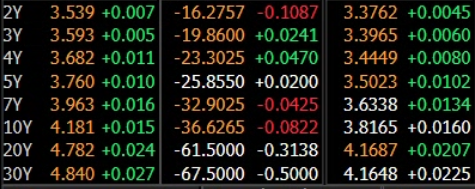
Source: Bloomberg, LLP | 9:30 AM NY Rates Snapshot
CHART 2, 2A & 2B: SOFR SWAP RATES TICK HIGHER AS MARKET REACTS TO RENEWED FED TENSIONS; 10Y US T-YIELDS TREND HIGHER
SOFR swap rates are a tick or two higher this morning, as traders digest the news that the US Central Bank has been issues subpoenas by the US Justice Department. This is a developing story we will be tracking closely. This situation represents a renewed threat to Fed independence, which historically, has been a key component of US monetary policy. The uptick in rates and steeper yield curve tell me the market is very nervous and highly uncertain about the Fed situation. That concern is likely to ripple globally. As such, I expect rates to be biased (slightly) to the upside and the yield curve to continue to steepen. The main market fear is that a removal of Fed independence will lead to aggressive and unnecessary rate cuts which will lead to dramatically higher inflation.
Traders continue to assess the current risk landscape and the path forward for interest rates. Market participants will continue to monitor the potential market catalysts mentioned above. Traders will now look ahead to the December CPI report due tomorrow, 1/13. Despite the “hype” surrounding the Employment Report, the reaction was relatively muted. Overall, swap rates remain range bound as the market seeks direction. Swap rates across the curve continue to trade in a ~10-15 bp trading range.
10-Year US Treasury yields continue to edge higher, which is not providing any real relief on mortgage rates. The aforementioned Fed-related higher inflation fears are the primary reasons 10-year Treasury yields continue to move higher. Market technicians have flagged 4.20% as a key yield-point for the 10-year note. Should we break through 4.20%, the next stop for 10-year Treasury yields could be 4.50%.
CHART 2:Short-End SOFR Swap Rates – Prior 30 Days
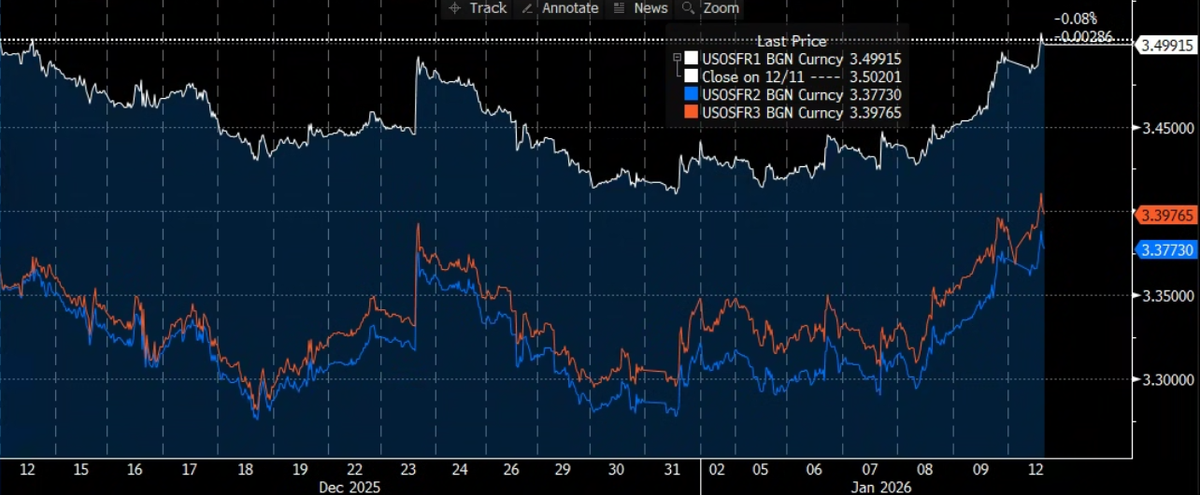
Source: Bloomberg, LLP | 1Y (white), 2Y (blue) & 3Y (orange) SOFR SWAP RATES, PRIOR 30 DAYS
CHART 2A:Long-End SOFR Swap Rates – Prior 30 Days
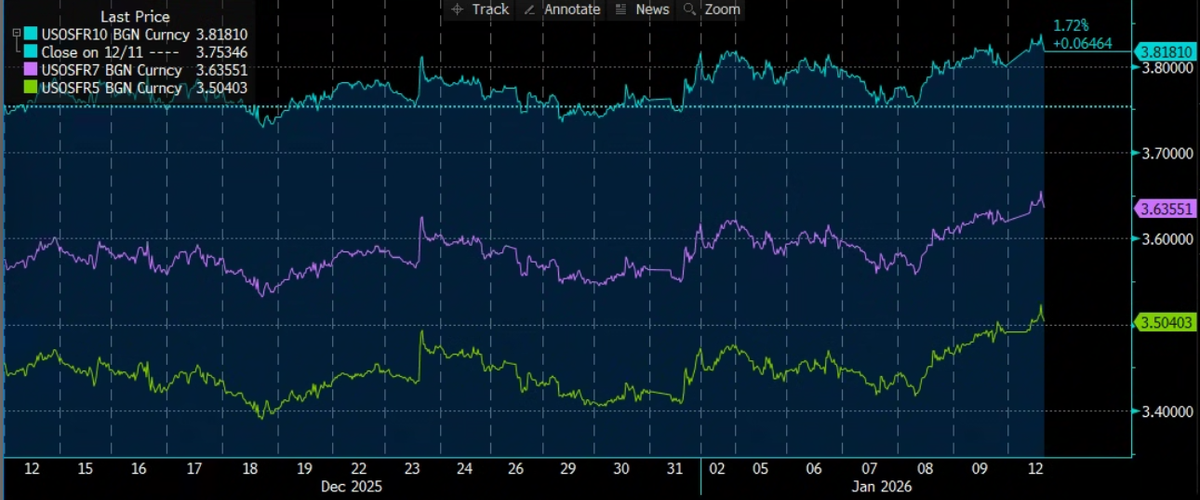
Source: Bloomberg, LLP | 5Y (green), 7Y (purple) & 10Y (light blue) SOFR SWAP RATES, PRIOR 30 DAYS
CHART 2B:Threats To Fed Independence Pushes 10-Year Yields Higher, Steepens Treasury Yield Curve
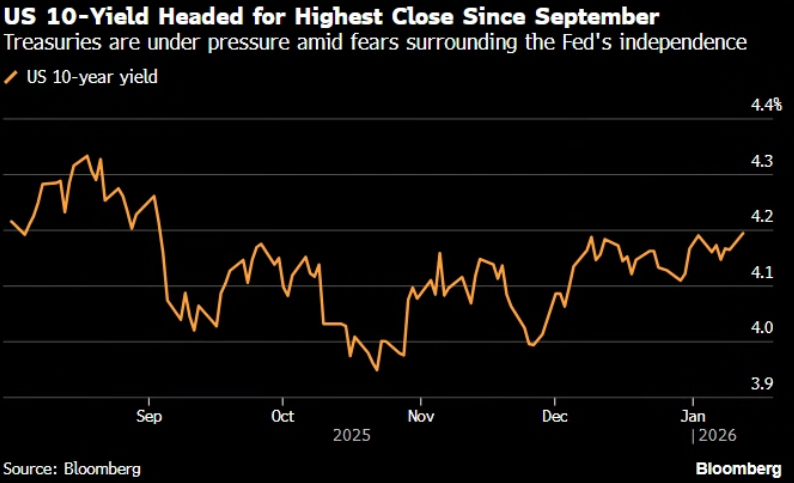
Source: Bloomberg, LLP | 10Y UST NOTE YIELD SINCE SEPTEMBER 2025
CHART 3: DECEMBER CPI PREVIEW
Next up for economic data will be the release of December CPI on Tuesday, 1/13 at 8:30 AM. With inflation still in focus, traders will be keen to see current inflation data. December consensus CPI expectations are as follows: MoM headline CPI, 0.3%; MoM Core CPI, 0.3%. Note: November MoM CPI data was not released. YoY headline CPI, 2.7% (vs. 2.7% the prior month); YoY Core CPI, 2.7% (vs. 2.6% prior). Traders will be paying close attention to the CPI data, but it will be interesting to see if they shrug-off the CPI data like they did with Friday’s jobs data. There are many potential market catalysts for traders to monitor and manage at that the moment.
CHART 3:December CPI Expectations
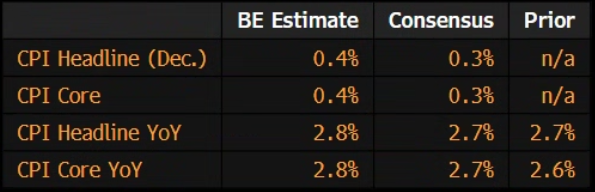
Source: Bloomberg, LLP | DECEMBER CPI EXPECTATIONS – MARKET CONSENSUS & BLOOMBERG ECONOMISTS
Disclaimer: The information provided in this communication is intended for discussion purposes only. Nothing presented in this communication should be taken as a recommendation or forecast. All market data shown is indicative only and subject to change depending on current market conditions. The information in this publication is confidential and is intended for the recipient only.