

Rate Markets Update · Wednesday, January 14, 2026
PPI, Retail Sales Data Results Mixed
- Iran Protests in Focus for Market
- Rates Drift Lower but Volatility Increases
Flash Update: US RATE MARKETS – WEDNESDAY JANUARY 14, 2026
UST yields and SOFR swap rates are drifting lower this morning as the market monitors multiple potential catalysts
YoY PPI rose more than expected in November due to a jump in energy costs
November Retail Sales data rose by the most since July, fueled by auto purchases and resilient holiday shopping
Traders continue to closely monitor geopolitical developments in multiple “hot spots”
The developing situation in Iran is captivating traders globally and is likely to remain a front-and-center market catalyst this week
Traders continue to monitor developments with the announced DOJ Criminal investigation into Chair Powell and the US Central Bank
The market reaction to the Powell announcement has been somewhat minimal so far, but market jitters have escalated
The Supreme Court did not rule on “tariffs” last week – the decision was postponed
A SCOTUS ruling on tariffs is now anticipated to come “at some point in January”, perhaps as early as today
The tariff ruling could potentially create additional rate volatility as the market reacts to the Supreme Court’s decision
We are tracking developments with Fannie Mae and Freddie Mac, which could have ramifications for the rates market
Next up for data: Weekly Jobless & Continuing Claims and Import/Export Price Index data print tomorrow, 1/15 at 8:30 AM
The next FOMC rate decision is due Wednesday, January 28, 2026 at 2:00 PM
Short-end SOFR swap rates are trading down ~1-2 bps this morning, depending on tenor
Long-end SOFR swap rates are currently trading down ~1-3 bps, depending on tenor
Good Morning – US Treasury yields and SOFR swap rates are drifting lower this morning as the market digests stale economic data and a host of other potential market catalysts. Rates initially dropped this morning on the worsening situation in Iran, then bounced around after the 8:30 AM economic data was released. Currently, SOFR swap rates are down 1-2 bps across the curve. Futures implied odds for a January rate cut have dropped this week to a paltry 2.8%.
Other news the market is tracking:
Geopolitical developments. Geopolitical tensions are running high, and that is not likely to abate anytime soon. Markets are paying particular attention to the situations in Venezuela and Iran. The unrest in Iran has significantly intensified over the past few days and is garnering global attention. President Trump urged Iranian dissidents to continue protesting against the regime of Supreme Leader Ayatollah Ali Khamenei and said he would “act accordingly” once he assesses how many demonstrators have been killed. We are seeing a potential safe haven trade taking shape as a result of the President’s comments – US Treasury rates are a touch lower this morning.
The Supreme Court ruling on tariffs was not released on Friday. The decision was postponed and is now expected to come at “some point in January”. The SCOTUS ruling could definitely have market implications. Currently, the market believes the Supreme Court will rule against the President. Economists are unsure about the market impact of the decision – either way, the ruling is likely to be a catalyst for elevated rate volatility.
President Trump has “asked” Fannie Mae and Freddie Mac to purchase ~$200 billion in mortgage-backed securities in order to facilitate lower mortgage rates. The market impact is uncertain at the moment, but if this does happen, it could certainly impact rates and the shape of the yield curve, at least in the short-term. We will continue to track this developing story.
The US Justice Department investigation into the US Central Bank and Chairman Powell could be a key market catalyst going forward. Chairman Powell has been defiant and has pushed back hard on the subpoenas, saying they are “political retribution” for not lowering rates and amount to “intimidation”. He has stated he will not resign. Ultimately, we are in uncharted waters on this – at the least, it is likely to increase volatility and uncertainty while the situation plays out.
There are a host of Fed officials scheduled to speak the remainder of this week. Five Fed officials are on the tape today, beginning around 10:00 AM. The Fed’s pre-meeting external “communications” blackout begins on January 17th.
Markets face a packed agenda of potential catalysts the rest of the week, including geopolitical tensions, big bank earnings, a slate of Fed speakers, US economic data and a possible Supreme Court ruling on tariffs. Investors will also follow rhetoric around Greenland as diplomats from the island and Denmark meet at the White House. President Trump posted on Truth Social that Greenland was vital to US plans to build a “Golden Dome” missile defense shield. Bottom-line, there are many potential market catalysts for traders to monitor and manage at the moment.
SOFR Swap Rate Summary: The 1Y SOFR swap rate is trading down ~1-2 bps this morning. 2Y and 3Y SOFR swap rates are currently trading down ~1-2 bps. 5Y and 10Y SOFR swap rates are currently trading down ~2-3 bps. The very back-end of the swap curve is currently trading flat to down ~1-2 bps from yesterday’s closing levels. Please note: Market levels can change rapidly – rate cap premiums are subject to a dynamic market that can change frequently.
CHART 1:US RATES SNAPSHOT: 9:30 AM Eastern
*For SOFR Swap Rates & Change-On-Day (In Bps): Refer Two Far Right Columns (SOFR Swap Rates)
UST YIELDS | SWAP SPREADS | SOFR SWAP RATES
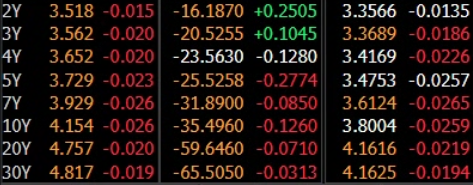
Source: Bloomberg, LLP | 9:30 AM NY Rates Snapshot
CHART 2, 2A & 2B: SOFR SWAP RATES DRIFT SLIGHTLY LOWER; RANGE BOUND 10-YEAR UST YIELD WAITS FOR CATALYST
SOFR swap rates are holding mostly steady this morning – right now swap rates are a tick or two lower. It was no surprise to me that the market largely ignored the November PPI and retail sales data – it is stale data as this point and only serves as historical reference. I suspect that traders are being defensive at the moment and reluctant to materially move rates, given the escalating market uncertainty and wide range of potential market catalysts currently at work. Those catalysts include the upcoming FOMC meeting on January 28th.
The 10-year UST note yield has been stuck in a narrow corridor since early September, as markets struggle to get a clear read on the economy and the path forward for interest rates. Market pundits suspect that traders may be waiting to see the results of the January FOMC meeting and Chairman Powell’s press conference. The Fed meeting and Powell presser may set the tone for interest rates, at least until Powell’s tenure as Chairman ends in May.
CHART 2:Short-End SOFR Swap Rates – Prior 30 Days
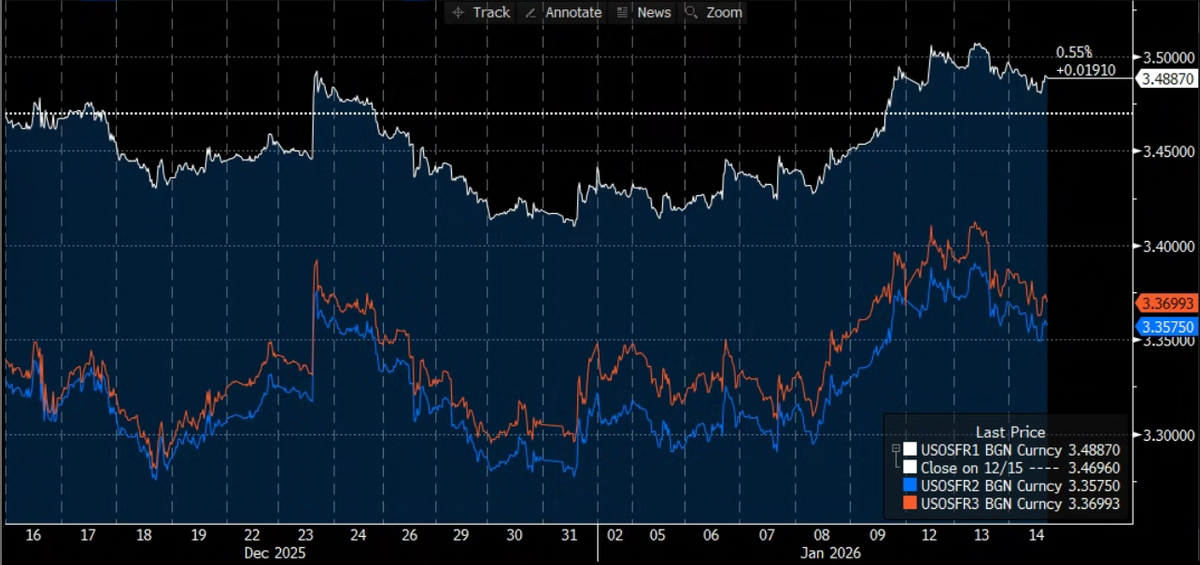
Source: Bloomberg, LLP | 1Y (white), 2Y (blue) & 3Y (orange) SOFR SWAP RATES, PRIOR 30 DAYS
CHART 2A:Long-End SOFR Swap Rates – Prior 30 Days
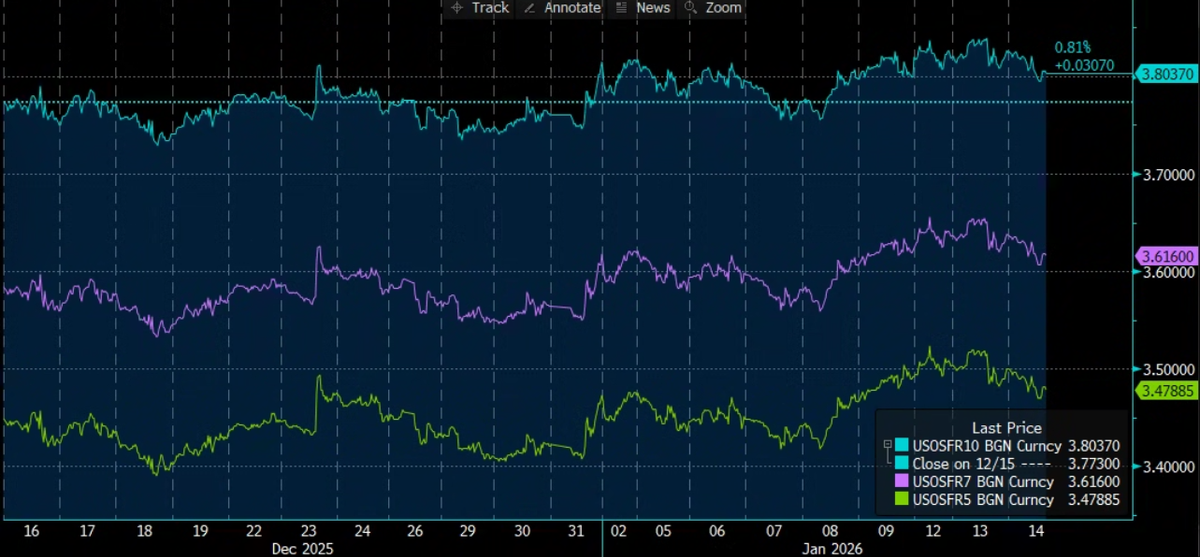
Source: Bloomberg, LLP | 5Y (green), 7Y (purple) & 10Y (light blue) SOFR SWAP RATES, PRIOR 30 DAYS
CHART 2B:Range Bound 10-Year UST Yields Await Catalyst
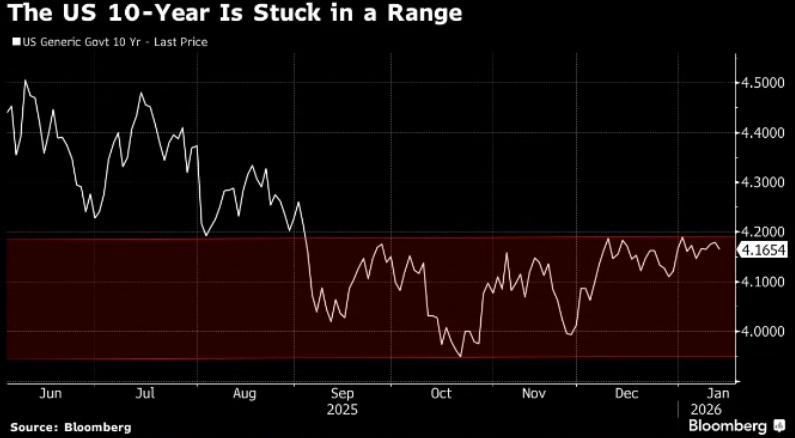
Source: Bloomberg, LLP | 10Y UST NOTE YIELD SINCE JUNE 2025
CHART 3 & 3A: NOVEMBER PPI & NOVEMBER RETAIL SALES RECAP – MIXED DATA CLOUDS RATE OUTLOOK AHEAD OF FOMC MEETING
US wholesale inflation picked up slightly in November from a month earlier on a jump in energy costs. Headline PPI rose 0.2% in November after climbing 0.1% in the prior month. The PPI report released this morning, which also included the first estimate of October wholesale price data, was delayed by the 43-day federal shutdown. Compared with a year earlier, headline PPI advanced 3%. Core PPI, which excludes food and energy prices, was unchanged from the prior month (0.2%) and climbed 3% from November 2024.
US Retail Sales increased in November by more than forecast, fueled by a rebound in auto purchases and resilient holiday shopping. The value of retail purchases, not adjusted for inflation, increased 0.6% in November after a downwardly revised 0.1% drop in October. Excluding automobiles, November sales climbed 0.5%.
Next up for economic data will be the release of Weekly Jobless Claims and Continuing Claims, the Import Price Index and the Export Price Index tomorrow at 8:30 AM.
CHART 3:November PPI Recap & Historical Data
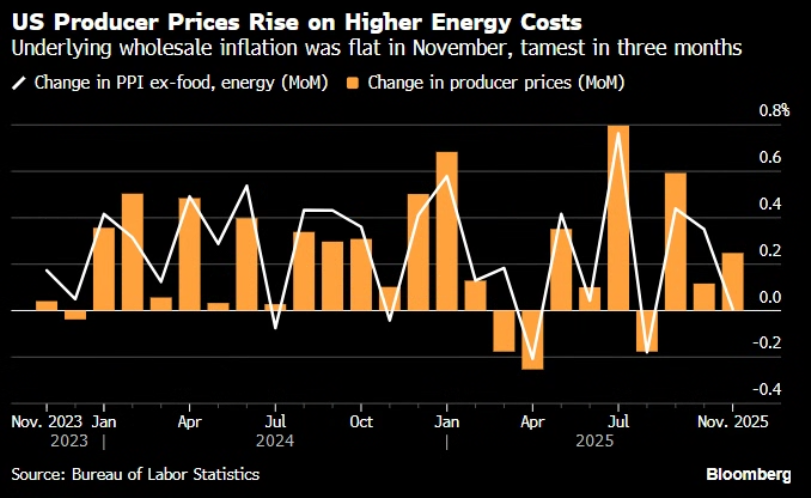
Source: Bloomberg, LLP | November PPI Recap
CHART 3A:November Retail Sales Recap
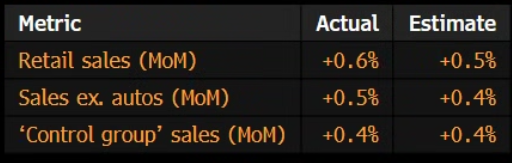
Source: Bloomberg, LLP | November Retail Sales Recap
Disclaimer: The information provided in this communication is intended for discussion purposes only. Nothing presented in this communication should be taken as a recommendation or forecast. All market data shown is indicative only and subject to change depending on current market conditions. The information in this publication is confidential and is intended for the recipient only.