

Rate Markets Update · Thursday, January 22, 2026
Rates Tick Higher as 3q GDP Revised Higher
- Traders Monitor Geopolitical Developments
- FOMC Meets Next Week
Flash Update: US RATE MARKETS – THURSDAY JANUARY 22, 2026
UST yields and SOFR swap rates are ticking higher this morning on better-than-expected economic data
3Q GDP was revised higher (4.4%) and weekly jobless claims were lower-than-forecasted
The data released this morning was the last “big” data we will see before the FOMC meets next week
Traders continue to closely monitor geopolitical developments in multiple “hot spots” (Greenland, Europe, Venezuela, Iran)
Traders will also keep a close eye on developments in the DOJ Criminal investigation into Chair Powell and the US Central Bank
A SCOTUS ruling on tariffs is now anticipated to come “at some point in January” – the decision could come any day
The “tariff” ruling could potentially create additional rate volatility as the market reacts to the Supreme Court’s decision
The US Supreme Court is also currently hearing arguments related to the legality of the Lisa Cook firing
Fed officials have entered the pre-meeting “communications blackout” until 1/29
The next FOMC rate decision is due Wednesday, January 28, 2026 at 2:00 PM
Short-end SOFR swap rates are trading up ~2-3 bps this morning, depending on tenor
Long-end SOFR swap rates are currently trading up ~1-3 bps, depending on tenor
Good Morning – US Treasury yields and SOFR swap rates are ticking slightly higher this morning, mainly due to better-than-expected economic data. The data released this morning is the last “big” data we will see prior to next week’s FOMC rate decision. Yes, the Fed is not expected to cut, but the market will be very focused on what the FOMC, and Chairman Powell have to say!
For now, however, the primary market focus will remain fixed on geopolitical developments (particularly with Greenland), and how they potentially play out. The geopolitical “news” is likely to continue to come rapidly, which will continue to make it challenging for traders to position. It also makes it challenging to forecast the path forward for interest rates. I think rates could be biased higher for the near term, or at least until the geopolitical landscape stabilizes.
News the market is tracking includes:
Geopolitical developments continue to dominate market sentiment. Geopolitical tensions escalated this week, as President Trump notched up the Greenland threats and rhetoric. President Trump’s pledge yesterday that he would not “use force” to obtain Greenland was met with some optimism, which cooled-down some of the more immediate global market concerns about an armed conflict. That said, geopolitical tensions continue to run high, and that is not likely to abate anytime soon. Markets will continue to closely monitor the situations in Venezuela, Europe, Iran and Greenland.
The Supreme Court ruling on President Trump’s tariffs has not yet been released. The ruling was postponed and is now expected to come at “some point in January”. The SCOTUS ruling could definitely have market implications. Currently, market participants and economists believe the Supreme Court will rule against the President. Economists are unsure about the market impact of the decision – either way, the ruling is a potential catalyst for elevated rate volatility. SCOTUS is also currently ruling on the legality of the President firing of the Fed’s Lisa Cook. That ruling is also expected to come in the near term.
President Trump has “asked” Fannie Mae and Freddie Mac to purchase ~$200 billion in mortgage-backed securities in order to facilitate lower mortgage rates. The market impact is uncertain at the moment, but if this does happen, it could certainly impact rates and the shape of the yield curve, at least in the short-term. We will continue to track this developing story. The President is also working to reduce credit card rates, which may also impact interest rates, consumer sentiment and the direction of the US economy.
The US Justice Department investigation into the US Central Bank and Chairman Powell is likely to remain a key market focus moving forward. Chairman Powell has been defiant and has pushed back hard on the subpoenas, saying they are “political retribution” for not lowering rates and amount to “intimidation”. He has stated he will not resign. Ultimately, we are in uncharted waters on this – at the least, it is likely to increase volatility and uncertainty while the situation plays out.
The Fed’s pre-meeting external “communications blackout” is in effect until after the FOMC meeting wraps up on January 28th. Recent Fed-speak has leaned hawkish. The Fed is not expected to lower rates next week. The next time we hear from a Fed official will be Chairman Powell’s post-meeting press conference on 1/28.
Bottom-line, there are many potential market catalysts for traders to monitor and manage at the moment.
SOFR Swap Rate Summary: The 1Y SOFR swap rate is trading up ~2-3 bps this morning. 2Y and 3Y SOFR swap rates are currently trading up ~2-3 bps. 5Y and 10Y SOFR swap rates are currently trading up ~1-3 bps. The very back-end of the swap curve is currently trading up ~1-2 bps from yesterday’s closing levels. Please note: Market levels can change rapidly – rate cap premiums are subject to a dynamic market that can change frequently.
CHART 1:US RATES SNAPSHOT: 9:30 AM Eastern
*For SOFR Swap Rates & Change-On-Day (In Bps): Refer Two Far Right Columns (SOFR Swap Rates)
UST YIELDS | SWAP SPREADS | SOFR SWAP RATES
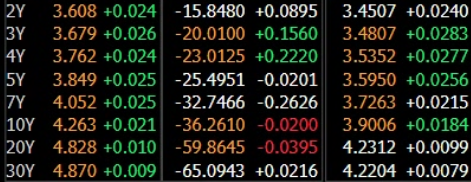
Source: Bloomberg, LLP | 9:30 AM NY Rates Snapshot
CHART 2 & 2A: SOFR SWAP RATES TICK HIGHER ON BETTER-THAN-EXPECTED ECONOMIC DATA
SOFR swap rates are ticking higher this morning, mostly due to the favorable 3Q GDP revision and lower-than-expected weekly jobless claims. The positive data is increasing the odds that the Fed will stay on the sidelines for at least the first few meetings of the year. Here are the current odds for a Fed rate cut at the next three meetings: January, 5.1%; March, 16.2%; April, 28.1%. Right now, traders do not expect a rate cut in the first quarter of 2026.
Short-term SOFR swap rates remain near the top of the recent range, and longer term rates are threatening to break out of the recent range to the upside. Expect SOFR swap rates to be biased higher until the geopolitical landscape stabilizes.
CHART 2:Short-End SOFR Swap Rates – Prior 30 Days
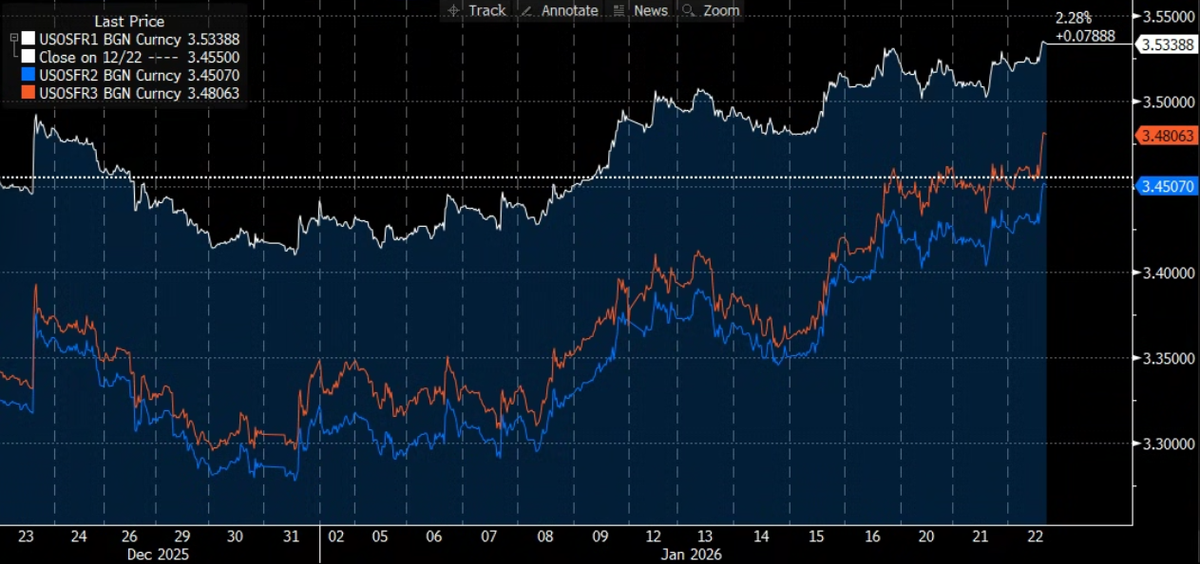
Source: Bloomberg, LLP | 1Y (white), 2Y (blue) & 3Y (orange) SOFR SWAP RATES, PRIOR 30 DAYS
CHART 2A:Long-End SOFR Swap Rates – Prior 30 Days
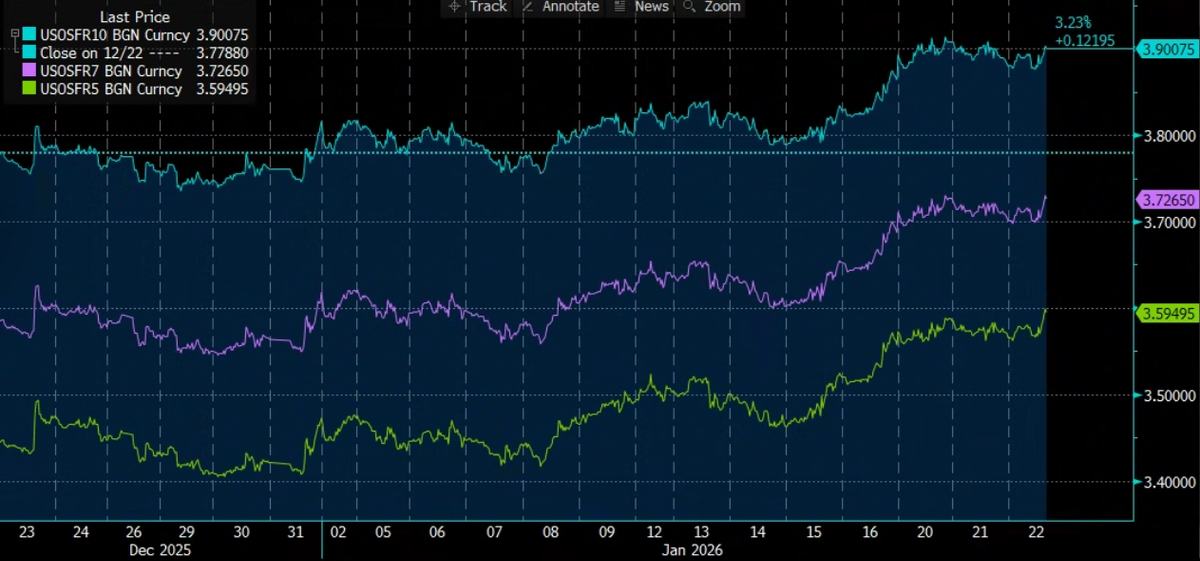
Source: Bloomberg, LLP | 5Y (green), 7Y (purple) & 10Y (light blue) SOFR SWAP RATES, PRIOR 30 DAYS
CHART 3 & 3A: ECONOMIC DATA BEATS EXPECTATIONS; MARKET LOOKS AHEAD TO FOMC MEETING
Rates opened higher this morning after better-than-expected economic data was released. Weekly jobless claims beat expectations, reflecting less layoffs than anticipated. The recent jobs data has reduced some of the fear that the labor market is rapidly cooling-off – so far, the US labor market is holding its own!
3Q GDP was revised higher, supported by stronger exports and a smaller-than-expected drag from business inventories. 3Q GDP increased at a revised 4.4% annualized rate, the fastest pace in two years. Consumer spending advanced at a 3.5% annualized pace, reflecting the fastest pace of outlays for services in three years, while spending on goods also accelerated from the previous quarter.
CHART 3:3Q GDP Recap: 3Q GDP Revised Higher
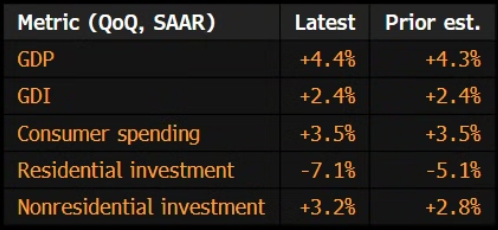
Source: Bloomberg, LLP | 3Q GDP REVISIONS RECAP
CHART 3A:Weekly Jobless Claims Beat Expectations, Remain Steady
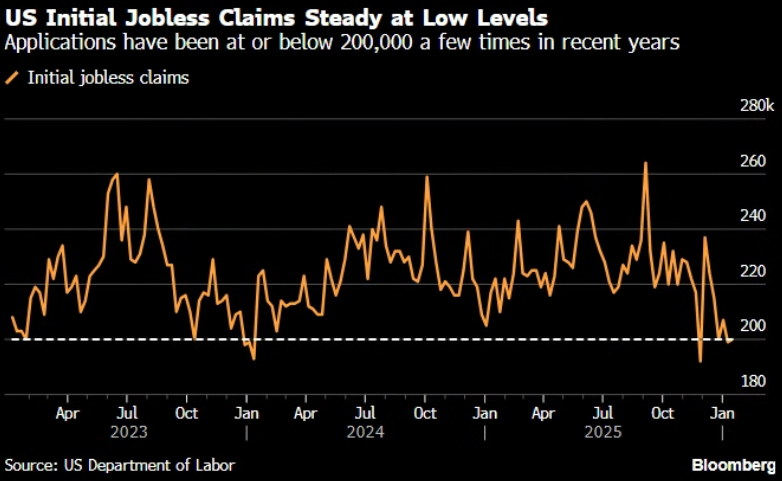
Source: Bloomberg, LLP | WEEKLY JOBLESS CLAIMS RECAP
Disclaimer: The information provided in this communication is intended for discussion purposes only. Nothing presented in this communication should be taken as a recommendation or forecast. All market data shown is indicative only and subject to change depending on current market conditions. The information in this publication is confidential and is intended for the recipient only.