

Rate Markets Update · Tuesday, January 27, 2026
Rates Mostly Steady as Market Prepares for FOMC Rate Decision & Chair Powell's Press Conference Tomorrow
Flash Update: US RATE MARKETS – TUESDAY JANUARY 27, 2026
UST yields and SOFR swap rates are holding mostly steady this morning ahead of tomorrow’s FOMC rate decision
The FOMC is widely anticipated to leave rates unchanged; All ears will be on Chair Powell’s post-meeting press conference
Traders continue to closely monitor geopolitical developments in multiple “hot spots” (Greenland, Europe, Venezuela, Iran)
A SCOTUS ruling on tariffs is now anticipated to come “at some point in January” – the decision could come any day
Fed officials remain subject to the pre-meeting “communications blackout” until 1/29
The next FOMC rate decision is due tomorrow, January 28, 2026 at 2:00 PM
Chairman Powell’s post-meeting press conference will be held tomorrow at 2:30 PM
Next up for data: December PPI is released on Friday, 1/30 at 8:30 AM
Short-end SOFR swap rates are trading flat to down ~1 bp this morning, depending on tenor
Long-end SOFR swap rates are currently trading flat to up ~1-2 bps, depending on tenor
Good Morning – US Treasury yields and SOFR swap rates are holding mostly steady this morning, as traders prepare for tomorrow’s FOMC rate decision and Chairman Powell’s post-meeting press conference. Yes, the Fed is expected to hold rates steady tomorrow, but the market will be very focused on what the FOMC, and Chairman Powell have to say. Traders are seeking forward direction from the Fed – we will see if the FOMC can provide it!
Geopolitical tensions have cooled somewhat, which has provided traders time to regroup before the Fed meeting. We don’t see any major economic data until after the FOMC meets tomorrow, so barring any new geopolitical developments, interest rates are likely to remain in a holding pattern ahead of the Fed meeting.
That said, market participants are still nervous and uncertain – the price of gold topped $5,000 earlier today, and we are still seeing a demand for a “risk premium” for long-dated US Treasuries, which has been keeping back-end rates propped up, hence the slight curve steepener we have been experiencing this week. Positive economic and inflation data has caused short term rates to drift a touch higher as traders reprice Fed rate cut expectations. Currently, forward market pricing implies 46.1 bps of cumulative rate cuts in 2026. That number was in the 50’s a couple of weeks ago.
News the market is tracking includes:
Geopolitical developments continue to dominate market sentiment. Geopolitical tensions continue to run high, and that is not likely to abate anytime soon. Markets will continue to closely monitor the situations in Venezuela, Europe, Iran and Greenland.
The Supreme Court ruling on President Trump’s tariffs has not yet been released. The ruling was postponed and is now expected to come at “some point in January”. The SCOTUS ruling could definitely have market implications. Currently, market participants and economists believe the Supreme Court will rule against the President. Economists are unsure about the market impact of the decision – either way, the ruling is a potential catalyst for elevated rate volatility. SCOTUS is also currently ruling on the legality of the President firing of the Fed’s Lisa Cook. That ruling is also expected to come in the near term.
President Trump has “asked” Fannie Mae and Freddie Mac to purchase ~$200 billion in mortgage-backed securities in order to facilitate lower mortgage rates. The market impact is uncertain at the moment, but if this does happen, it could certainly impact rates and the shape of the yield curve, at least in the short-term. We will continue to track this developing story. The President is also working to reduce credit card rates, which may also impact interest rates, consumer sentiment and the direction of the US economy.
The US Justice Department investigation into the US Central Bank and Chairman Powell is likely to remain a key market focus moving forward. Chairman Powell has been defiant and has pushed back hard on the subpoenas, saying they are “political retribution” for not lowering rates and amount to “intimidation”. He has stated he will not resign. Ultimately, we are in uncharted waters on this – at the least, it is likely to increase volatility and uncertainty while the situation plays out.
Bottom-line, there are many potential market catalysts for traders to monitor and manage at the moment.
SOFR Swap Rate Summary: The 1Y SOFR swap rate is trading flat to down ~1 bp this morning. 2Y and 3Y SOFR swap rates are currently trading flat to down ~1 bp. 5Y and 10Y SOFR swap rates are currently trading flat to up ~1 bp. The very back-end of the swap curve is currently trading up ~1-2 bps from yesterday’s closing levels. Please note: Market levels can change rapidly – rate cap premiums are subject to a dynamic market that can change frequently.
CHART 1:US RATES SNAPSHOT: 9:30 AM Eastern
*For SOFR Swap Rates & Change-On-Day (In Bps): Refer Two Far Right Columns (SOFR Swap Rates)
UST YIELDS | SWAP SPREADS | SOFR SWAP RATES
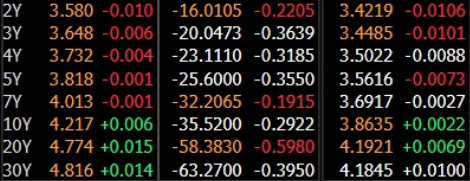
Source: Bloomberg, LLP | 9:30 AM NY Rates Snapshot
CHART 2 & 2A: SOFR SWAP RATES MOSTLY STEADY AS MARKET BRACES FOR FOMC RATE DECISION
SOFR swap rates are holding mostly steady this morning, as the market awaits tomorrow’s FOMC rate decision. The recent positive economic data has decreased the odds for a Fed rate cut during the first few meetings of the year. Here are the current odds for a Fed rate cut at the next three meetings: January, 2.8%; March, 13.8%; April, 26.3%. Right now, traders do not expect a rate cut in the first quarter of 2026.
CHART 2:Short-End SOFR Swap Rates – Prior 30 Days
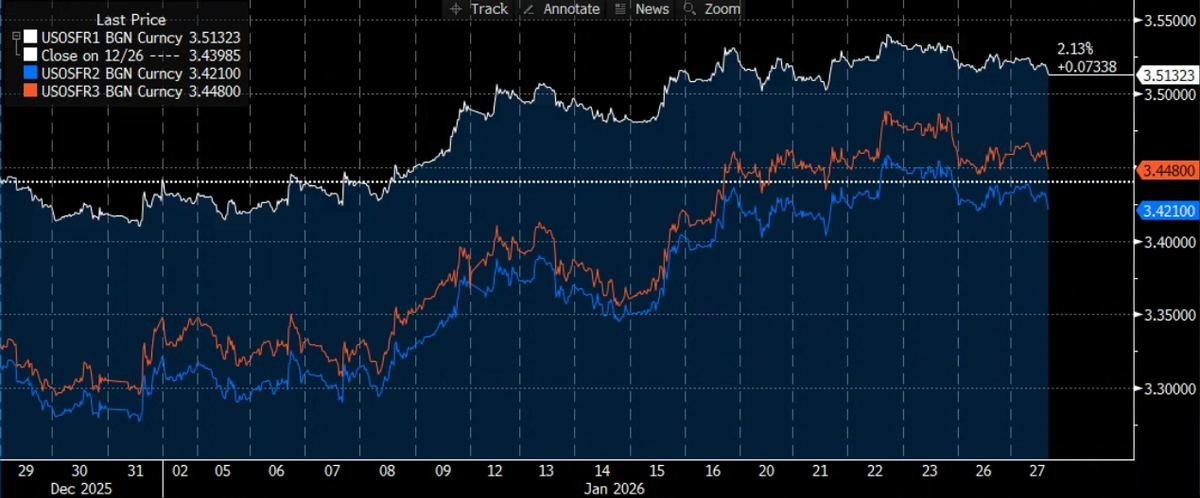
Source: Bloomberg, LLP | 1Y (white), 2Y (blue) & 3Y (orange) SOFR SWAP RATES, PRIOR 30 DAYS
CHART 2A:Long-End SOFR Swap Rates – Prior 30 Days
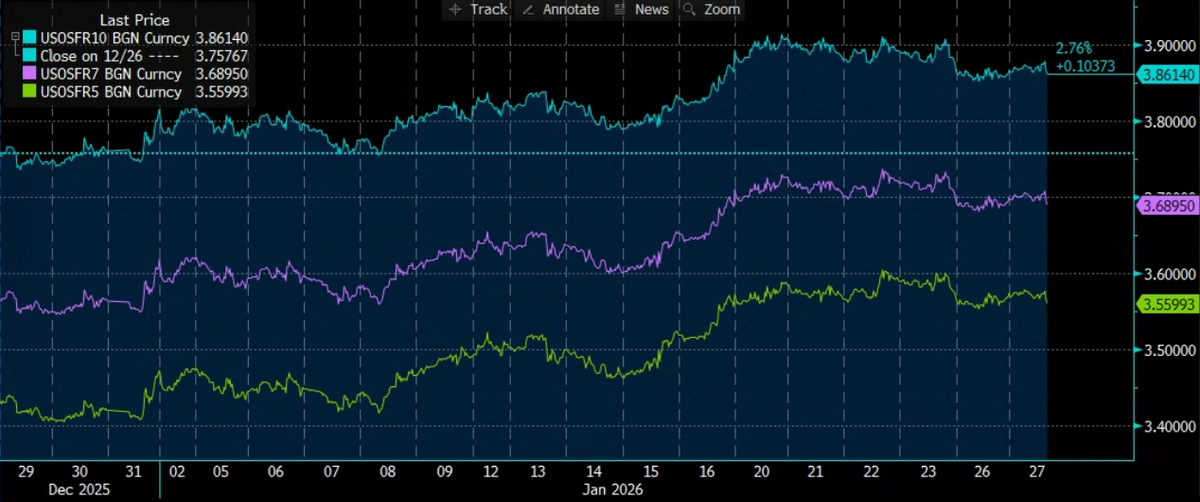
Source: Bloomberg, LLP | 5Y (green), 7Y (purple) & 10Y (light blue) SOFR SWAP RATES, PRIOR 30 DAYS
CHART 3 & 3A: FOMC PREVIEW: FED EXPECTED TO HOLD BENCHMARK RATE STEADY; FAR MORE INTEREST IN POWELL SPEECH
The FOMC is widely anticipated to hold the benchmark rate steady tomorrow. I will be most interested in what Chair Powell has to say tomorrow – that is the big event. I will also be looking at who dissents, and how the new voting members actually vote. Two of the new voting members, Hammack and Logan, are hawks, so how they vote could help set the tone for the Fed going forward. I will also be listening carefully for any mention of a “neutral rate”. One of the big questions for me is: What are FOMC members thinking regarding the “neutral rate”? If FOMC members think we are “there”, or even “close”, we may not see another rate cut for some time.
Finally, I read an interesting observation today: Pay particular attention for the phrase “in considering the extent and timing” of future rate moves – in the past, when the Fed has included that phrase in the official statement, it has preceded extended FOMC “pauses”. Regarding the DOJ criminal probe, I fully expect Chair Powell to address questions about Fed independence and White House meddling head on. Fasten your seatbelts!
CHART 3:Fed Hawks Have Upper Hand At The Moment…
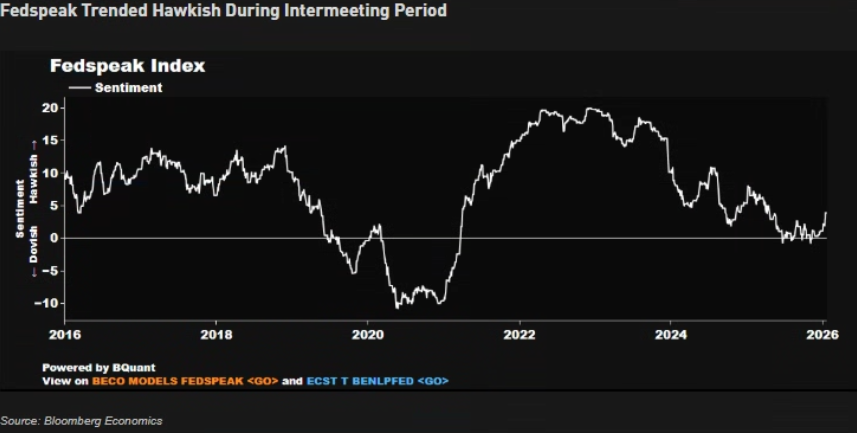
Source: Bloomberg, LLP | BLOOMBERG FED-SPEAK INDEX SINCE 2016
CHART 3A:Recent Economic Data Makes It Tough To Argue For A Rate Cut
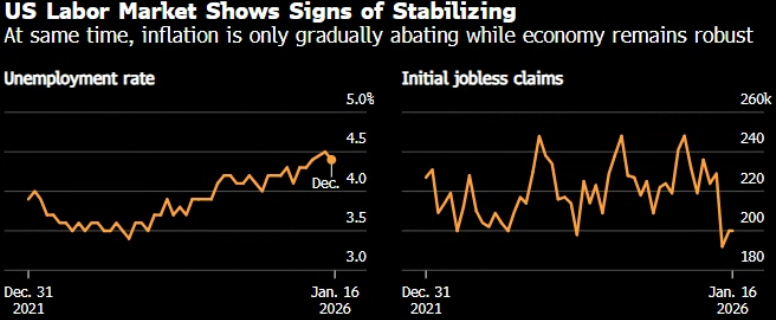
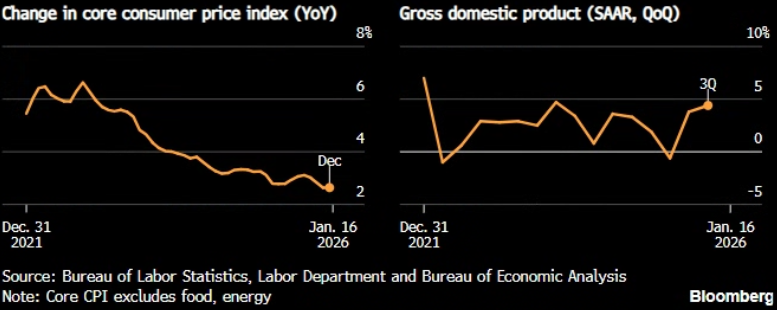
Source: Bloomberg, LLP | HISTORICAL MAJOR ECONOMIC DATA SINCE DECEMBER 2021
Disclaimer: The information provided in this communication is intended for discussion purposes only. Nothing presented in this communication should be taken as a recommendation or forecast. All market data shown is indicative only and subject to change depending on current market conditions. The information in this publication is confidential and is intended for the recipient only.