

Rate Markets Update · Thursday, January 29, 2026
FOMC Holds as Anticpated
- Powell Has No Comment on Doj Investigation
- Rates Mostly Steady as Market Regroups
Flash Update: US RATE MARKETS – THURSDAY JANUARY 29, 2026
UST yields and SOFR swap rates are holding mostly steady this morning as traders digest yesterday’s Fed news
The Fed held the overnight rate steady and signaled they will proceed on a meeting by meeting basis
Traders continue to closely monitor geopolitical developments in multiple “hot spots” (Greenland, Europe, Venezuela, Iran)
The deteriorating situation in Iran, coupled with US threats, are capturing the market’s attention this morning
A potential government shutdown is also garnering market attention – another disruption to “data releases” could impact rates
A SCOTUS ruling on tariffs is now anticipated to come “at some point in January” – the decision could come any day
Fed officials will emerge from the “communications blackout” tomorrow, 1/30
The next FOMC rate decision is due Wednesday, March 18, 2026 at 2:00 PM
Next up for data: December PPI is released tomorrow, 1/30 at 8:30 AM
Short-end SOFR swap rates are trading flat to down ~1 bp this morning, depending on tenor
Long-end SOFR swap rates are currently trading up ~1-3 bps, depending on tenor
Good Morning – US Treasury yields and SOFR swap rates are holding mostly steady this morning, as traders digest yesterday’s Fed announcement and Chairman Powell’s comments. The Fed held the overnight rate steady, and signaled they will be in a “wait and see mode” going forward. Chair Powell stressed there is no “pre-set course” for monetary policy – they will be making monetary policy decisions on a meeting by meeting basis and will remain data dependent. Overall, the market had a muted reaction to all the Fed news yesterday – rates remain range bound. The market is still seeking direction, or perhaps, we are currently at the “right” levels given all of the ongoing turmoil and uncertainty.
Traders will likely shift focus to several other “hot spots” that could impact US rates including a potential US government shutdown, a deteriorating political situation in Iran and the next series of key economic data. We will see December PPI released tomorrow at 8:30 AM. Expectations are as follows: Headline MoM, 0.2% (vs. 0.2% the prior month); Core MoM, 0.2% (vs. 0.0% prior); Headline YoY, 2.8% (vs. 3.0% prior); Core YoY, 2.9% (vs. 3.0% prior).
News the market is tracking includes:
Geopolitical developments continue to weigh on market sentiment. Geopolitical tensions continue to run high, and that is not likely to abate anytime soon. Markets will continue to closely monitor the situations in Venezuela, Europe, Iran and Greenland. Geopolitical tensions escalated yesterday as the US stepped up its threats against the Iranian regime. That development once again has global markets nervous and uncertain.
Markets will be tracking developments in the equities markets closely. There is still a sharp focus on the performance of the growing AI sector. Market sentiment is likely to be impacted by “tech” earnings for the foreseeable future.
The Supreme Court ruling on President Trump’s tariffs has not yet been released. The ruling is now expected to come at “some point in January”. The SCOTUS ruling could definitely have market implications. Currently, market participants and economists believe the Supreme Court will rule against the President. Economists are unsure about the market impact of the decision – either way, the ruling is a potential catalyst for elevated rate volatility.
SCOTUS is also currently ruling on the legality of the President firing of the Fed’s Lisa Cook. That ruling is also expected to come in the near term. Chair Powell said yesterday that this is “the most important legal case in the Fed’s history”. Stay tuned!
President Trump has “asked” Fannie Mae and Freddie Mac to purchase ~$200 billion in mortgage-backed securities in order to facilitate lower mortgage rates. The market impact is uncertain at the moment. A sudden surge in purchases could impact rates and the shape of the yield curve, at least in the short-term. We will continue to track this developing story.
The US Justice Department investigation into the US Central Bank and Chairman Powell is likely to remain a key market focus moving forward.
Traders will continue to track developments with the US dollar – the recent weakness, and reaction of the US government, has baffled markets. Sustained currency weakness can be inflationary. A weak dollar can lead to “pricier” imports and a deterioration in investor confidence.
Bottom-line, there are many potential market catalysts for traders to monitor and manage at the moment.
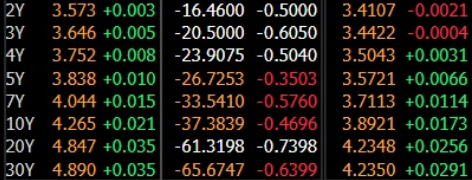
SOFR Swap Rate Summary: The 1Y SOFR swap rate is trading flat to down ~1 bp this morning. 2Y and 3Y SOFR swap rates are currently trading flat to down ~1 bp. 5Y and 10Y SOFR swap rates are currently trading up ~1-2 bps. The very back-end of the swap curve is currently trading up ~1-3 bps from yesterday’s closing levels. The yield curve steepened slightly this morning, driven by the back-end of the curve.
Please note: Market levels can change rapidly – rate cap premiums are subject to a dynamic market that can change frequently.
CHART 1:US RATES SNAPSHOT: 9:30 AM Eastern
*For SOFR Swap Rates & Change-On-Day (In Bps): Refer Two Far Right Columns (SOFR Swap Rates)
UST YIELDS | SWAP SPREADS | SOFR SWAP RATES
Source: Bloomberg, LLP | 9:30 AM NY Rates Snapshot
CHART 2, 2A & 2B: SOFR SWAP RATES STEADY AS MARKET DIGESTS POWELL COMMENTS; PATH FORWARD UNCERTAIN
SOFR swap rates are holding mostly steady this morning, as the market digests the results of the FOMC meeting and parses Chairman Powell’s post-meeting comments. Markets had an overall muted reaction to the FOMC official statement and Chair Powell’s comments, and I am not sure the market got the direction it was seeking.
Forces likely to impact swap rates in the near term include the worsening situation in Iran and the impact on oil prices, a potential US government shutdown and upcoming US economic data. We will see December PPI released tomorrow at 8:30 AM. Other key economic data on the horizon includes: January ISM Manufacturing data on 2/02; December JOLTS jobs report on 2/03; January ISM Services data on 2/4; January CPI on 2/11; January Employment Report on 2/6.
Here are the current odds for a Fed rate cut at the next four meetings: March, 13.5%; April, 26.1%; June, 61.5%; July 73.8%. Right now, traders do not expect a rate cut in the first quarter of 2026, but they do suspect that the installment of a new Fed chief could green-light a rate cut in June. Currently, forward market pricing implies 47.4 bps of cumulative rate cuts in 2026 (~two, 25 bp rate cuts).
CHART 2:Short-End SOFR Swap Rates – Prior 30 Days
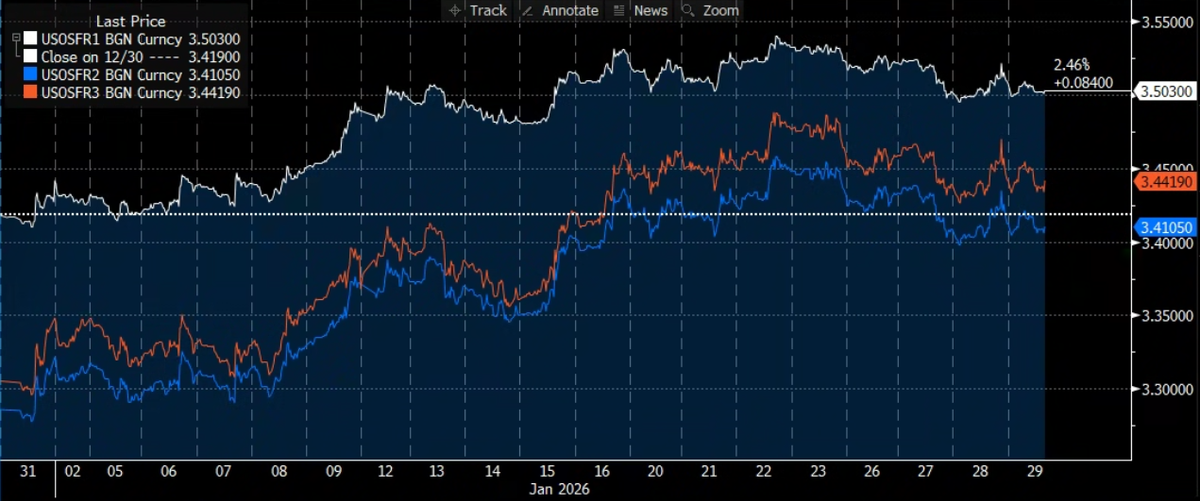
Source: Bloomberg, LLP | 1Y (white), 2Y (blue) & 3Y (orange) SOFR SWAP RATES, PRIOR 30 DAYS
CHART 2A:Long-End SOFR Swap Rates – Prior 30 Days
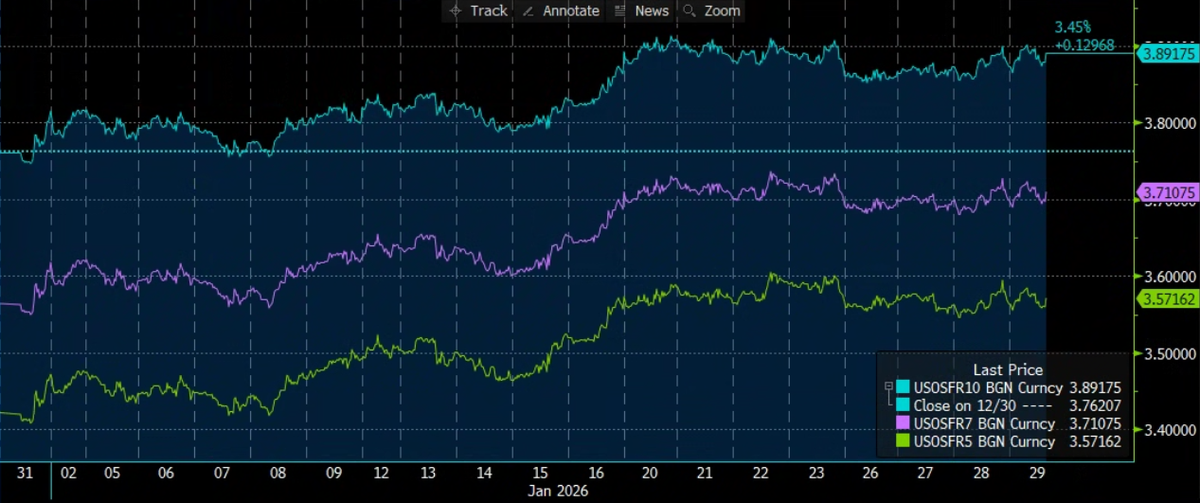
Source: Bloomberg, LLP | 5Y (green), 7Y (purple) & 10Y (light blue) SOFR SWAP RATES, PRIOR 30 DAYS
CHART 2B:Market Tracking Crude Oil Prices As Iran Situation Deteriorates
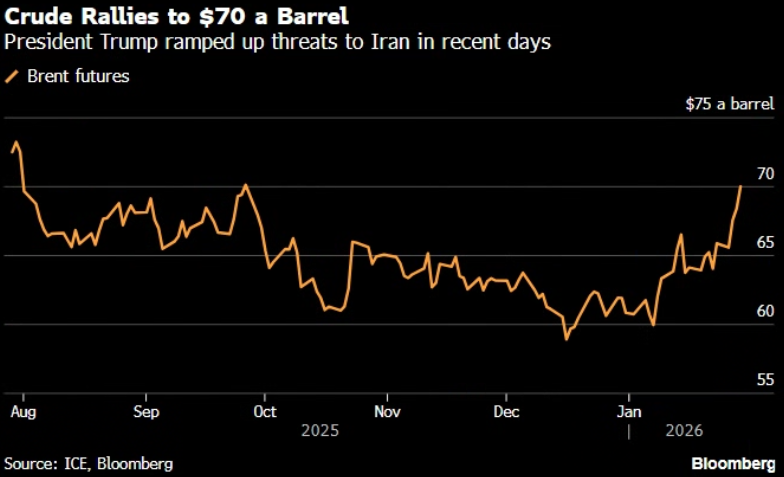
Source: Bloomberg, LLP | BRENT CRUDE OIL FUTURES PRICING SINCE AUGUST 2025
CHART 3, 3A & 3B: FOMC HOLDS AS EXPECTED; SIGNALS WILL PROCEED ON A “MEETING BY MEETING” BASIS
Yesterday, the FOMC held the benchmark rate steady, as anticipated. The Fed Funds target range remains 3.50% - 3.75%. There were two dissenting votes from Waller and Miran, in favor of a rate cut. The FOMC toned down the official statement – they removed language saying downside risks to employment have risen and they added that the Unemployment Rate has shown signs of stabilization. The FOMC did flag inflation, saying it “remains somewhat elevated”, but overall they presented a fairly upbeat assessment of the broader US economy. They did use the phrase, “in considering the timing an extent of future rate moves”, which typically precedes an extended Fed pause.
Chairman Powell had a lot to say yesterday, but to my huge surprise, he steadfastly avoided commenting on the DOJ probe, political pressure, the Lisa Cook SCOTUS hearing or on his future plans. Basically he avoided comments on anything not related to monetary policy or the US economy. He said, “I’ve got nothing for you on that” multiple times during the Q&A. He is simply not going to comment on political or legal matters.
Highlights of Chair Powell’s comments include:
-Economic growth is solid and on “firm footing for 2026”
-“Inflation remains elevated”, but short-term forecasts are favorable
-Jobs market showing signs of stabilization and remains “broadly stable”
-Consumer Spending remains “resilient”
-Tariffs appear to be a “one-time” pass-through
-Fed is “well positioned to determine our next move on rates”
-He championed and stressed the need to maintain Fed independence and he urged his successor to be accountable to Congress
-Monetary policy decisions to be made on a “meeting by meeting basis”, data dependent
Based on Chair Powell’s comments yesterday, recent data and consensus forecasts, we may have seen the last of the rate cuts during Powell’s Chairmanship. More importantly, that likely means the Fed’s impact on rates may be muted for at least the first quarter of 2026. Right now, markets do not expect the Fed to do much of anything for at least the next few meetings, maybe longer. Markets may therefore look to other areas of the broader market for rate catalysts. Those may include fiscal policy changes, geopolitical developments, market forces (i.e. supply & demand, liquidity, risk premiums, etc.) and “FX” markets. The puzzling recent US dollar weakness could definitely impact rates and if it is sustained, could be inflationary. Economic data will also be a key focus for traders as we fully emerge from the government shutdown data void.
Admittedly, the Fed is likely to remain in the spotlight given the DOJ investigation, Lisa Cook SCOTUS hearing and a new Chairman on the horizon. In fact, the spotlight may only shine brighter on the Fed over the next several months. However, the Fed’s monetary policy decisions are not likely to have a major impact on rates for the near term. At one point during the press conference, Chair Powell conceded we may be at the “higher-end of the plausible range for neutral” – that tells me that, as it stands right now, we may – may have one more rate cut to look forward to this year.
Big picture, I think the Fed will remain on the sidelines for the foreseeable future – perhaps the next several meetings.
CHART 3:Fed Rate Cut Bets Dialed Back As Fed Signals “Meeting By Meeting” Bias; Powell Says Fed “Well Positioned”
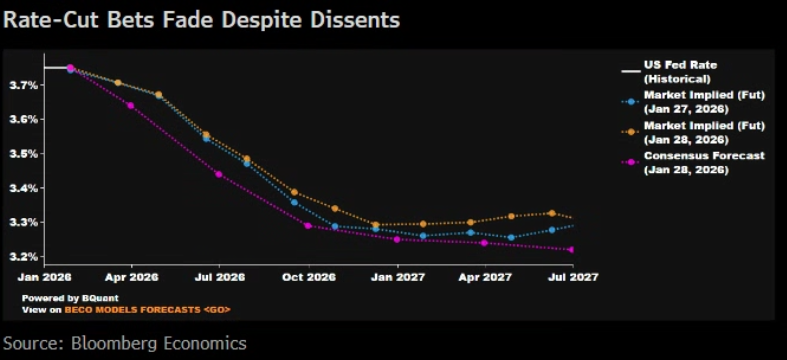
Source: Bloomberg, LLP | FED RATE CUT EXPECTATIONS THROUGH JULY 2027
CHART 3A:Market Ponders Who Will Be The Next Fed Chairman…President Trump’s Decision Is Expected Soon
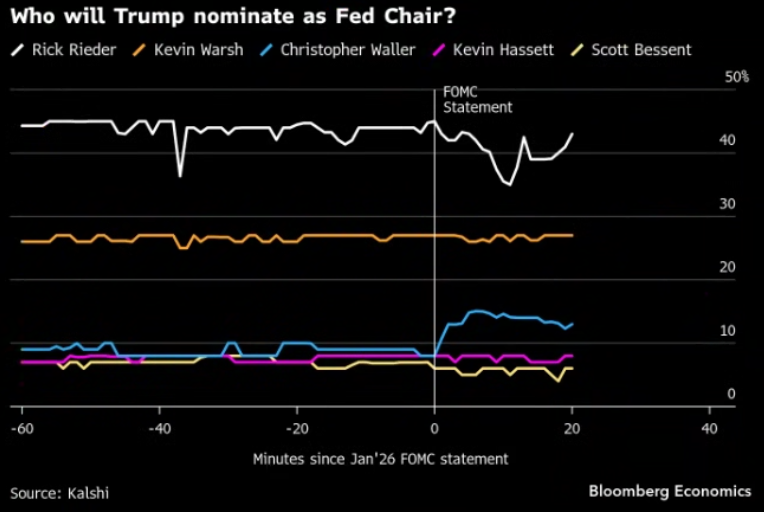
Source: Bloomberg, LLP | FOMC CHAIRMAN “ODDS” INDEX
CHART 3B:Current Forward Implied Fed Funds & 1-Month Term SOFR Rates
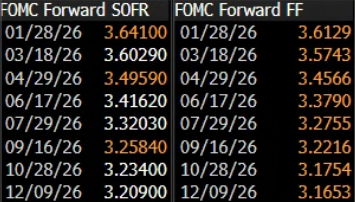
Source: Bloomberg, LLP | CURRENT FWD IMPLIED FED FUNDS & 1M TERM SOFR RATES
Disclaimer: The information provided in this communication is intended for discussion purposes only. Nothing presented in this communication should be taken as a recommendation or forecast. All market data shown is indicative only and subject to change depending on current market conditions. The information in this publication is confidential and is intended for the recipient only.