

Rate Markets Update · Thursday, January 8, 2026
Rates Drift Higher on Better-Than-Expected Economic Data
- Traders Await December Employment Report
Flash Update: US RATE MARKETS – THURSDAY JANUARY 8, 2026
UST yields and SOFR swap rates are drifting higher this morning on better-than-expected economic data
Yesterday’s JOLTS jobs report beat expectations; Job openings rose, layoffs declined
Data released this morning showed US labor productivity accelerated to the strongest pace in two years
Overall, SOFR swap rates remain range bound as the market awaits a fresh run of economic data
Traders are also closely monitoring geopolitical developments in several “hot spots”
Next up for data: December Employment Report is due tomorrow, 1/9 at 8:30 AM
The next FOMC rate decision is due Wednesday, January 28, 2026 at 2:00 PM
Short-end SOFR swap rates are trading up ~1-2 bps this morning, depending on tenor
Long-end SOFR swap rates are currently trading up ~2-3 bps, depending on tenor
Good Morning – US Treasury yields and SOFR swap rates are drifting higher this morning after better-than-expected jobs and labor productivity data was released. Data showed that layoffs moved to a 17-month low, and US labor productivity accelerated to the strongest pace in two years. Job openings data results also beat expectations. The positive jobs and productivity data led to higher rates this morning. That said, traders are clearly reluctant to make any dramatic moves ahead of tomorrow’s release of the December Employment Report. I thought rates would move a bit more based on the data the past two days, but clearly market participants want to see tomorrow’s labor data before potentially carving out a new trading range.
The first big data event of the year will be the release of the December Employment Report tomorrow, 1/9 at 8:30 AM. All eyes will be on that report, as it will likely set the tone for monetary policy expectations. December Employment Report expectations are as follows: Change in Non-Farm Payrolls, +70k expected (vs. +64k prior); Change in Private Payrolls, +75k (vs. +69k prior); Unemployment Rate, 4.5% (vs. 4.6% prior); Average Hourly Earnings, 0.3% (vs 0.1% prior). Weaker-than-expected employment data would likely lead to lower rates. Better-than-expected data would reduce the odds for a Fed rate cut anytime soon, and rates would likely move higher.
The primary concerns facing the market in early 2026 are geopolitical, the upcoming FOMC “facelift” (new voting members, new Chairman as of June 2026) and questions surrounding inflation and the outlook for Fed rate cuts (more cuts? steeper yield curve?). There are many market participants who fear a curve steepener will occur in Q1 2026 due to strong economic growth and sticky inflation.
SOFR Swap Rate Summary: The 1Y SOFR swap rate is trading up ~1-2 bps this morning. 2Y and 3Y SOFR swap rates are currently trading up ~1-2 bps. 5Y and 10Y SOFR swap rates are currently trading up ~2-3 bps. The very back-end of the swap curve is currently trading up ~2-3 bps from yesterday’s closing levels. Please note: Market levels can change rapidly – rate cap premiums are subject to a dynamic market that can change frequently.
CHART 1:US RATES SNAPSHOT: 10:15 AM Eastern
*For SOFR Swap Rates & Change-On-Day (In Bps): Refer Two Far Right Columns (SOFR Swap Rates)
UST YIELDS | SWAP SPREADS | SOFR SWAP RATES
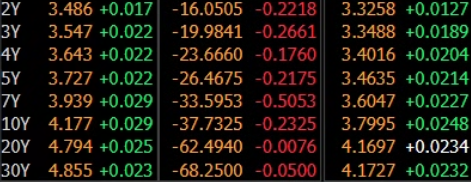
Source: Bloomberg, LLP | 10:15 AM NY Rates Snapshot
CHART 2 & 2A: SOFR SWAP RATES DRIFT HIGHER ON BETTER-THAN-EXPECTED ECONOMIC DATA
SOFR swap rates are a touch higher this morning, due to stronger-than-expected jobs and productivity data. Traders continue to assess the current risk landscape and the path forward for interest rates. Traders are also waiting for the release of the December Employment Report, due tomorrow. Overall, swap rates remain range bound as the market seeks direction. Swap rates across the curve have been trading in an ~10-15 bp trading range since early December.
The first “big” number we see this year is the December Employment Report, which is due for release tomorrow, January 9 at 8:30 AM. The next FOMC rate decision is due Wednesday, January 28 at 2:00 PM. At the moment, odds for a 25 bp rate cut have dropped to ~11.6%. Currently, market participants do not expect a rate cut at the January FOMC meeting.
CHART 2:Short-End SOFR Swap Rates – Prior 30 Days
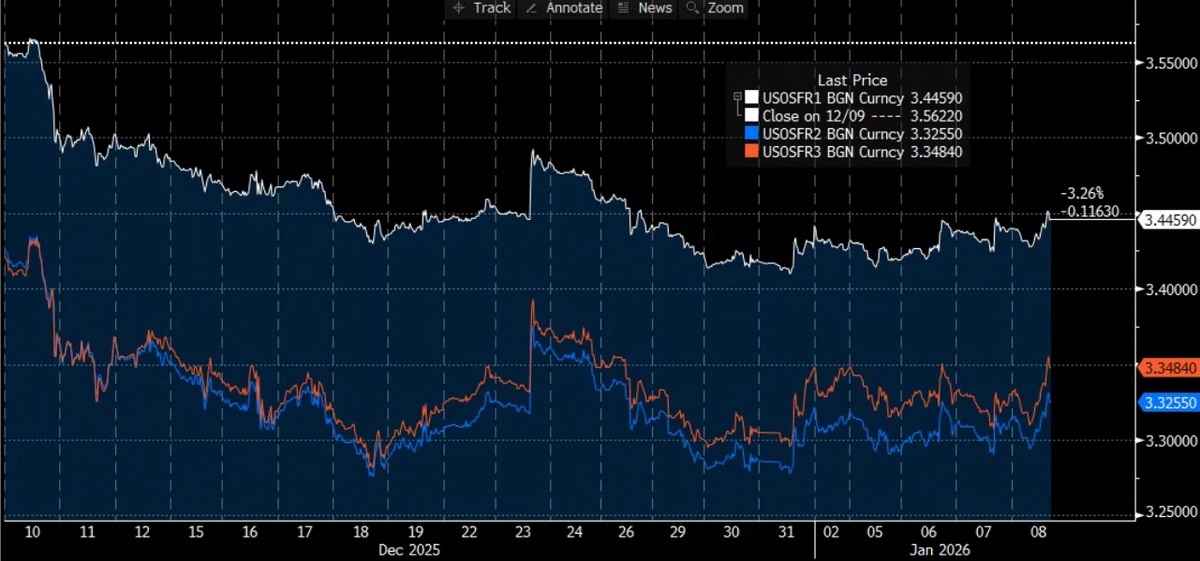
Source: Bloomberg, LLP | 1Y (white), 2Y (blue) & 3Y (orange) SOFR SWAP RATES, PRIOR 30 DAYS
CHART 2A:Long-End SOFR Swap Rates – Prior 30 Days
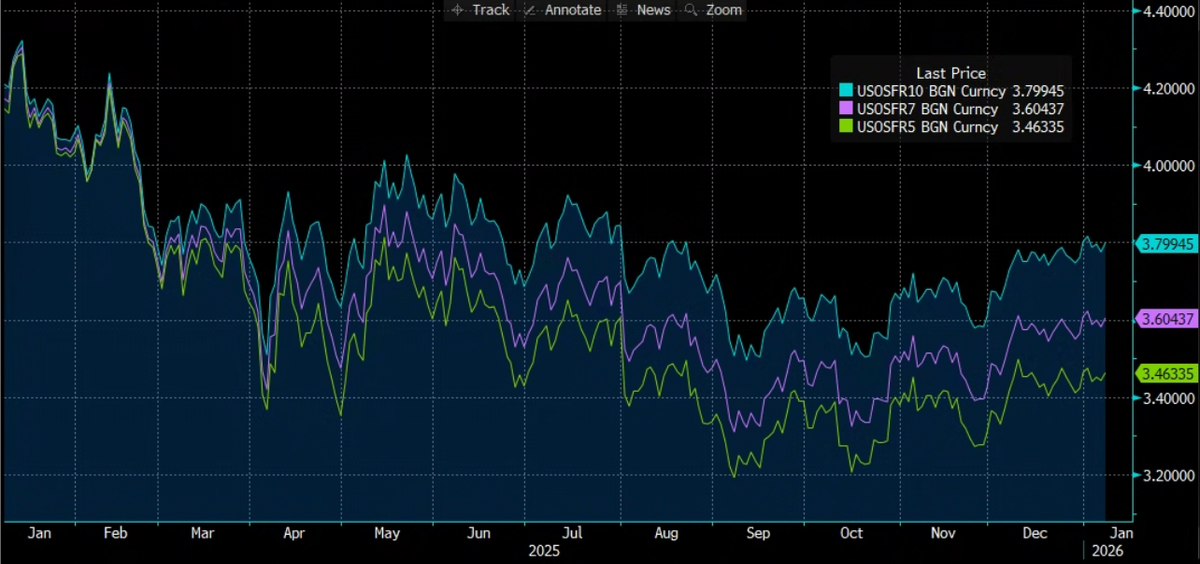
Source: Bloomberg, LLP | 5Y (green), 7Y (purple) & 10Y (light blue) SOFR SWAP RATES, PRIOR 30 DAYS
Disclaimer: The information provided in this communication is intended for discussion purposes only. Nothing presented in this communication should be taken as a recommendation or forecast. All market data shown is indicative only and subject to change depending on current market conditions. The information in this publication is confidential and is intended for the recipient only.