

Rate Markets Update · Friday, January 9, 2026
Employment Report Mixed, Unemployment Rate Drops to 4.4%
- Rates Steady After Jobs Report
- Market Awaits Tariff Ruling Due Today
Flash Update: US RATE MARKETS – FRIDAY JANUARY 9, 2026
UST yields and SOFR swap rates are a few ticks higher this morning but overall, traders shrugged-off the jobs data
The December Employment Report results were mixed; Additions to non-farm payrolls missed expectations but the Unemployment Rate slid to 4.4%
Overall, the December jobs data takes some of the potency out of the view that the labor market is significantly weakening
The December Employment Report results did little to alter Fed rate cut expectations for 2026
The Supreme Court will rule today on whether President Trump’s tariffs are legal or not
The tariff ruling could potentially create additional rate volatility as the market digests the Supreme Court’s decision
Traders continue to closely monitor geopolitical developments in several “hot spots”
We are tracking developments with Fannie Mae and Freddie Mac, which could have ramifications for the rates market
Next up for data: December CPI data prints on Tuesday, 1/13 at 8:30 AM
The next FOMC rate decision is due Wednesday, January 28, 2026 at 2:00 PM
Short-end SOFR swap rates are trading up ~1-2 bps this morning, depending on tenor
Long-end SOFR swap rates are currently trading up ~1-2 bps, depending on tenor
Good Morning – US Treasury yields and SOFR swap rates increased slightly this morning, as traders digested the December Employment Report results. The December jobs data was mixed – additions to non-farm and private payrolls were weaker-than-expected, but the Unemployment Rate dropped to 4.4%, below expectations calling for 4.5%. Overall, traders shrugged-off the mixed data, which is keeping rates relatively steady for the time being. I do think the mixed data does take some of the potency out of the argument that the US labor market is facing significant weakness. That does not seem to be the case. The data did little to change Fed rate cut expectations for 2026. Forward market pricing implies 54.7 bps of cumulative rate cuts for 2026 (~two, 25 bp rate cuts). Currently, the odds for a rate cut at the January Fed meeting are sitting at a paltry 2.6%.
Other news the market is tracking:
Geopolitical developments. Geopolitical tensions are running high, and that is not likely to abate anytime soon. Markets are paying particular attention to the situation in Venezuela. So far, the market’s reaction has been relatively muted.
The Supreme Court is due to rule today on the legality of President Trump’s tariffs. The ruling could definitely have market implications. Currently, the market believes the Supreme Court will rule against the President. Economists are unsure about the market impact of the decision – either way, the ruling could potentially be a catalyst for elevated rate volatility.
President Trump has “asked” Fannie Mae and Freddie Mac to purchase ~$200 billion in mortgage-backed securities in order to facilitate lower mortgage rates. The market impact is uncertain at the moment, but if this does happen, it could certainly impact rates and the shape of the yield curve, at least in the short-term.
Next up for economic data will be the release of December CPI on Tuesday, 1/13 at 8:30 AM. With inflation still in focus, traders will be keen to see current inflation data.
SOFR Swap Rate Summary: The 1Y SOFR swap rate is trading up ~1-2 bps this morning. 2Y and 3Y SOFR swap rates are currently trading up ~1-2 bps. 5Y and 10Y SOFR swap rates are currently trading up ~1-2 bps. The very back-end of the swap curve is currently trading up ~1-2 bps from yesterday’s closing levels. Please note: Market levels can change rapidly – rate cap premiums are subject to a dynamic market that can change frequently.
CHART 1:US RATES SNAPSHOT: 9:30 AM Eastern
*For SOFR Swap Rates & Change-On-Day (In Bps): Refer Two Far Right Columns (SOFR Swap Rates)
UST YIELDS | SWAP SPREADS | SOFR SWAP RATES
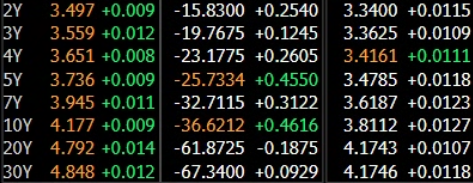
Source: Bloomberg, LLP | 9:30 AM NY Rates Snapshot
CHART 2 & 2A: SOFR SWAP RATES DRIFT SLIGHTLY HIGHER AS MARKET SHRUGS-OFF EMPLOYMENT DATA
SOFR swap rates are a touch higher this morning, as traders digest a mixed jobs report. Traders continue to assess the current risk landscape and the path forward for interest rates. Market participants will continue to monitor the potential market catalysts mentioned above. Traders will now look ahead to the December CPI report due on 1/13. Despite the hype surrounding the Employment Report, the reaction this morning was relatively muted. Overall, swap rates remain range bound as the market seeks direction. Swap rates across the curve continue to trade in a ~10-15 bp trading range.
CHART 2:Short-End SOFR Swap Rates – Prior 10 Days
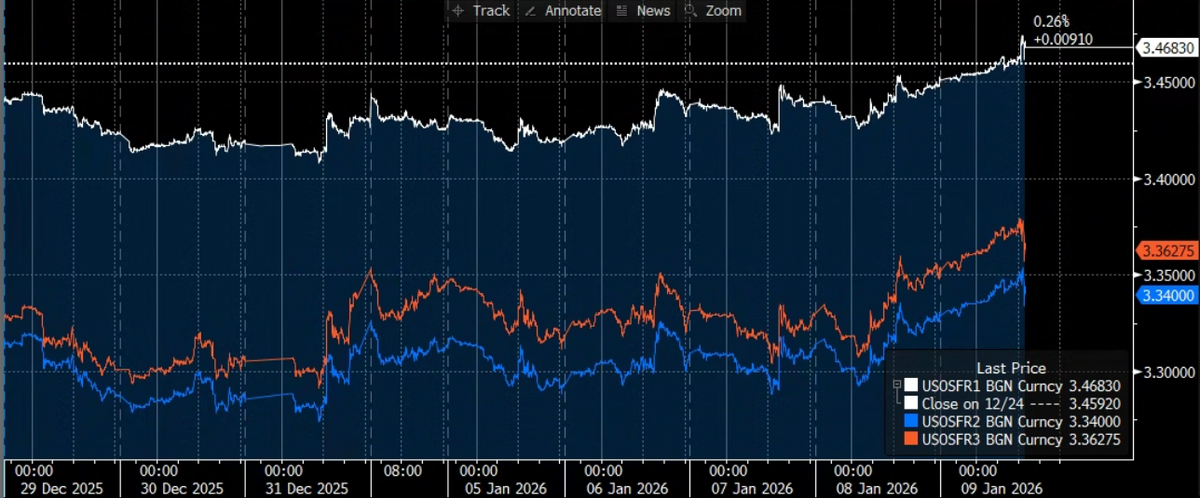
Source: Bloomberg, LLP | 1Y (white), 2Y (blue) & 3Y (orange) SOFR SWAP RATES, PRIOR 10 DAYS
CHART 2A:Long-End SOFR Swap Rates – Prior 10 Days
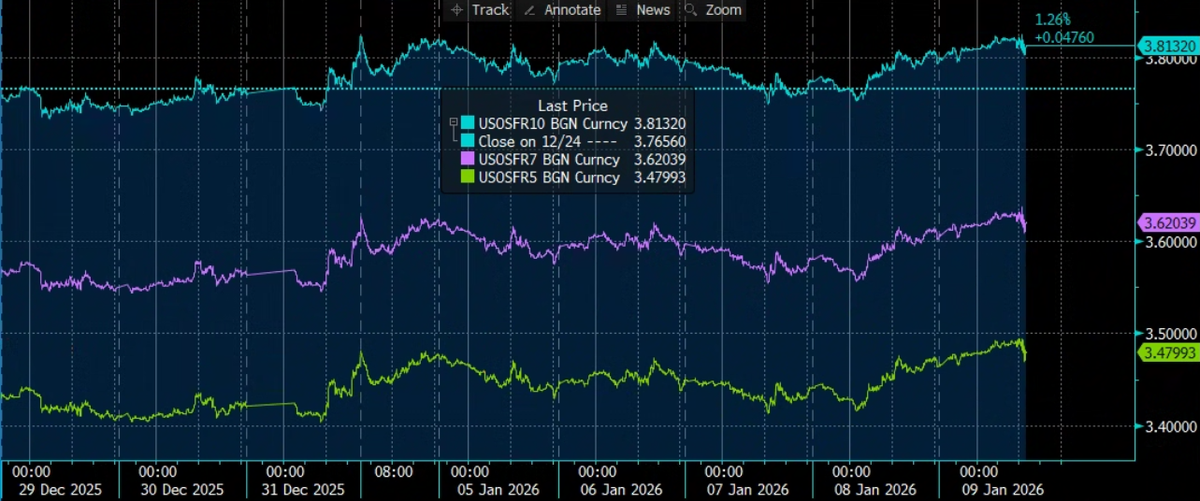
Source: Bloomberg, LLP | 5Y (green), 7Y (purple) & 10Y (light blue) SOFR SWAP RATES, PRIOR 10 DAYS
CHART 3: DECEMBER EMPLOYMENT REPORT RECAP – DECEMBER EMPLOYMENT DATA MIXED
The December Employment Report was not the catalyst market participants anticipated. The December jobs results were mixed – additions to non-farm and private payrolls missed expectations, but the critical Unemployment Rate dropped to 4.4%. One the one hand, US employers added fewer jobs than expected in December, suggesting the labor market continued to soften at year-end. One the other hand, nonfarm payrolls increased 50,000 last month and the unemployment rate edged down to 4.4%, which to me, does not suggest an imminent collapse of the labor market. I do think the US labor market remains fragile, which should hold rates steady while the market awaits additional economic data.
CHART 3:December Employment Report Recap
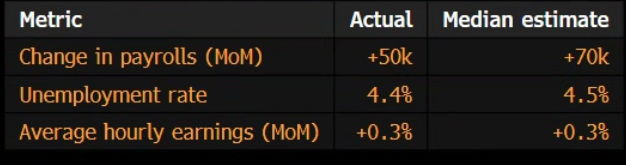
Source: Bloomberg, LLP | DECEMBER EMPLOYMENT REPORT RECAP
Disclaimer: The information provided in this communication is intended for discussion purposes only. Nothing presented in this communication should be taken as a recommendation or forecast. All market data shown is indicative only and subject to change depending on current market conditions. The information in this publication is confidential and is intended for the recipient only.