

Rate Markets Update · Friday, February 13, 2026
Rates Drift Lower on Better-Than-Expected CPI Data
- More Key Data on the Horizon
Flash Update: US RATE MARKETS – FRIDAY FEBRUARY 13, 2026
UST yields and SOFR swap rates dipped slightly lower this morning on better-than-expected January CPI data
Overall, January CPI beat expectations, signaling consumer inflation remains mostly in check
However, MoM core CPI jumped 0.3% in January, as expected, but the highest increase since August
Traders continue to monitor geopolitical developments, though tensions have eased a bit recently
Market participants will continue to monitor developments with the DOJ investigation into the US Central Bank
A SCOTUS ruling on tariffs is now anticipated to come in February – the decision could come any day
The next FOMC rate decision is due Wednesday, March 18, 2026 at 2:00 PM
The January FOMC meeting minutes will be released on Wednesday, 2/18 at 2:00 PM
Next up for data: Q4 GDP and December PCE inflation data are released on Friday 2/20 at 8:30 AM
Short-end SOFR swap rates are trading down ~3-4 bps this morning, depending on tenor
Long-end SOFR swap rates are currently down ~2-3 bps, depending on tenor
Good Morning – US Treasury yields and SOFR swap rates moved a bit lower this morning after a better-than-expected January CPI report showed consumer inflation remains in check. Rates initially moved ~5-6 bps lower after the CPI data was released, but retraced higher after traders parsed the CPI report details. Currently, rates are ~2-4 bps lower across the curve.
Market participants will continue to track a number of potential market catalysts, but I think the primary focus for traders right now is seeing current economic and inflation data. That will continue into next week, when we will see the release of the January FOMC meeting minutes and key economic data. The January Fed meeting minutes will be released on Wednesday, 2/18 at 8:30 AM. We will also see the release of Q4 GDP and December PCE inflation data on Friday 2/20, at 8:30 AM.
News the market is tracking includes:
Geopolitical developments continue to weigh on market sentiment. The current lull in geopolitical tensions has forced traders into a “wait and see mode”. Tensions have abated somewhat in recent days, but remain simmering just below the surface.
Market participants will be tracking developments in the US equities markets closely. There is still a sharp focus on the performance of the growing AI sector. Market sentiment is likely to be impacted by “tech” earnings for the foreseeable future.
The Supreme Court ruling on President Trump’s tariffs has not yet been released. The ruling is now expected to come this month. The SCOTUS ruling could definitely have market implications. Economists are unsure about the market impact of the decision – either way, the ruling is a potential catalyst for elevated rate volatility.
SCOTUS is also currently ruling on the legality of the President firing of the Fed’s Lisa Cook. That ruling is also expected to come in the near term. Chair Powell said yesterday that this is “the most important legal case in the Fed’s history”. Stay tuned!
The US Justice Department investigation into the US Central Bank and Chairman Powell is likely to remain a key market focus moving forward.
Traders will continue to track developments with the US dollar – the recent weakness, and reaction of the US government, has baffled markets. Sustained currency weakness can be inflationary. A weak dollar can lead to “pricier” imports and a deterioration in investor confidence.
Market participants are once again tracking US political developments, specifically with respect to budget negotiations. Traders are watching for signs of another potential government shutdown. As we have witnessed recently, government shutdowns can impact the timely release of economic data, which makes it difficult for traders to position.
Bottom-line, there are many potential market catalysts for traders to monitor and manage at the moment.
SOFR Swap Rate Summary: The 1Y SOFR swap rate is trading down ~2-4 bps this morning. 2Y and 3Y SOFR swap rates are currently trading down ~2-4 bps. 5Y and 10Y SOFR swap rates are currently trading down ~2-3 bps on the day. The very back-end of the swap curve is currently trading down ~2-3 bps from yesterday’s closing levels.
Please note: Market levels can change rapidly – rate cap premiums are subject to a dynamic market that can change frequently.
CHART 1:US RATES SNAPSHOT: 9:30 AM Eastern
*For SOFR Swap Rates & Change-On-Day (In Bps): Refer Two Far Right Columns (SOFR Swap Rates)
UST YIELDS | SWAP SPREADS | SOFR SWAP RATES
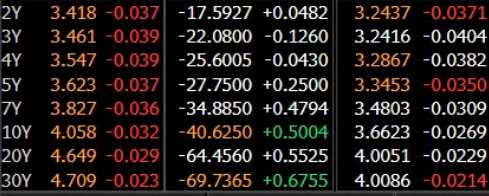
Source: Bloomberg, LLP | 9:30 AM NY Rates Snapshot
CHART 2, 2A & 2B: SWAP RATES EDGE LOWER ON SLIGHTLY BETTER-THAN-EXPECTED CPI REPORT; FED RATE CUT EXPECTATIONS HOLD STEADY
SOFR swap rates are a touch lower this morning – nothing earth shattering. The January CPI printed slightly better-than-expected, but traders keyed in on the 0.3% jump in month-on-month core CPI, the biggest monthly increase since August. Swap rates initially dipped down ~5-6 bps on the initial data print, but started to drift higher as traders parsed the CPI details.
I think the CPI result this morning was more about keeping Fed rate cut hopes alive as opposed to a catalyst for materially lower rates – I do not think the CPI numbers we saw this morning justify a significant rate move and traders seem to agree. Swap rates remain range bound, but we have tested the lows of the range the past two days. SOFR swap rates are sitting near the bottom of the recent 30-Day range. 2-Year SOFR swap rates began the week at 3.33% and are currently trading at ~3.24%.
CHART 2:Short-End SOFR Swap Rates – Prior 30 Days
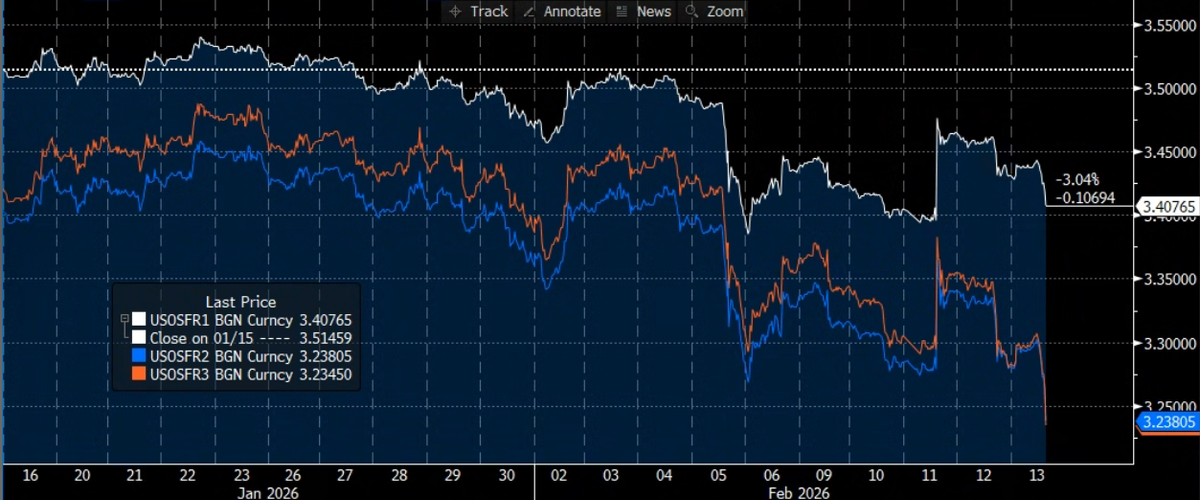
Source: Bloomberg, LLP | 1Y (white), 2Y (blue) & 3Y (orange) SOFR SWAP RATES, PRIOR 30 DAYS
CHART 2A:Long-End SOFR Swap Rates – Prior 30 Days
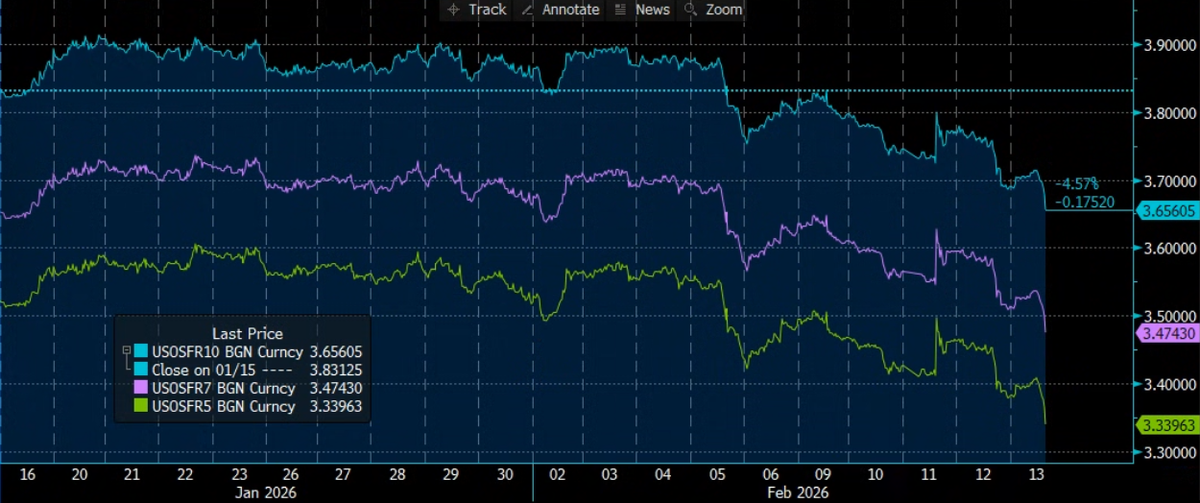
Source: Bloomberg, LLP | 5Y (green), 7Y (purple) & 10Y (light blue) SOFR SWAP RATES, PRIOR 30 DAYS
CHART 2B:Forward Market Pricing Implies Two Rate Cuts This Year
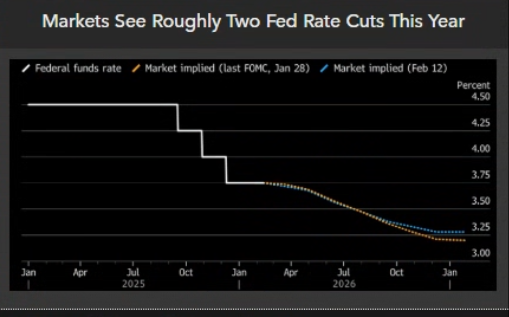
Source: Bloomberg, LLP | MARKET IMPLIED FED RATE CUTS FOR 2026
CHART 3: JANUARY CPI REPORT BEATS EXPECTATIONS, CONSUMER INFLATION MOSTLY STEADY…BUT CONCERNS REMAIN
The January CPI report showed consumer inflation remains largely in check, but stubborn core inflation continues to concern the market. The core consumer price index, which excludes more volatile food and energy costs, increased 0.3% from December, the most since August. However, core CPI rose from a year ago by the least since 2021 – 2.5%. The somewhat mixed CPI results were generally viewed positively by market participants, hence the slight drop in rates and ever-so-slight increase in Fed rate cut expectations. Odds for a “next” rate cut in June ticked a touch higher after the data dropped, but nothing dramatic. In my opinion, this was another “sigh of relief” moment for traders and market participants – relief that Fed rate cuts are still on the table for 2026!
CHART 3:January CPI Recap
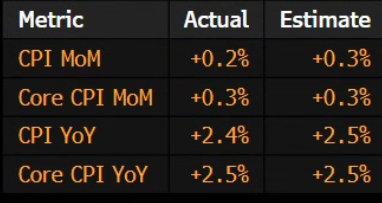
Source: Bloomberg, LLP | JANUARY CPI RECAP
RCA Product & Pricing Update:
Product Spotlight: What We Are Seeing In The Rates & Derivatives Markets
The market is again facing tremendous uncertainty surrounding the path forward for interest rates. Borrowers should be as nimble as possible in this market environment. Cap purchasers should onboard as quickly as possible – there is no cost to onboard. It is important to be in a position to take advantage of market opportunities quickly and efficiently.
Given the uncertainty that still remains about forward rates, many clients are grappling with when or if to extend. This is a difficult question – our advice has been to monitor the market closely and be on-boarded and ready to trade, should the market move in your favor. We also advise borrowers to check the market pricing for extensions, similar to how you purchased the original cap. Market pricing discovery is a key component to any cap transaction – new caps, extensions or terminations.
There is an increasing interest in exploring interest rate swaps as a possible hedge alternative. IR Swaps lock in a synthetic fixed rate and do not require an upfront premium. Unlike an interest rate cap, swaps are secured derivatives, so the counterparty selection process is more challenging with a swap. There are also additional variables that factor into the decision to pursue an interest rate swap, or to unwind an existing swap. We are also seeing a dramatic increase in swap termination advisory requests recently, as clients contemplate refinancings. Lower rates have sparked refinancing activity, which in some cases necessitates unwinding an existing swap. Please let us know if you would like to learn more about interest rate swaps, or swap terminations.
We are still seeing some residual demand for interest rate floor indications – to offset high loan floors or simply to benefit from declining variable rates. Borrowers who have “floors” embedded in their loans have been considering purchasing a separate, stand-alone interest rate floor to offset the loan floor.
Interest Rate Cap Hub: Pricing & Volatility Update for 2/13/2026
Cap premiums have been somewhat volatile intraday, but generally remain range bound
January CPI data printed as expected; market reaction was muted – cap premiums slightly lower today
Volatility remains relatively subdued; potential catalysts remain on the horizon
Current 1-Month Term SOFR = 3.65965% (Prior day: 3.65964%)
Pricing Matrix:1-Week Movement In 1-Month Term SOFR Cap Premiums
Notional Amount | Tenor | Strike Rate | ~Premium 2/6/26 | ~Premium 2/13/26* |
$25,000,000 | 1-Year | 3.50% | ~$53k | ~$52k |
$25,000,000 | 1-Year | 4.50% | ~$16k | ~$15k |
$25,000,000 | 2-Year | 3.50% | ~$115k | ~$112k |
$25,000,000 | 2-year | 4.50% | ~$22k | ~$21k |
$25,000,000 | 3-Year | 3.50% | ~$217k | ~$214k |
$25,000,000 | 3-Year | 4.50% | ~$71k | ~$68k |
*Premium levels provided are indications only and subject to change.
Please contact us if you would like to discuss an upcoming rate cap or rate cap extension, explore ways to reduce or eliminate escrow deposits for replacement caps or learn more about interest rate Caps, Floors, Swaps or Swaptions. RCA can also assist you with the voluntary early termination of your cap or swap. Hedge with an edge - The RCA Edge!
Disclaimer: The information provided in this communication is intended for discussion purposes only. Nothing presented in this communication should be taken as a recommendation or forecast. All market data shown is indicative only and subject to change depending on current market conditions. The information in this publication is confidential and is intended for the recipient only.