

Rate Markets Update · Thursday, February 5, 2026
Rates Drift Lower as Challenger Job Cuts Data Materially Misses Expectations
Flash Update: US RATE MARKETS – THURSDAY FEBRUARY 5, 2026
UST yields and SOFR swap rates are moving lower this morning on worse-than-expected job cuts data
The January Challenger Job Cuts data showed US companies announced the most job cuts for any January since 2009
Weekly jobless claims also missed expectations, which is contributing to lower rates this morning
Traders continue to closely monitor geopolitical developments
Market participants will continue to monitor developments with the DOJ investigation into the US Central Bank
A SCOTUS ruling on tariffs is now anticipated to come in February – the decision could come any day
The next FOMC rate decision is due Wednesday, March 18, 2026 at 2:00 PM
Next up for data: The delayed December JOLTS job openings report will be released this morning at 10:00 AM
Given the market’s reaction to the Challenger Job Cuts data, traders will be paying close attention to the JOLTS report results
The January Employment Report release is delayed until Wednesday, 2/11 at 8:30 AM
Short-end SOFR swap rates are trading down ~4-5 bps this morning, depending on tenor
Long-end SOFR swap rates are currently down ~3-6 bps, depending on tenor
Good Morning – US Treasury yields and SOFR swap rates are moving a few ticks lower this morning after the January Challenger Job Cuts data showed US companies announced the most jobs cuts for any January since 2009. Weekly jobless claims also missed expectations (231k actual vs. 212k expected), which is also contributing to lower rates this morning. Traders are clearly excited to see the fresh economic data - the lull in geopolitical tensions and brief economic data blackout caused traders to pause and regroup for the past few days.
This morning, rates dropped ~2-3 bps after the Challenger report was released at 7:30 AM, but traders are not overreacting to the data. The weak job cuts report follows yesterday’s weak ADP Employment Change report. The January ADP report showed a 22k increase to private payrolls – the market expected an increase of ~45k. The weaker-than-expected jobs data released this week will likely rekindle talk of a softening US labor market and perhaps, additional rate cuts.
We will receive more insight into the labor market today – the December JOLTS Job Openings report prints this morning at 10:00 AM. A weak JOLTS report is likely to push rates a touch lower, but I do not see the market carving out a definitive new trading range until after we see the January Employment Report next week. The January Employment Report is due on Wednesday, 2/11 at 8:30 AM.
Market participants will continue to track a number of potential market catalysts (equity markets; commodity markets; the geopolitical landscape; the DOJ investigation into the Fed; the Warsh nomination; the SCOTUS tariff ruling; the shape of the yield curve; US Treasury risk premiums), but I think the primary focus for traders right now is seeing current economic data. Market participants and economists are eager to see if Chair Powell’s recent upbeat assessment of the economy and monetary policy is accurate.
News the market is tracking includes:
Geopolitical developments continue to weigh on market sentiment. Geopolitical tensions continue to run high, and that is not likely to materially abate anytime soon. Markets will continue to closely monitor the situations in Venezuela, Europe, Iran and Greenland. The current lull in geopolitical tensions has forced traders into a “wait and see mode”.
Markets will be tracking developments in the US equities markets closely. There is still a sharp focus on the performance of the growing AI sector. Market sentiment is likely to be impacted by “tech” earnings for the foreseeable future.
The Supreme Court ruling on President Trump’s tariffs has not yet been released. The ruling is now expected to come this month. The SCOTUS ruling could definitely have market implications. Currently, market participants and economists believe the Supreme Court will rule against the President. Economists are unsure about the market impact of the decision – either way, the ruling is a potential catalyst for elevated rate volatility.
SCOTUS is also currently ruling on the legality of the President firing of the Fed’s Lisa Cook. That ruling is also expected to come in the near term. Chair Powell said yesterday that this is “the most important legal case in the Fed’s history”. Stay tuned!
President Trump has “asked” Fannie Mae and Freddie Mac to purchase ~$200 billion in mortgage-backed securities in order to facilitate lower mortgage rates. The market impact is uncertain at the moment. A sudden surge in purchases could impact rates and the shape of the yield curve, at least in the short-term. We will continue to track this developing story.
The US Justice Department investigation into the US Central Bank and Chairman Powell is likely to remain a key market focus moving forward.
Traders will continue to track developments with the US dollar – the recent weakness, and reaction of the US government, has baffled markets. Sustained currency weakness can be inflationary. A weak dollar can lead to “pricier” imports and a deterioration in investor confidence.
Ongoing volatile price fluctuations in the commodities markets are likely to continue to captivate the IR market for the near term. A reallocation of commodity assets could have implications for US Treasury yields.
Bottom-line, there are many potential market catalysts for traders to monitor and manage at the moment.
SOFR Swap Rate Summary: The 1Y SOFR swap rate is trading down ~4-5 bps this morning. 2Y and 3Y SOFR swap rates are currently trading down ~4-5 bps. 5Y and 10Y SOFR swap rates are currently trading down ~4-6 bps on the day. The very back-end of the swap curve is currently trading down ~3-5 bps from yesterday’s closing levels.
Please note: Market levels can change rapidly – rate cap premiums are subject to a dynamic market that can change frequently.
CHART 1:US RATES SNAPSHOT: 9:00 AM Eastern
*For SOFR Swap Rates & Change-On-Day (In Bps): Refer Two Far Right Columns (SOFR Swap Rates)
UST YIELDS | SWAP SPREADS | SOFR SWAP RATES
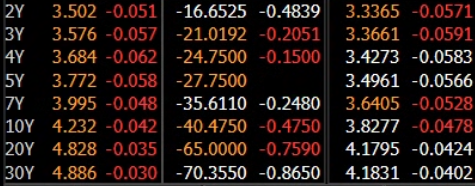
Source: Bloomberg, LLP | 9:00 AM NY Rates Snapshot
CHART 2, 2A & 2B: SOFR SWAP RATES DIP LOWER ON WORSE-THAN-EXPECTED CHALLENGER JOB CUTS REPORT
SOFR swap rates are moving lower this morning after the Challenger Job Cuts report printed much weaker-than-expected. Weekly jobless claims released this morning also posted worse-than-expected. This week we have seen mostly weaker-than-expected jobs data, leading to slightly lower swap rates. Swap rates may continue to drift lower today if the JOLTS report misses expectations. Should the JOLTS report beat expectations, we may see a small reversal in the direction of rates. Barring anything unforeseen, I do not see rates moving too dramatically ahead of next week’s January Employment report release on 2/11.
Despite a small uptick in volatility this week, swap rates remain range bound. Short-term swap rates have traded in a 10-15 basis point range since the start of the year. Longer dated swaps have also been trading in a similar 10-15 basis point range since the start of 2026. In my opinion, the market is still seeking direction. The relatively tight trading range we are in tells me uncertainty still dominates the market.
There are many potential market catalysts that have yet to be “resolved” – that’s keeping traders nervous and uncertain. The yield curve continues to gradually steepen, mostly driven by increased risk premiums for longer dated US Treasuries.
CHART 2:Short-End SOFR Swap Rates – Prior 30 Days
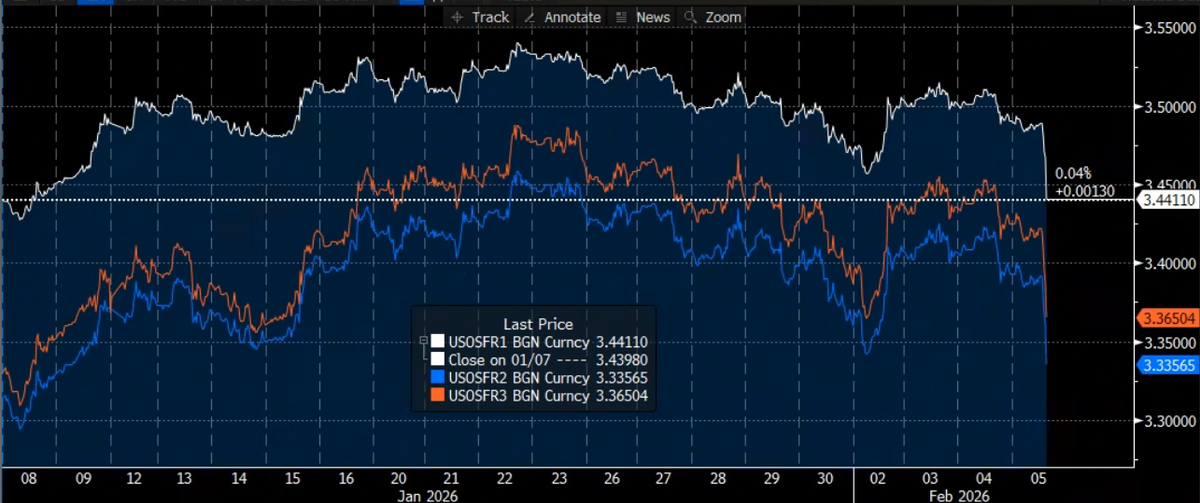
Source: Bloomberg, LLP | 1Y (white), 2Y (blue) & 3Y (orange) SOFR SWAP RATES, PRIOR 30 DAYS
CHART 2A:Long-End SOFR Swap Rates – Prior 30 Days
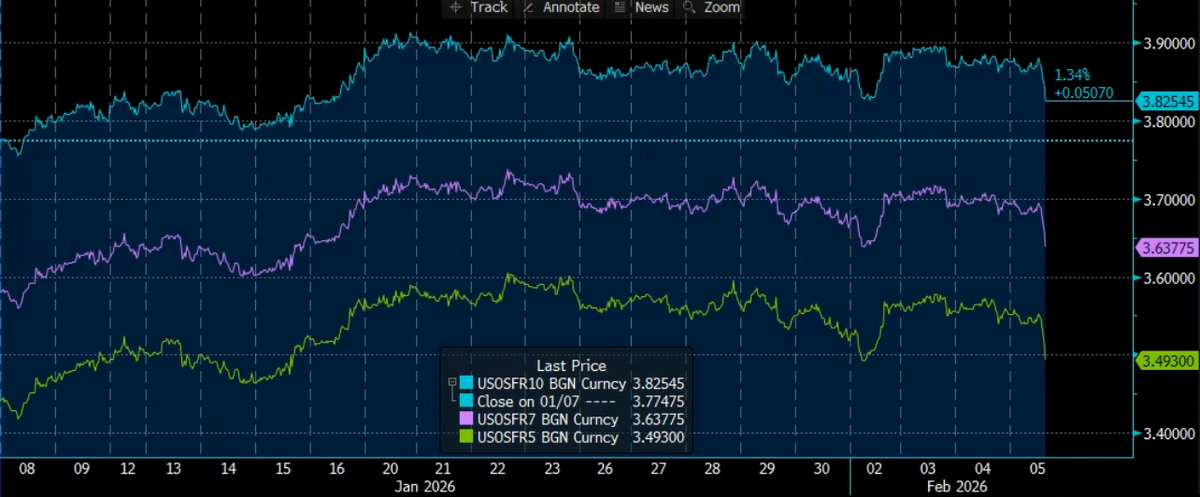
Source: Bloomberg, LLP | 5Y (green), 7Y (purple) & 10Y (light blue) SOFR SWAP RATES, PRIOR 30 DAYS
CHART 2BHistorical Challenger Job Cuts Data Since 2021
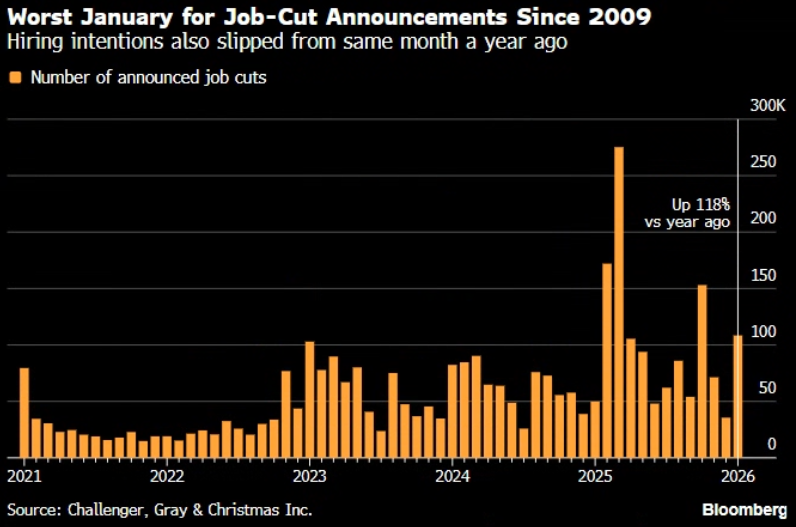
Source: Bloomberg, LLP | HISTORICAL CHALLENGER JOBS CUTS DATA SINCE 2021
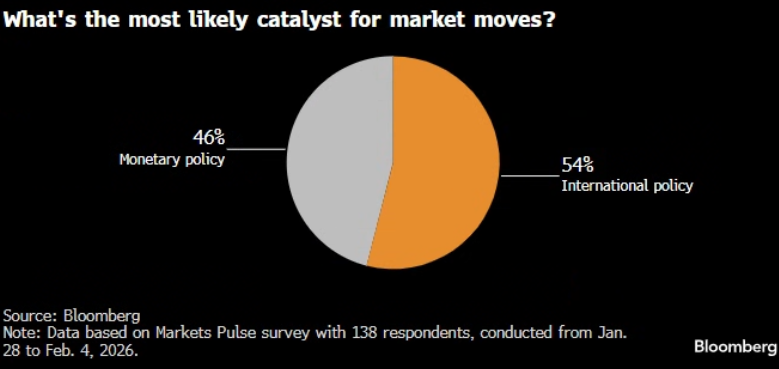
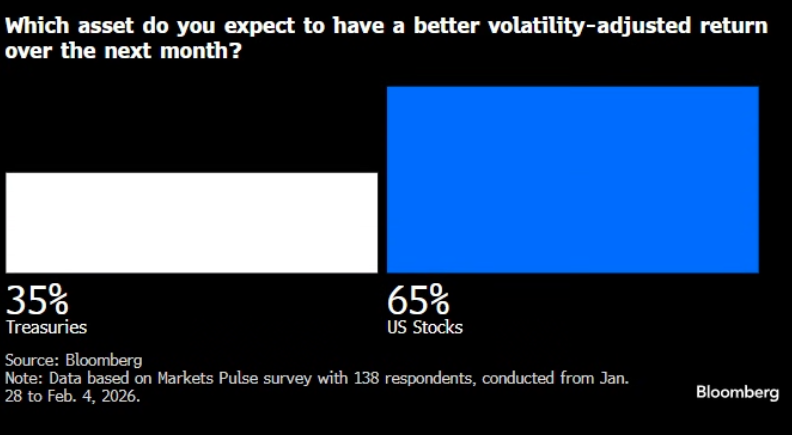
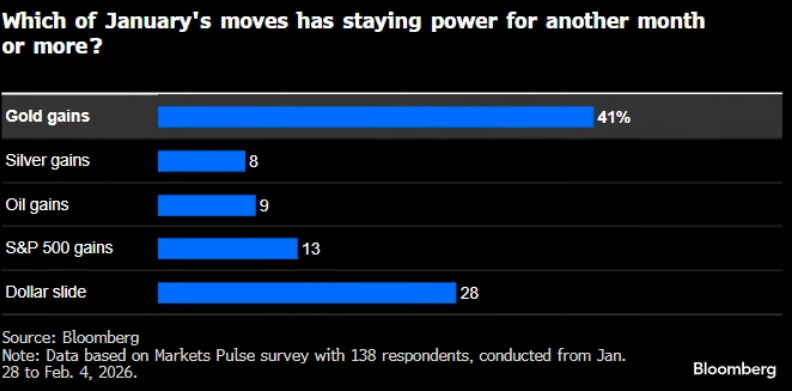
CHART 3, 3A & 3B: BLOOMBERG “MARKET PULSE” SURVEY RESULTS: AN UNCERTAIN MARKET SEEKS DIRECTION
I thought I would share some of the results of the latest Bloomberg Market Pulse Survey. In short, survey respondents see many potential market catalysts in play at the moment. Respondents believe that geopolitics has surpassed “the FOMC” (monetary policy) as the primary potential market catalyst. I will let you draw your own conclusions, but one thing is clear to me: there is a tremendous amount of uncertainty present in the market with respect to the forward path for interest rates.
CHART 3:Market Sees Geopolitics As Most Likely Near-Term Market Catalyst
Source: Bloomberg, LLP | BLOOMBERG MARKET PULSE SURVEY RESULTS
CHART 3A:Demand For Safe Haven US Treasuries Eases Due To Risk Premium, Sluggish Returns
Source: Bloomberg, LLP | BLOOMBERG MARKET PULSE SURVEY RESULTS
CHART 3B:An “Uncertain” Interest Rate Market Sees Many Potential Catalysts
Source: Bloomberg, LLP | BLOOMBERG MARKET PULSE SURVEY RESULTS
Disclaimer: The information provided in this communication is intended for discussion purposes only. Nothing presented in this communication should be taken as a recommendation or forecast. All market data shown is indicative only and subject to change depending on current market conditions. The information in this publication is confidential and is intended for the recipient only.