

Rate Markets Update · Thursday, March 12, 2026
Iran War Impact Deepens as Conflict Intensifies
- Rates Mostly Steady but Remain Biased Higher
- Traders Brace for Economic Data Due Tomorrow
Flash Update: US RATE MARKETS – THURSDAY MARCH 12, 2026
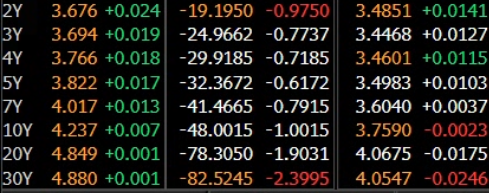
UST yields and SOFR swap rates are holding mostly steady this morning – we are seeing a slight uptick in rates on the short-end and a slight drop in long-term rates
Iran stepped-up attacks overnight, calling into question the magnitude and more importantly, the duration of the war
As the conflict intensifies, the Middle East war remains the primary market catalyst
Growing fear that the Iran war will lead to prolonged global energy production disruptions and sustained higher oil prices is resulting in dramatically higher inflation expectations
The market reaction to the SCOTUS “tariff ruling” has been largely muted as traders await more details and information
Traders will continue to track volatile equity markets, specifically the technology and AI sectors
Market participants will continue to monitor developments with the DOJ investigation into the US Central Bank
The next FOMC rate decision is due Wednesday, March 18, 2026 at 2:00 PM
Fed officials will be in the pre-meeting communications “quiet period” until March 19th
Next up for key data: January PCE, Personal Income, Personal Spending & Q4 GDP (2nd revision) data print tomorrow, March 13th @ 8:30 AM
The January JOLTS job openings report will be released tomorrow at 10:00 AM
It is challenging to forecast the possible impact of tomorrow’s economic data releases, given the ongoing Middle East conflict
At the very least, the data will provide a (relatively) current glimpse into some key areas of the economy
Short-end SOFR swap rates are trading up ~1-2 bps this morning, depending on tenor
Long-end SOFR swap rates are currently down ~1-2 bps, depending on tenor
Good Morning – US Treasury yields and SOFR swap rates are holding mostly steady this morning. Iran escalated the intensity of attacks overnight, providing a fresh wave of market anxiety. Turmoil in the global energy markets continues to fan concerns global inflation will increase significantly. Hopes for a quick resolution to the conflict are dimming, leading to speculation that oil and natural gas production could be disrupted for a sustained period of time. As we are witnessing, that can have a far reaching impact on the global economy, inflation and interest rates.
From my perspective, the market is still trading with the view that the war will be transient – I am still surprised rate volatility has not surged even more than it has. The longer the war drags-on, the worse it will be for rates. As we know, the conflict continues to intensify. The news is coming fast and furious, so I expect the market to continue to be headline driven this week.The war in the Middle East is likely to remain the primary market catalyst until it is resolved, and resolved decisively. As such, uncertainty surrounding the duration, intensity and impact of the conflict remains extremely elevated.
Tomorrow is a big day for US economic data. January PCE data will be released tomorrow, 3/13 at 8:30 AM. Right now, the war remains the primary focus for market participants, so I do not see tomorrow’s PCE data having a huge impact on rates – we are likely to see a similar reaction to the one we saw to the CPI release earlier this week. However, should the number significantly miss expectations to either side, the market may react. A below expectations print would signal inflation was contained prior to the war. A higher-than-expected PCE print could add to the inflation fears running rampant currently. Even an “at expectations” print would be subject to debate – a 3.1% core YoY PCE figure is not what the Fed wants to see. Bottom-line, it is challenging to forecast the impact of tomorrow’s PCE release. The expectations for tomorrow’s PCE print are as follows: Headline MoM, 0.3% (vs. 0.4% the prior month); Core MoM, 0.4% (vs. 0.4% prior); Headline YoY, 2.9% (vs. 2.9% prior); Core YoY, 3.1% (vs. 3.0% prior).
We will also see January Personal Income and Personal Spending data released tomorrow at 8:30 AM. Expectations are as follows: Personal Income, 0.5% (vs. 0.3% the prior month); Personal Spending, 0.3% (vs. 0.4% prior). The JOLTS job openings report is also released tomorrow at 10:00 AM.
Finally, the second revision to Q4 GDP is released tomorrow at 8:30 AM. Expectations are as follows: Q4 GDP, 1.4% (unchanged); GDP Price Index, 3.6% (unchanged). A better-than-expected GDP revision would likely result in slightly scaled back Fed rate cut expectations. A weaker-than-expected revision would like keep the door ajar for a Fed rate cut in the second half of the year, or perhaps sooner depending on what happens in the Middle East.
There is definitely the possibility for whip-saw movements in rates this week, and I anticipate volatility will remain at elevated levels. Rates are likely to be biased higher until the oil market stabilizes.
News the market is tracking includes:
Geopolitical developments continue to weigh on market sentiment.The US/Iran “war” will likely dominate market sentiment this week. The end result of the US attack on Iran is difficult to forecast at this time. Currently, the major impacts thus far have been higher oil prices, higher rates, and a surge in geopolitical tensions.
SCOTUS is also currently ruling on the legality of the President firing of the Fed’s Lisa Cook. There are some reports stating that SCOTUS is nearing a final decision on that case, which could have far reaching implications for the US Central Bank.
The US Justice Department investigation into the US Central Bank and Chairman Powell will remain a key market focus moving forward.
Market participants continue to closely track developments in the US equities markets. There is still a sharp focus on the performance of the growing AI sector. Market sentiment is likely to be impacted by “tech” earnings for the foreseeable future.
The market continues to monitor US political developments. Traders are watching for signs of another potential government shutdown. US political developments will remain front-and-center for the market for the foreseeable future.
Traders and investors continue to assess the market implications of the recent SCOTUS ruling on President Trump’s tariffs. Market participants await more data and information.
SOFR Swap Rate Summary: The 1Y SOFR swap rate is trading up ~1-2 bps this morning. 2Y and 3Y SOFR swap rates are currently trading up ~1-2 bps. 5Y and 10Y SOFR swap rates are trading flat to up ~1-2 bps on the day. The very back-end of the swap curve is currently trading down ~1-2 bps from yesterday’s closing levels. Expect increased levels of rate volatility today.
Please note: Market levels can change rapidly – rate cap premiums are subject to a dynamic market that can change frequently.
CHART 1:US RATES SNAPSHOT: 9:30 AM Eastern
*For SOFR Swap Rates & Change-On-Day (In Bps): Refer Two Far Right Columns (SOFR Swap Rates)
UST YIELDS | SWAP SPREADS | SOFR SWAP RATES
Source: Bloomberg, LLP | 9:30 AM NY Rates Snapshot
CHART 2, 2A & 2B: SOFR SWAP RATES STEADY AS MARKET PARTICIPANTS NERVOUSLY MONITOR WAR DEVELOPMENTS
SOFR swap rates are holding mostly steady this morning, as the conflict in the Middle East rages on. There still does not appear to be a quick resolution in sight. The Iranian attacks overnight are forcing traders to reassess the “war outlook”. As I have been saying recently, it is extremely difficult to chart the path forward for US rates currently. There are simply too many wildcards to form a consistent, confident rate view.
Rates are still biased higher in my opinion, as energy market led inflation fears continue to dominate the market. Short-end SOFR swap rates have broken out of the recent trading range due to reduced Fed rate cut expectations and war-related inflation fears. Longer-term swap rates have also moved higher on inflation fears, but are still trading just within the recent range.
I expect rates to remain asymmetrically biased higher as long as “oil fears” dominate the market. The 2-year SOFR swap rate closed at 3.21% on Friday 2/27 – it is currently trading at ~3.485% (+27.5 bps). The 10-year SOFR swap rates has experienced a similar move – it closed Friday night at 3.52% and is currently trading at ~3.76% (+24 bps).
CHART 2:Short-End SOFR Swap Rates – Prior 30 Days
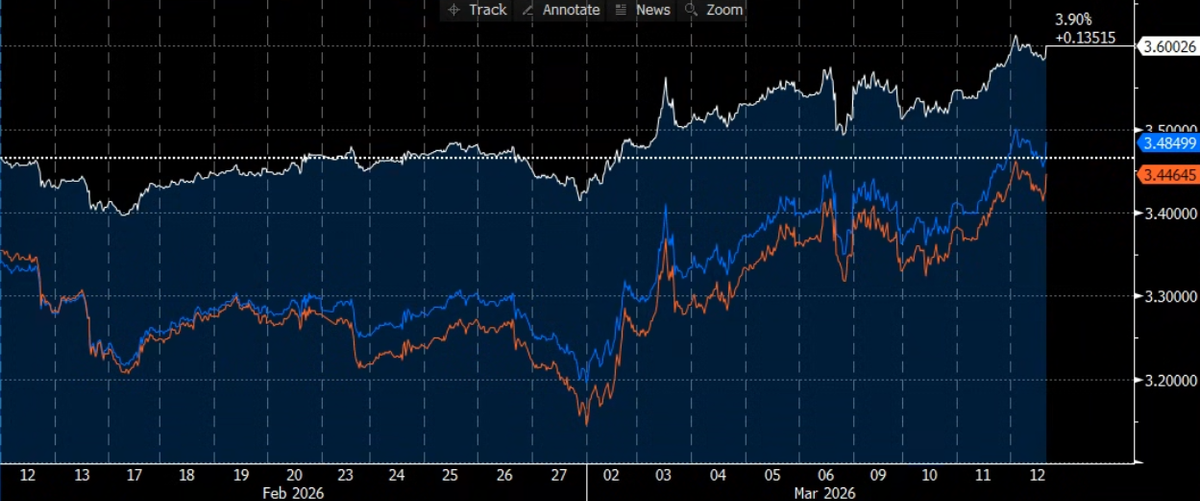
Source: Bloomberg, LLP | 1Y (white), 2Y (blue) & 3Y (orange) SOFR SWAP RATES, PRIOR 30 DAYS
CHART 2A:Long-End SOFR Swap Rates – Prior 30 Days
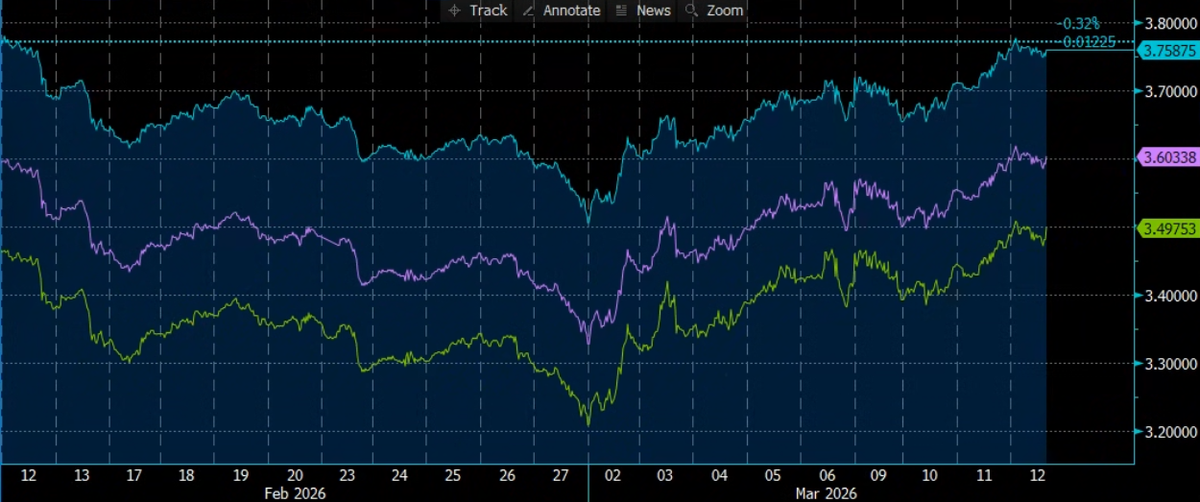
Source: Bloomberg, LLP | 5Y (green), 7Y (purple) & 10Y (light blue) SOFR SWAP RATES, PRIOR 30 DAYS
CHART 2B:Iran War-Related Inflation Fears Continue To Put Upward Pressure On Long-Term US Treasuries
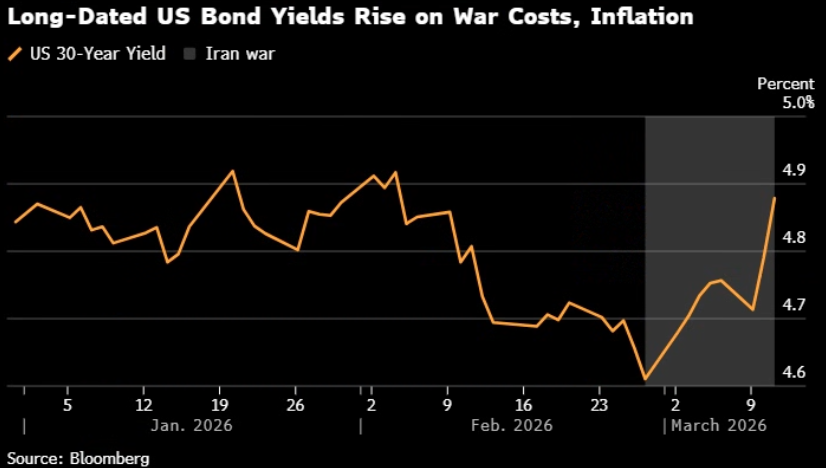
Source: Bloomberg, LLP | MOVEMENT IN 30Y UST YIELDS SINCE JAN 1, 2026
Please contact us if you would like to discuss an upcoming rate cap or rate cap extension, explore ways to reduce or eliminate escrow deposits for replacement caps or learn more about interest rate Caps, Floors, Swaps or Swaptions. RCA can also assist you with the voluntary early termination of your cap or swap.
HedgeWithAnEdge-TheRCAEdge!
Disclaimer: The information provided in this communication is intended for discussion purposes only. Nothing presented in this communication should be taken as a recommendation or forecast. All market data shown is indicative only and subject to change depending on current market conditions. The information in this publication is confidential and is intended for the recipient only.