

Rate Markets Update · Wednesday, March 18, 2026
Hot February PPI Print Lifts Rates
- Market Awaits Fed Rate Decision
Flash Update: US RATE MARKETS – WEDNESDAY MARCH 18, 2026
UST yields and SOFR swap rates are edging higher this morning, after February PPI data printed much hotter-than-expected
The hot PPI print augments inflation concerns that are already front-and-center for market participants due to the war in the Middle East
Traders and market participants also await this afternoon’s FOMC rate decision and Chairman Powell’s press conference
We will also see a revised Fed dot-plot and economic projections (SEP) released this afternoon
The new consensus Fed dot-plot is forecasted to show one, and possibly no rate cuts this year
The next FOMC rate decision is due today, March 18th at 2:00 PM; Chairman Powell’s press conference will immediately follow the rate announcement at 2:30 PM
Fed officials remain in the pre-meeting communications “quiet period” until March 19th
The market reaction to the SCOTUS “tariff ruling” has been largely muted as traders await more details and information
Traders will continue to track volatile equity markets, specifically the technology and AI sectors
Market participants will continue to monitor developments with the DOJ investigation into the US Central Bank
The war in the Middle East remains the primary focus for the rate markets
Short-end SOFR swap rates are trading up ~2-4 bp this morning, depending on tenor
Long-end SOFR swap rates are currently up ~1-3 bps, depending on tenor
Good Morning – US Treasury yields and SOFR swap rates are edging higher this morning after February PPI printed much hotter-than-expected. Perhaps the most disconcerting component of PPI was the YoY Core PPI result, which jumped to 3.9% from 3.5% the prior month. Needless to say, that is simply too high for the Fed’s liking. The PPI data definitely shifted the market’s focus back to inflation, at least for today – that is the primary reason we are seeing rates tick higher this morning, particularly on the short-end of the curve. That said, traders are being somewhat careful not to ‘overreact’ to the PPI data, especially given the proximity of the data release to the FOMC rate decision. Oil prices began to March higher again this morning, which is keeping upward pressure on rates across the curve.
The market friction between potential higher inflation and potential damage to economic growth will continue to grow as long as the war rages on. If traders begin to believe that weaker economic growth is the likely outcome, that would make a strong case for Fed rate cuts, and we would see rates begin to drop further, perhaps materially. If not, and inflation gaps higher but growth stabilizes, rate cuts are likely off the table and you will start to hear whispers that the Fed’s next move will be a rate hike. Worst case, both happen and we experience the dreaded stagflation, which is challenging to manage with traditional monetary policy moves.
Besides the ongoing Middle East conflict, which will remain the primary market catalyst for the near term, the big market news this week is the FOMC rate announcement due this afternoon at 2:00 PM. Market participants do not expect the Fed to move rates (odds imply a 1.0% chance for a rate cut today), but they will be very interested to see the new SEP (economic projections), Dot-Plot and official statement. Traders will also be laser focused on Chairman Powell’s comments at his post-meeting press conference. Yes, he is “on his way out”, but he is the mouthpiece for the Fed, and he often refers to “committee thinking” when making his comments. A lot has changed since the last Fed meeting – market participants are eager to hear the Fed’s perspective. Fed officials will emerge from the pre-meeting quiet period on 3/19, so we will see a deluge of Fed commentary in the days immediately following the meeting.
As you would expect, market participants will continue to nervously monitor the latest war developments. The longer the war drags on and oil prices remain elevated, the greater the threat to global economic growth and inflation. There is also a growing threat of stagflation – the war could damage global economic growth and lead to higher inflation. The revision to GDP last week, coupled with the red-hot PPI data released today, certainly whisper “stagflation” to me, and we have yet to experience the full inflation and economic growth impacts of the war. Stagflation would make the Fed’s job even more challenging.
I expect the market to continue to be “headline” driven for the near term. The conflict in the Middle East remains the market’s primary focus. There is definitely the possibility for whip-saw movements in rates this week, and I anticipate volatility will remain at elevated levels.
News the market is tracking includes:
Geopolitical developments continue to weigh on market sentiment.The US/Iran “war” will likely dominate market sentiment this week. The end result of the US attack on Iran is difficult to forecast at this time. Currently, the major impacts thus far have been higher oil prices, higher rates, and a surge in geopolitical tensions.
SCOTUS is also currently ruling on the legality of the President firing of the Fed’s Lisa Cook. There are some reports stating that SCOTUS is nearing a final decision on that case, which could have far reaching implications for the US Central Bank.
The US Justice Department investigation into the US Central Bank and Chairman Powell will remain a key market focus moving forward.
Market participants continue to closely track developments in the US equities markets. There is still a sharp focus on the performance of the growing AI sector. Market sentiment is likely to be impacted by “tech” earnings for the foreseeable future.
The market continues to monitor US political developments. US political developments will remain a major focus for the market for the foreseeable future.
Traders and investors continue to assess the market implications of the recent SCOTUS ruling on President Trump’s tariffs. Market participants await more data and information.
Market participants are growing more and more concerned with the ongoing “partial” government shutdown. Traders are hoping the situation is resolved quickly – a full government shut-down would be extremely challenging to manage during a war.
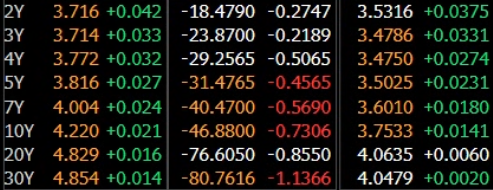
SOFR Swap Rate Summary: The 1Y SOFR swap rate is trading up ~2-3 bps this morning. 2Y and 3Y SOFR swap rates are currently trading up ~2-4 bps. 5Y and 10Y SOFR swap rates are trading up ~1-3 bps on the day. The very back-end of the swap curve is currently trading up ~1 bp from yesterday’s closing levels.
Please note: Market levels can change rapidly – rate cap premiums are subject to a dynamic market that can change frequently.
CHART 1:US RATES SNAPSHOT: 9:30 AM Eastern
*For SOFR Swap Rates & Change-On-Day (In Bps): Refer Two Far Right Columns (SOFR Swap Rates)
UST YIELDS | SWAP SPREADS | SOFR SWAP RATES
Source: Bloomberg, LLP | 9:30 AM NY Rates Snapshot
CHART 2 & 2A: SOFR SWAP RATES EDGE HIGHER ON HOT PPI PRINT
SOFR swap rates are ticking a touch higher this morning after hotter-than-expected February PPI data. The PPI data results augmented growing market concerns about higher inflation due to the ongoing war in the Middle East. Traders now await this afternoon’s FOMC rate decision and Chairman Powell’s press conference. Traders and market participants continue to anxiously monitor developments in the Middle East crisis – I still expect rates to remain asymmetrically biased higher as long as “oil fears” dominate the market.
Key Swap Rate Movement Since The War Began: The 2-year SOFR swap rate closed at 3.21% on Friday 2/27 – it is currently trading at ~3.53% (+32 bps). The 5-year SOFR swap rate closed at 3.22% on Friday 2/27 – it is currently trading at ~3.50% (+28 bps). The 10-year SOFR swap rates has experienced a similar move – it closed Friday 2/27 at 3.52% and is currently trading at ~3.755% (+23.5 bps).
CHART 2:Short-End SOFR Swap Rates – Prior 30 Days
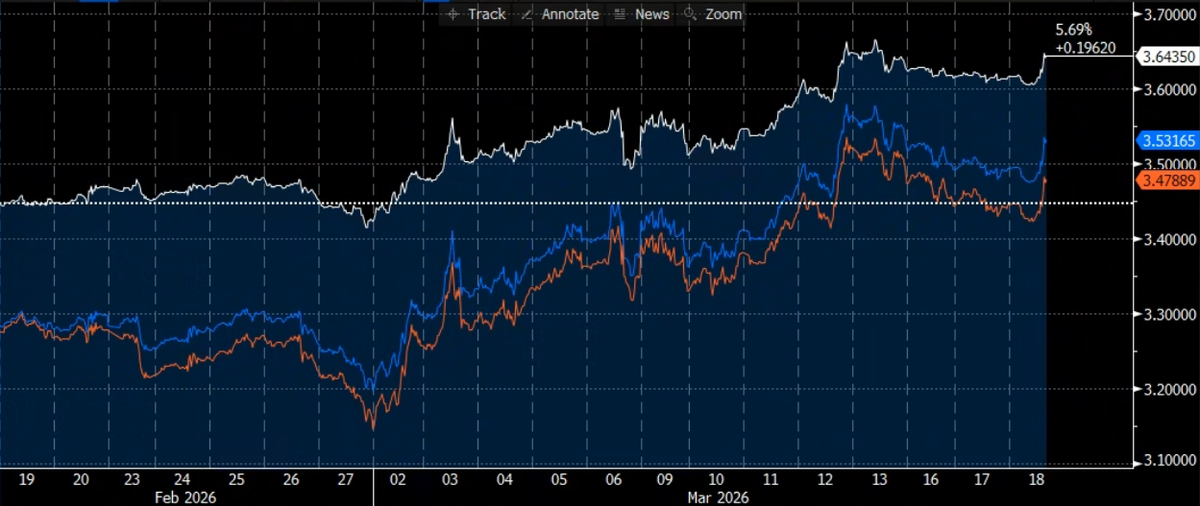
Source: Bloomberg, LLP | 1Y (white), 2Y (blue) & 3Y (orange) SOFR SWAP RATES, PRIOR 30 DAYS
CHART 2A:Long-End SOFR Swap Rates – Prior 30 Days
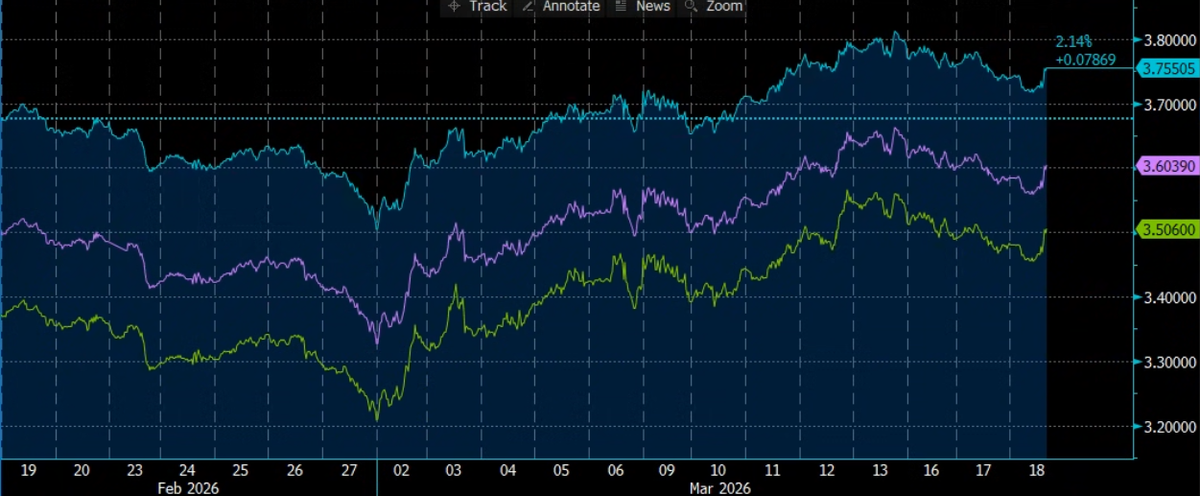
Source: Bloomberg, LLP | 5Y (green), 7Y (purple) & 10Y (light blue) SOFR SWAP RATES, PRIOR 30 DAYS
CHART 3 & 3A: FEBRUARY PPI RECAP: HOT PPI PRINT LIFTS RATES, DEEPENS INFLATION CONCERNS
PPI wholesale inflation results for February unexpectedly accelerated from a month earlier, reflecting higher costs for goods and services. Headline PPI rose 0.7% in February (vs. 0.3% expected), after a 0.5% gain in January. Core PPI, which excludes food an energy prices, advanced 0.5% from a month earlier, vs. expectations calling for a gain of 0.3%. The YoY components of CPI were even scarier: YoY Headline PPI printed at 3.4% and YoY Core PPI increased to 3.9% - in my opinion those numbers are simply way too high for the Fed to even consider cutting rates at the next few meetings. The war has also lead to a spike in oil prices, which remains a key inflation wildcard for market participants. To me, the PPI number signals cost pressures were growing even before the war.
CHART 3:February PPI Recap
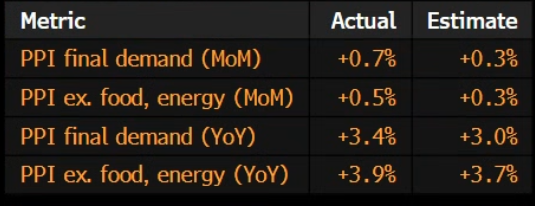
Source: Bloomberg, LLP | FEBRUARY PPI RECAP
CHART 3A:Historical PPI Data
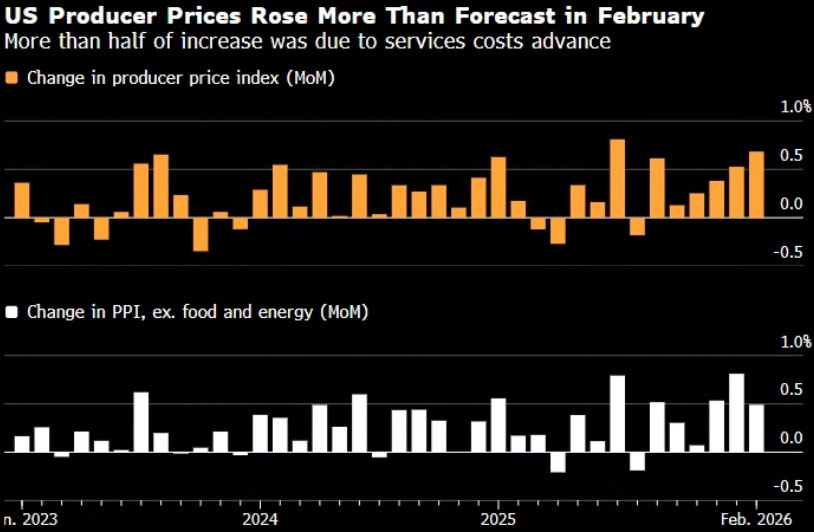
Source: Bloomberg, LLP | HISTORICAL PPI DATA SINCE 2023
Please contact us if you would like to discuss an upcoming rate cap or rate cap extension, explore ways to reduce or eliminate escrow deposits for replacement caps or learn more about interest rate Caps, Floors, Swaps or Swaptions. RCA can also assist you with the voluntary early termination of your cap or swap.
HedgeWithAnEdge-TheRCAEdge!
Disclaimer: The information provided in this communication is intended for discussion purposes only. Nothing presented in this communication should be taken as a recommendation or forecast. All market data shown is indicative only and subject to change depending on current market conditions. The information in this publication is confidential and is intended for the recipient only.