

Rate Markets Update · Wednesday, May 13, 2026
Rates Steady as Traders Mull Hot PPI Data
- US-China Summit Begins
- Traders Anxiously Monitor War Developments
Flash Update: US RATE MARKETS – WEDNESDAY MAY 13, 2026
UST yields and SOFR swap rates are holding mostly steady this morning despite the much hotter-than-expected April PPI data
The hot April PPI data was mainly due to increased energy prices stemming from the conflict in the Middle East
The status of the US-Iran war remains in limbo; There is no timetable for the next round of talks between the two sides
Market participants and traders have shifted into a “wait-and-see” mode as they anxiously monitor war developments
The US/Iran war remains the primary focus for the rate markets
President Trump arrives in China this morning for a high stakes trade summit with Chinese President Xi
Next up for Key Data: April Retail Sales results will be released tomorrow, 5/14 at 8:30 AM
Short-term SOFR swap rates are trading flat to down ~1 bp this morning, depending on tenor
Medium-term SOFR swap rates are flat to down ~1 bp currently, depending on tenor
Long-end SOFR swap rates are flat to down ~1 bp this morning, depending on tenor
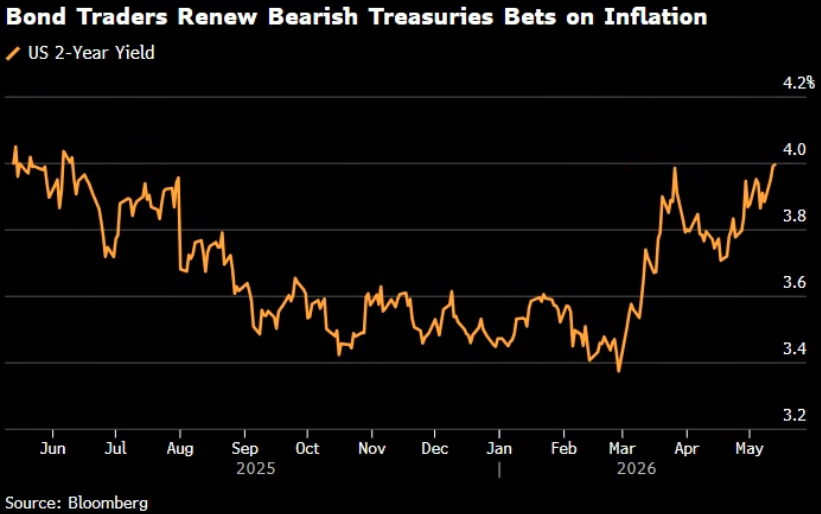
Good morning – US Treasury yields and SOFR swap rates are holding mostly steady this morning, despite a hot April PPI print. The hot PPI data renewed fear about a war-induced resurgence in inflation. That said, traders mostly ignored the number! The hot PPI data comes directly on the heels of yesterday’s much stronger-than-expected consumer inflation data (CPI). The fact rates have not moved even higher after the hot inflation data released this week tells me traders are being very cautious not to overreact. There is still an underlying feeling in the market that a peace deal can and will be reached soon. There is also the possibility that traders feel the rise in rates since the war began already reflects the risk of higher inflation. We shall see. That said, the uptick in rates since last week tells me traders are frustrated by the lack of progress toward a peace deal – each day the war lingers puts more upward pressure on inflation. Eventually, economic growth will also be negatively impacted.
The overall market theme we have been tracking recently continues – progress towards a US/Iran peace deal and/or lower oil prices will likely lead to lower rates and more stable markets. Conversely, if we see indications that the peace deal will not happen, the next round of negotiations is significantly delayed or hostilities resume, we are likely to get higher oil prices and higher rates. Traders will continue to anxiously monitor war developments as the “negotiation” news unfolds.
Next up for data is tomorrow’s April Retail Sales data. A resilient US consumer has been propping up the economy for some time, so traders will be very interested to see if the war is impacting consumer spending. We have already seen evidence that consumers are backing off due to higher gasoline prices and uncertainty surrounding the inflation impact of the war. Expectations for tomorrow’s Retail Sales data are as follows: Headline Retail Sales, 0.5% (vs. 1.7% the prior month); Retail Sales ex Autos, 0.7% (vs. 1.9% prior).
“Key News” the market is tracking includes:
Geopolitical developments continue to weigh on markets.The US/Iran “war” continues to dominate market sentiment this week.
The US Justice Department has dropped the investigation into the US Central Bank and Chairman Powell, likely clearing the way for Kevin Warsh to be confirmed as the next FOMC Chairman.From the market’s perspective, there are still many questions surrounding both Mr. Warsh’s monetary policy views, and what is next for Jay Powell.
Market participants continue to closely track developments in the US equities markets. There is still a sharp focus on the performance of the growing AI sector. Overall market sentiment, and perhaps even economic performance, could be impacted by “tech” earnings for the foreseeable future.
Traders are growing increasingly concerned with the record-setting “partial” government shutdown currently underway. Traders are still hoping the situation is resolved quickly.
SCOTUS is currently ruling on the legality of the President firing of the Fed’s Lisa Cook. There are some reports stating that SCOTUS is nearing a final decision on that case, which could have far reaching implications for the US Central Bank.
SOFR Swap Rate Summary: The 1Y SOFR swap rate is trading flat to down ~1 bp this morning. 2Y and 3Y SOFR swap rates are currently trading flat to down ~1 bp. 5Y and 10Y SOFR swap rates are trading flat to down ~1 bp on the day. The very back-end of the swap curve is currently trading flat to up ~1 bp from yesterday’s closing levels.
Please note: Market levels can change rapidly – rate cap premiums are subject to a dynamic market that can change frequently.
CHART 1:US RATES SNAPSHOT: 9:30 AM Eastern
Chart 1 Key:
Far Left Columns:US Treasury Yields & Change on Day (bps)
Center Columns:SOFR OIS Swap Spreads (bps) & Change on Day (bps)
Far Right Columns:SOFR OIS Swap Rates & Change on Day (bps)
UST YIELDS | SWAP SPREADS | SOFR SWAP RATES
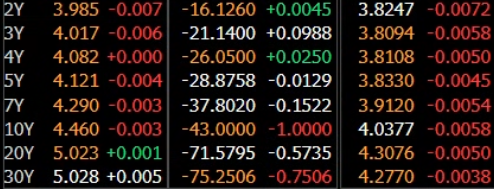
Source: Bloomberg, LLP | 9:45 AM NY Rates Snapshot
CHART 2, 2A & 2B: SOFR SWAP RATES MOSTLY STEADY AS MARKET WEIGHS INFLATION DATA, WAR OUTLOOK
SOFR swap rates are holding mostly steady this morning as traders weigh the hotter-than-expected PPI results released this morning. The strong PPI data comes on the heels of yesterday’s CPI data, which also printed well above expectations. Right now, market uncertainty remains elevated as the timetable for the next round of peace talks remains in limbo. Barring an unexpected announcement that a peace deal has been reached, I expect swap rates to remain biased higher in the near-term. I expected swap rates to move higher after the number – so far, traders are resisting the temptation to take rates higher. I would note, we have now reached new “war-highs” for swap rates.
Key SOFR Swap Rate Movements Since The US-Iran War Began:
The 2-year SOFR swap rate closed at 3.21% on Friday 2/27 – it is currently trading at ~3.824%(+61.4 bps).
The 5-year SOFR swap rate closed at 3.22% on Friday 2/27 – it is currently trading at ~3.833%(+61.3 bps).
The 10-year SOFR swap rate closed at 3.52% on Friday 2/27 – it is currently trading at ~4.038%(+51.8 bps).
CHART 2:Short-End SOFR Swap Rates – Since 2/27/2026 (Start of War)
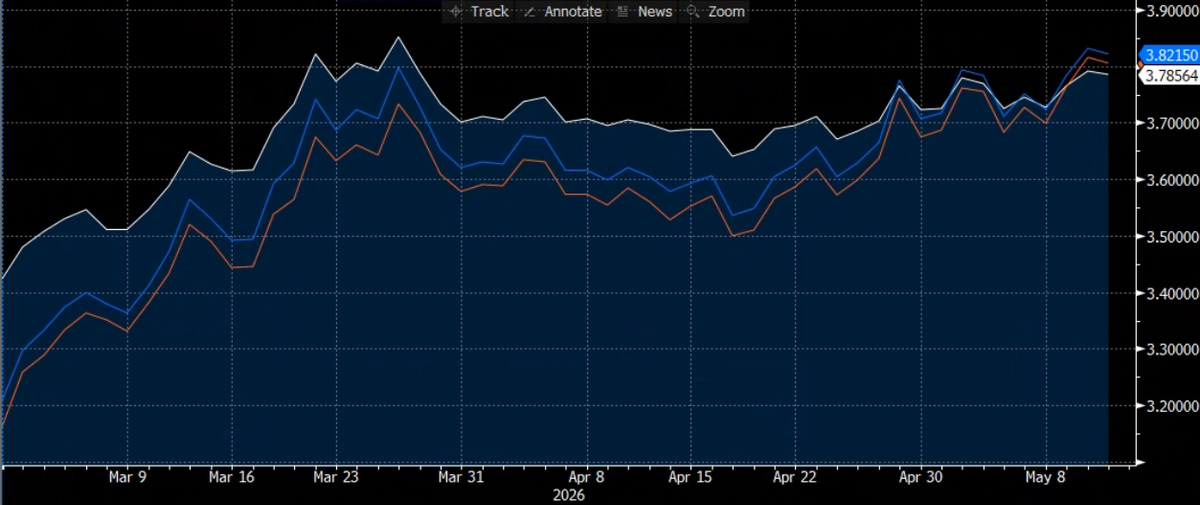
Source: Bloomberg, LLP | 1Y (white), 2Y (blue) & 3Y (orange) SOFR SWAP RATES; SINCE 2/27/2026
CHART 2A:Long-End SOFR Swap Rates – Since 2/27/2026 (Start of War)
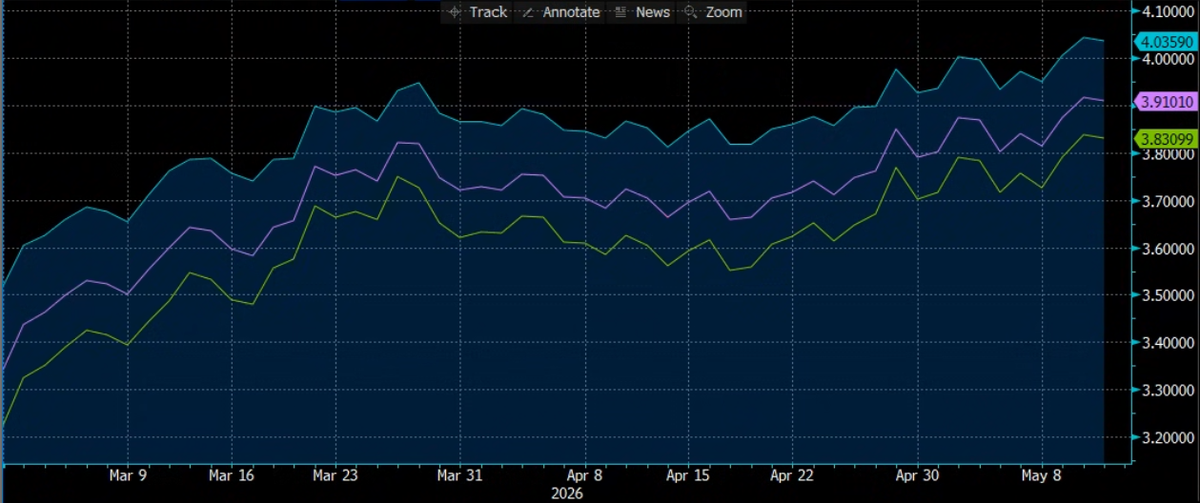
Source: Bloomberg, LLP | 5Y (green), 7Y (purple) & 10Y (light blue) SOFR SWAP RATES; SINCE 2/27/2026
CHART 2B:US Treasuries: Yield Overview Since November 2025
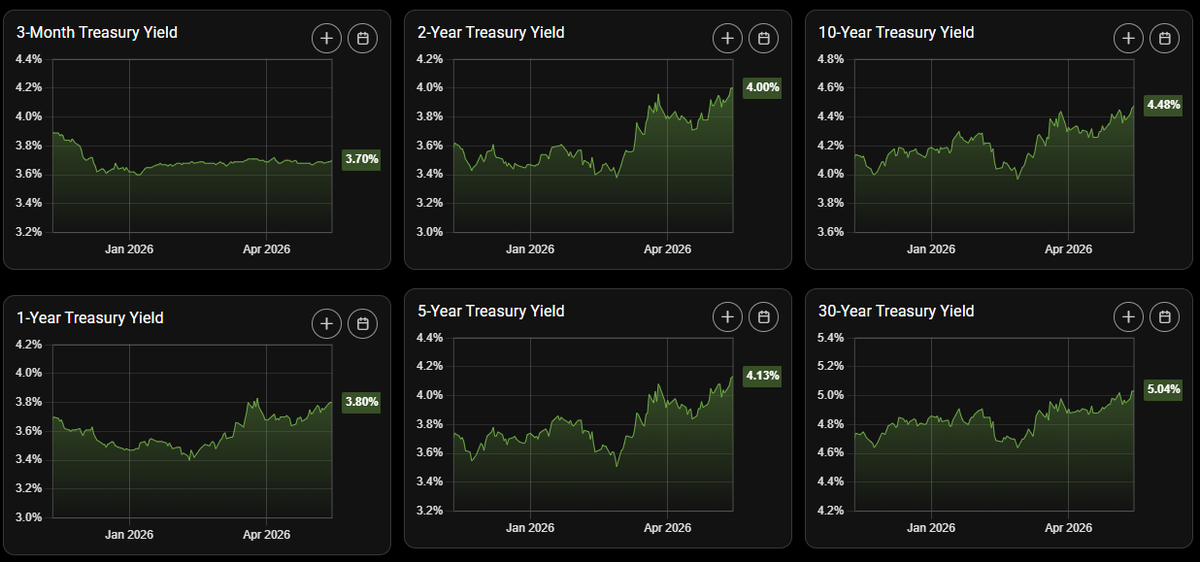
Source: StreetStats | US Treasury Bill, Note & Bond Yields; Prior 6-Months
CHART 3 & 3A: APRIL PPI RECAP – HOT PPI DATA FUELS INFLATION CONCERNS
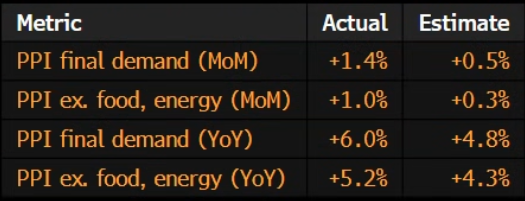
Producer prices accelerated in April to the fastest pace since 2022 on a war-induced increase in energy prices. A significant increase in energy costs is feeding into higher freight transportation costs. Headline PPI rose 6% from a year ago, topping the consensus estimate of 4.8%. Core PPI, which excludes food and energy prices, increased 5.2% from April 2025 — the biggest advance in more than three years. Headline PPI also showed the sharpest monthly gain since 2022, increasing 1.4% in April. Core PPI detailed a robust monthly gain of 1.0% — economists anticipated a gain of 0.5% in April.
Bottom line, the inflation data we have seen this week is rapidly moving in the wrong direction. However, traders are being cautious not to overreact to the data, as they are clinging to an underlying hope that a deal to end the war can be reached soon. I believe that is what is keeping rates in check for the moment.
CHART 3:April PPI Recap
Source: Bloomberg, LLP | APRIL PPI RECAP
CHART 3A:Fear of a Resurgence in Inflation Continues to Drive Rates Higher
Source: Bloomberg, LLP | US 2-YEAR TREASURY NOTE YIELD, PRIOR 12-MONTHS
RCA Product & Pricing Update:
Product Spotlight: What We Are Seeing In The Rates & Derivatives Markets
The market is again facing tremendous uncertainty surrounding the path forward for interest rates. Borrowers should be as nimble as possible in this market environment. Cap purchasers should onboard as quickly as possible – there is no cost to onboard. It is important to be in a position to take advantage of market opportunities quickly and efficiently.
Given the uncertainty that still remains about forward rates, many clients are grappling with when or if to extend. This is a difficult question – our advice has been to monitor the market closely and be on-boarded and ready to trade, should the market move in your favor. We also advise borrowers to check the market pricing for extensions, similar to how you purchased the original cap. Market pricing discovery is a key component to any cap transaction – new caps, extensions or terminations.
There is an increasing interest in exploring interest rate swaps as a possible hedge alternative. IR Swaps lock in a synthetic fixed rate and do not require an upfront premium. Unlike an interest rate cap, swaps are secured derivatives, so the counterparty selection process is more challenging with a swap. There are also additional variables that factor into the decision to pursue an interest rate swap, or to unwind an existing swap. We are also seeing a dramatic increase in swap termination advisory requests recently, as clients contemplate refinancings. Lower rates have sparked refinancing activity, which in some cases necessitates unwinding an existing swap. Please let us know if you would like to learn more about interest rate swaps, or swap terminations.
We are still seeing some residual demand for interest rate floor indications – to offset high loan floors or simply to benefit from declining variable rates. Borrowers who have “floors” embedded in their loans have been considering purchasing a separate, stand-alone interest rate floor to offset the loan floor.
Interest Rate Cap Hub: Pricing & Volatility Update for 5/13/2026
The uncertain US-Iran war outlook, and hotter-than-expected inflation data, are nudging rates higher, leading to higher cap premiums
Rate volatility remains relatively subdued, as the market participants and traders move into a “wait-and-see” mode
Current 1-Month Term SOFR = 3.62852% (Prior day: 3.63229%)
1-Month Term SOFR has been quietly drifting lower over the past two weeks and is currently sitting at a 12-month low
Pricing Matrix:1-Week Movement In 1-Month Term SOFR Cap Premiums
Notional Amount | Tenor | Strike Rate | ~Premium 5/6/26 | ~Premium 5/13/26*^ |
$25,000,000 | 1-Year | 3.50% | ~$94k | ~$98k |
$25,000,000 | 1-Year | 4.50% | ~$25k | ~$30k |
$25,000,000 | 2-Year | 3.50% | ~$259k | ~$263k |
$25,000,000 | 2-year | 4.50% | ~$94k | ~$98k |
$25,000,000 | 3-Year | 3.50% | ~$427k | ~$430k |
$25,000,000 | 3-Year | 4.50% | ~$180k | ~$187k |
*Indications as of market open. Premium levels provided are indications only and subject to change.
^NOTE: MARKET DYNAMICS AND PRICING CAN CHANGE VERY QUICKLY IN THIS MARKET ENVIRONMENT.
WE RECOMMEND YOU CALL US FOR ACCURATE, UP-TO-THE-MINUTE CAP INDICATIONS.
Please contact us if you would like to discuss an upcoming rate cap or rate cap extension, explore ways to reduce or eliminate escrow deposits for replacement caps or learn more about interest rate Caps, Floors, Swaps or Swaptions. RCA can also assist you with the voluntary early termination of your cap or swap.
HedgeWithAnEdge-TheRCAEdge!
Disclaimer: The information provided in this communication is intended for discussion purposes only. Nothing presented in this communication should be taken as a recommendation or forecast. All market data shown is indicative only and subject to change depending on current market conditions. The information in this publication is confidential and is intended for the recipient only.