

Rate Markets Update · Tuesday, May 19, 2026
Rates Tick Higher as Inflation Fear Dominates Market Sentiment
Flash Update: US RATE MARKETS – TUESDAY MAY 19, 2026
UST yields and SOFR swap rates are ticking higher this morning as fear of higher inflation dominates market sentiment
The status of the US-Iran war remains in limbo, which is making traders and investors increasingly worried about dramatically higher inflation
Medium and long dated US Treasury yields are approaching levels last seen in 2007
The US/Iran war remains the primary focus for the rate markets
Next up for data: No major data is scheduled for release this week. The FOMC meeting minutes for April will be released tomorrow 5/20 @ 2:00 PM
The next FOMC rate decision is due on Wednesday, June 17th at 2:00 PM
Short-term SOFR swap rates are trading up ~3-7 bps this morning, depending on tenor
Medium-term SOFR swap rates are up ~5-7 bps currently, depending on tenor
Long-end SOFR swap rates are up ~4-6 bps this morning, depending on tenor
Good morning – US Treasury yields and SOFR swap rates are once again ticking higher this morning. A lack of progress on a Middle East peace plan is frustrating market participants and exacerbating inflation fears. Oil prices remain elevated, which is putting sustained pressure on global prices. Traders are being very careful not to overreact – there is still lingering optimism that the two sides are inching toward a resolution to the conflict. That lingering optimism is likely the main reason rates have not moved even higher.
Market participants, in my opinion, continue to exercise patience and restraint in the hope that a peace plan can be reached soon. I expect markets to remain jittery the rest of this week and there is the potential for a sudden, material move in rates if we get some verifiable news. Positive news likely leads to lower oil prices and lower rates. Delays and back-and-forth rhetoric are likely to lead to an uptick in oil prices…and rates.
The overall market theme we have been tracking recently continues – progress towards a US/Iran peace deal and/or lower oil prices will likely lead to lower rates and more stable markets. Conversely, if we see indications that the peace deal will not happen, is significantly delayed or worse, hostilities resume, we are likely to get higher oil prices and higher rates. From my perspective, the only way we will see materially lower rates is a peaceful resolution to the US-Iran conflict. Traders will continue to anxiously monitor war developments as news and developments unfold.
If this latest “peace plan” optimism is once again quashed (and that it how it is looking right now), I would not be surprised at all to see rates resume their march higher – we are seeing that on a small scale so far this morning. I believe the market wants to see lower rates – an end to the conflict is the answer. That said, and make no mistake, should the conflict in the Middle East linger indefinitely, the fear of higher inflation will augment further, and we may only just be seeing the beginning of a bond market fearful of higher inflation.
“Key News” the market is tracking includes:
Geopolitical developments continue to weigh on markets.The US/Iran “war” continues to dominate market sentiment this week.
Kevin Warsh has been confirmed as the new FOMC Chairman. He will oversee his first meeting as Chair beginning June 16. From the market’s perspective, there are still many questions surrounding both Mr. Warsh’s monetary policy views and his plans for the central bank, and what is next for Mr. Powell.
Market participants continue to track developments in the US equities markets. There is still a sharp focus on the performance of the growing AI sector. Overall market sentiment, and perhaps even economic performance, could be impacted by “tech” earnings for the foreseeable future.
SCOTUS is currently ruling on the legality of the President firing of the Fed’s Lisa Cook. There are some reports stating that SCOTUS is nearing a final decision on that case, which could have far reaching implications for the US Central Bank.
SOFR Swap Rate Summary: The 1Y SOFR swap rate is trading up ~3-4 bps this morning. 2Y and 3Y SOFR swap rates are currently trading up ~5-7 bps. 5Y and 10Y SOFR swap rates are trading up ~5-7 bps on the day. The very back-end of the swap curve is currently trading up ~4-6 bps from yesterday’s closing levels.
Swap rates across the curve have now reached new “war-highs”. Swap rates are also sitting at 12-month highs. I expect swap rates to remain biased higher until a peace plan is announced, but we could see rates bounce around depending on the news and rumors of the day.
Key SOFR Swap Rate Movements Since The US-Iran War Began:
• The 2-year SOFR swap rate closed at 3.21% on Friday 2/27 – it is currently trading at ~3.954% (+74.4 bps).
• The 5-year SOFR swap rate closed at 3.22% on Friday 2/27 – it is currently trading at ~4.025% (+80.5 bps).
• The 10-year SOFR swap rate closed at 3.52% on Friday 2/27 – it is currently trading at ~4.222% (+70.2 bps).
Please note: Market levels can change rapidly – rate cap premiums are subject to a dynamic market that can change frequently.
CHART 1: US RATES SNAPSHOT: 9:15 AM Eastern
Chart 1 Key:
Far Left Columns:US Treasury Yields & Change on Day (bps)
Center Columns:SOFR OIS Swap Spreads (bps) & Change on Day (bps)
Far Right Columns:SOFR OIS Swap Rates & Change on Day (bps)
UST YIELDS | SWAP SPREADS | SOFR SWAP RATES
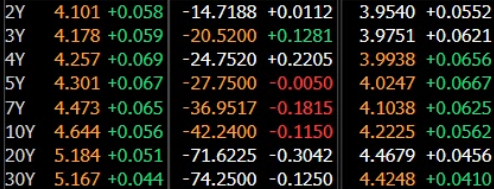
Source: Bloomberg, LLP | 9:15 AM NY Rates Snapshot
Please contact us if you would like to discuss an upcoming rate cap or rate cap extension, explore ways to reduce or eliminate escrow deposits for replacement caps or learn more about interest rate Caps, Floors, Swaps or Swaptions. RCA can also assist you with the voluntary early termination of your cap or swap.
HedgeWithAnEdge-TheRCAEdge!
Disclaimer: The information provided in this communication is intended for discussion purposes only. Nothing presented in this communication should be taken as a recommendation or forecast. All market data shown is indicative only and subject to change depending on current market conditions. The information in this publication is confidential and is intended for the recipient only.