

Rate Markets Update · Wednesday, July 22, 2026
Rates Tick Higher as Traders Monitor Developments in the Middle East and Prepare for the Release of Key Tech Earnings Reports
Flash Update: US RATE MARKETS – WEDNESDAY JULY 22, 2026
UST yields and SOFR swap rates are drifting a touch higher this morning as traders anxiously monitor developments in the Middle East
Thus far, light summer trading and extraordinarily patient traders are preventing whipsaw rate movements
Surging hostilities between the US and Iran are once again spooking global markets and edging oil prices higher
The US/Iran conflict remains the primary driver for the rate markets; The price of crude oil is trading near ~$95 a barrel this morning
Traders will continue to pay close attention to developments in the tech-sector; There is growing fear that the equity markets are due for a correction
Market participants await important tech-sector earnings reports due today - Tesla Inc. and Alphabet Inc. report today
Investors will be paying particular attention to Alphabet earnings – they will be looking for evidence that Alphabet’s AI investments are generating returns
Next up for key data: June PCE prints on Thursday, 7/30 at 8:30 AM
The Fed’s external communications blackout continues; Fed officials will be in the “quiet period” until 7/30
The next FOMC rate decision is due on Wednesday, July 29th at 2:00 PM
Short-term SOFR swap rates are trading up ~1-2 bps this morning, depending on tenor
Medium-term SOFR swap rates are up ~1-2 bps currently, depending on tenor
Long-end SOFR swap rates are trading up ~1-2 bps this morning, depending on tenor
Good morning – US Treasury yields and SOFR swap rates are ticking a touch higher this morning as traders continue to monitor a variety of potential market catalysts. Mounting uncertainty surrounding the conflict in the Middle East, anxiety about high tech-sector equity valuations, jitters surrounding the potential for a deluge of new tariffs and the upcoming Fed rate decision are all weighing on markets. Currently, the situation in the Middle East remains the market’s primary focus.
Overnight, the US widened the scope of its airstrikes on Iran and the Iranian government fired on US bases in Kuwait, Bahrain and Jordan. There are no negotiations between the US and Iran currently scheduled, dimming the prospect for peace in the near term. Overall, the situation in the Middle East seems to be deterorating, not improving. Escalating Gulf hostilities have also pushed oil prices higher this week – Brent crude oil topped $85 a barrel earlier this morning. It does not appear that a quick resolution to the conflict is on the horizon, which will likely keep the rate bias firmly entrenched to the upside for now.
Fed officials remain within the pre-meeting “quiet period” until July 30. We don’t really see any key data released ahead of the Fed rate decision on the 29th. The lack of Fed speakers and key economic data ahead of next week’s Fed meeting makes it likely the market’s focus will remain on developments in the US-Iran war.
Market Avoids Whipsaw Moves, but Rates are Quietly Creeping Back Toward the YTD Highs Reached on July 14th
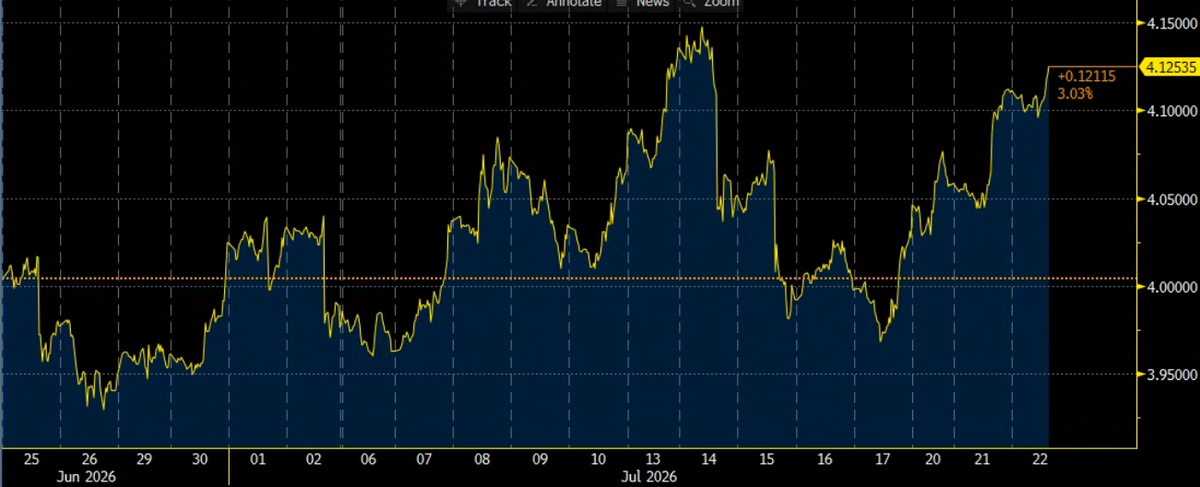
Source: Bloomberg, LLP | 2-Year OIS Annual SOFR Swap Rate Movement – Prior 30 Days
“Key News” the market is tracking includes:
Geopolitical developments continue to weigh on markets.Developments in the US/Iran “war” will continue to dominate market sentiment.
Market participants continue to track developments in the US equities markets. There is still a sharp focus on the performance of the growing AI sector. Overall market sentiment, and perhaps even economic performance, could be impacted by “tech” earnings for the foreseeable future.
Tariffs are once again in focus, as President Trump implements a new round of tariffs and threatens more are coming. This is the last thing global markets need right now – they are already grappling with massive inflation uncertainty due to the conflict in the Gulf. This is a developing story, so the market impact is undetermined currently.
The possibility exists we may be facing another government shutdown soon. Lawmakers have reached a temporary compromise to avert a shutdown for now, but the threat of another government shutdown looms.
SOFR Swap Rate Summary: The 1Y SOFR swap rate is trading up ~1-2 bps this morning. 2Y and 3Y SOFR swap rates are currently trading up ~1-2 bps. 5Y and 10Y SOFR swap rates are trading up ~1-2 bps this morning. The very back-end of the swap curve is currently up ~1-2 bps from yesterday’s closing levels.
Please note: Market levels can change rapidly – rate cap premiums are subject to a dynamic market that can change frequently.
CHART 1:US RATES SNAPSHOT: 9:00 AM Eastern
Chart 1 Key:
Far Left Columns:US Treasury Yields & Change on Day (bps)
Center Columns:SOFR OIS Swap Spreads (bps) & Change on Day (bps)
Far Right Columns:SOFR OIS Swap Rates & Change on Day (bps)
UST YIELDS | SWAP SPREADS | SOFR SWAP RATES
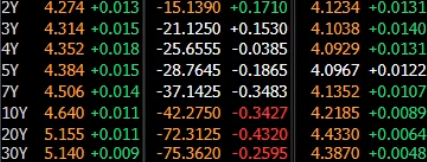
Source: Bloomberg, LLP | 9:00 AM NY Rates Snapshot
CHART 2, 2A, 2B & 2C: SOFR SWAP RATES TICK HIGHER ON MIDDLE EAST JITTERS; BRENT CRUDE OIL TRADING NEAR $95 A BARREL
SOFR swap rates are drifting a touch higher this morning, as jittery traders anxiously monitor a host of market forces at work. Massive uncertainty surrounding the conflict in the Middle East, the sustainability and veracity of tech sector equity valuations and the path forward for the FOMC are making it extremely challenging to chart the path forward for interest rates currently.
I expect volatility to remain subdued – we are in the middle of summer trading and more importantly, traders have grown increasingly adept at ignoring the rhetoric and noise and focusing on the hard facts…or lack thereof! That “patience” is preventing more extreme, whipsaw reactions to announcements and rumors. Rate volatility catalysts on the horizon include: A decisive end to the conflict; A tech-led equity market correction; A major increase in US-Iran hostilities beyond what we have seen to date; A Fed rate hike next week.
I also expect rates, overall, to remain biased higher. FOMC Chair Warsh has talked a “big game” recently – he made it clear inflation will not be tolerated – that is likely to keep upward pressure on the Fed-sensitive short-end of the curve, particularly as we approach next week’s Fed rate decision.
Odds for a 25 bp Fed rate hike at the July meeting have increased since hostilities between the US and Iran escalated – they are now sitting at ~28.6%. That figure was at ~10.2% just last week! Odds for a rate hike in September have been bumped back up to ~70%. One thing is certain: Expectations for the Fed and for the path forward for interest rates are changing and evolving almost every day.
US-IRAN WAR IMPACT: Key SOFR Swap Rate Movements Since The US-Iran War Began:
The 2-year SOFR swap rate closed at 3.21% on Friday 2/27 – it is currently trading at ~4.123%(+91.3 bps).
The 5-year SOFR swap rate closed at 3.22% on Friday 2/27 – it is currently trading at ~4.097%(+87.7 bps).
The 10-year SOFR swap rate closed at 3.52% on Friday 2/27 – it is currently trading at ~4.218%(+69.8 bps).
CHART 2:Short-End SOFR Swap Rates – Year-To-Date 2026
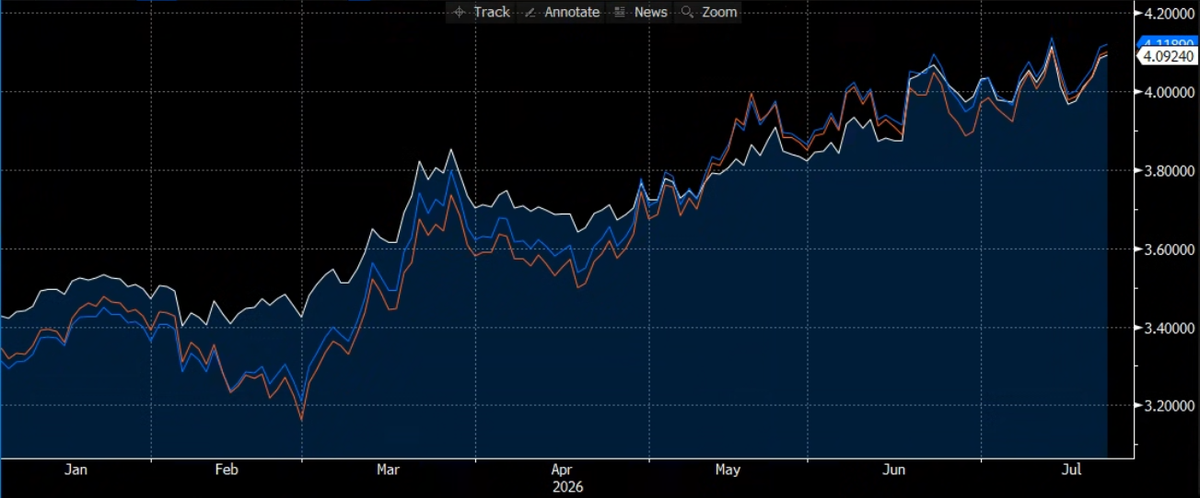
Source: Bloomberg, LLP | 1Y (white), 2Y (blue) & 3Y (orange) SOFR SWAP RATES; YTD 2026
CHART 2A:Long-End SOFR Swap Rates – Year-To-Date 2026
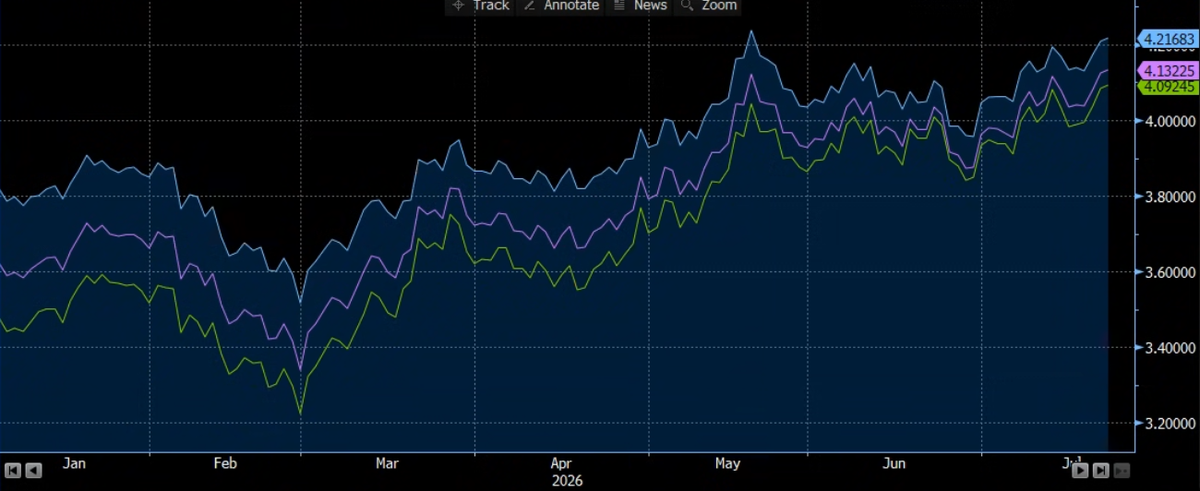
Source: Bloomberg, LLP | 5Y (green), 7Y (purple) & 10Y (light blue) SOFR SWAP RATES; YTD 2026
CHART 2B:US Treasuries: Yield Overview – Year-To-Date 2026
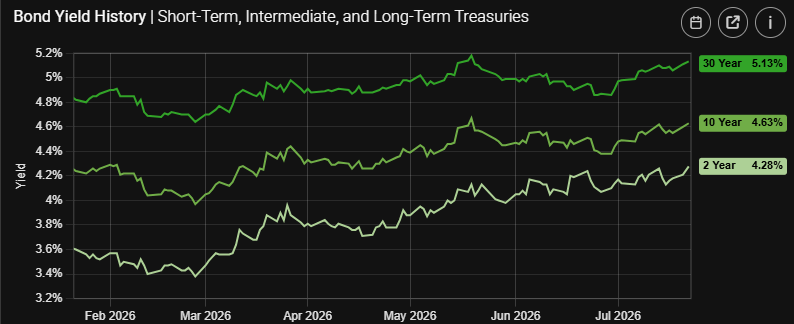
Source: StreetStats | US Treasury Yields; YTD 2026 (30Y UST yield – top line; 10Y UST yield – middle line; 2Y UST yield – bottom line)
CHART 2C: Price of Brent Crude Oil Approaches $95 a Barrel as Middle East Hostilities Escalate
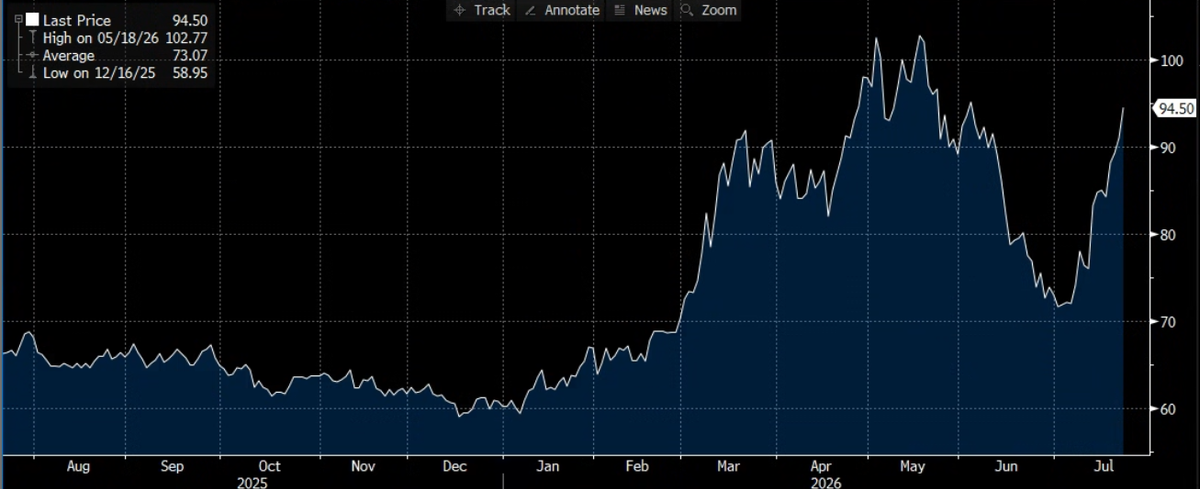
Source: Bloomberg, LLP | HISTORICAL PRICE PER BARREL BRENT CRUDE OIL – PRIOR 12 MONTHS
RCA Product & Pricing Update:
Product Spotlight: What We Are Seeing In The Rates & Derivatives Markets
The market is once again facing tremendous uncertainty surrounding the path forward for interest rates. Borrowers should be as nimble as possible in this market environment. Cap purchasers should onboard as quickly as possible – there is no cost to onboard. It is important to be in a position to take advantage of market opportunities quickly and efficiently.
Given the high-level of uncertainty surrounding forward rates, many clients are grappling with when or if to extend. This is a difficult question – our advice has been to monitor the market closely and be on-boarded and ready to trade, should the market move in your favor. We also advise borrowers to check the market pricing for extensions, similar to how you purchased the original cap. Market pricing discovery is a key component to any cap transaction – new caps, extensions or terminations.
There is an increasing interest in exploring interest rate swaps as a possible hedge alternative. IR Swaps lock in a synthetic fixed rate and do not require an upfront premium. Unlike an interest rate cap, swaps are secured derivatives, so the counterparty selection process is more challenging with a swap. There are also additional variables that factor into the decision to pursue an interest rate swap, or to unwind an existing swap. We are also seeing a dramatic increase in swap termination advisory requests recently, as clients contemplate refinancings. Lower rates have sparked refinancing activity, which in some cases necessitates unwinding an existing swap. Please let us know if you would like to learn more about interest rate swaps, or swap terminations.
We are still seeing some residual demand for interest rate floor indications – to offset high loan floors or simply to benefit from declining variable rates. Borrowers who have “floors” embedded in their loans have been considering purchasing a separate, stand-alone interest rate floor to offset the loan floor.
Interest Rate Cap Hub: Pricing & Volatility Update for 7/22/2026
Current 1-Month SOFR = 3.67591%(Prior Day’s Reset: 3.66738%)
Escalatinghostilities between the US and Iran are increasing market uncertainty regarding the path forward for interest rates
Rate volatility remains relatively subdued given the myriad market forces at work
The swap curve remains flat – the 2’s/10’s swap spread is currently ~10.5 bps
Cap Pricing Matrix:1-Month Term SOFR Cap Premiums: Week-On-Week
Notional Amount | Tenor | Strike Rate | ~Premium 7/15/26 | ~Premium 7/22/26*^ |
$25,000,000 | 1-Year | 3.50% | ~$147k | ~$151k |
$25,000,000 | 1-Year | 4.50% | ~$38k | ~$42k |
$25,000,000 | 2-Year | 3.50% | ~$345k | ~$320k |
$25,000,000 | 2-year | 4.50% | ~$118k | ~$121k |
$25,000,000 | 3-Year | 3.50% | ~$548k | ~$552k |
$25,000,000 | 3-Year | 4.50% | ~$210k | ~$216k |
*Indications as of market open. Premium levels provided are indications only and subject to frequent change.
CHART 3:Historical Volatility: MOVE (Rate Vol.- RED) and VIX (Equity Vol.- BLUE) – Year-To-Date 2026
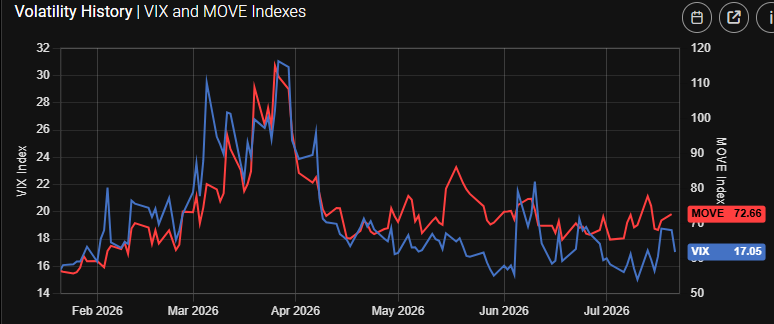
Source: StreetStats | HISTORICAL RATE (MOVE) AND EQUITY (VIX) VOLATILITY – YTD 2026
^NOTE:RATE MARKETS CAN BE VOLATILE - MARKET DYNAMICS AND PRICING CAN CHANGE VERY QUICKLY IN THIS MARKET ENVIRONMENT.
**WE RECOMMEND YOU CALL US FOR ACCURATE, UP-TO-THE-MINUTE CAP INDICATIONS.**
Please contact us if you would like to discuss an upcoming rate cap or rate cap extension, explore ways to reduce or eliminate escrow deposits for replacement caps or learn more about interest rate Caps, Floors, Swaps or Swaptions. RCA can also assist you with the voluntary early termination of your cap or swap.
HedgeWithAnEdge-TheRCAEdge!
Disclaimer: The information provided in this communication is intended for discussion purposes only. Nothing presented in this communication should be taken as a recommendation or forecast. All market data shown is indicative only and subject to change depending on current market conditions. The information in this publication is confidential and is intended for the recipient only.