

Rate Markets Update · Tuesday, September 22, 2026
Rates Edge Lower as Oil Prices Dip
- President Trump to Address United Nations Later Today
Flash Update: US RATE MARKETS – TUESDAY SEPTEMBER 22, 2026
US Treasury yields and SOFR swap rates are edging lower this morning on the back of lower oil prices
Sentiment has improved in the Middle East, leading to renewed optimism that the US and Iran are gearing up for another round of negotiations
News this morning that Saudi Arabia is close to reopening its East-West pipeline also helped push oil prices lower
The US-Iran conflict, and the price of crude oil, continue to be the primary focus for the rate markets; Rates are likely to continue to track the direction of oil prices for the near term
Traders are still wary that the US-Iran conflict will persist indefinitely, leading to sustained higher inflation and reduced economic growth
The next FOMC rate decision is due Wednesday, October 28th at 2:00 PM
Odds for a 25 bp October Fed rate hike have drifted a touch lower this week and are currently sitting at ~53.1% this morning
Next up for “key” economic data: GDP, PCE, Personal Income and Personal Spending data print on 9/30 at 8:30 AM
Note: Given the tight-lipped, “no forward guidance” Fed approach, ALL economic data is likely to be more thoroughly scrutinized by market participants going forward
Short-term SOFR swap rates are trading down ~1-2 bps this morning, depending on tenor
Medium-term SOFR swap rates are down ~1-2 bps currently, depending on tenor
Long-end SOFR swap rates are trading down ~1-2 bps bp this morning, depending on tenor
Good morning – US Treasuryyields and SOFR swap rates are edging lower this morning on the back of a dip in crude oil prices. Oil turned lower as Saudi Arabia announced they are seeking to resume flows on the vital East-West pipeline and there were growing signs of renewed diplomatic efforts to reopen the Strait of Hormuz. As such, Brent crude oil dipped below $98 a barrel this morning. The drop in oil prices was further supported after Japan’s Kyodo News Agency cited an unnamed senior Iranian official as saying Iran proposed reopening the Strait of Hormuz in seven days if a US blockade is lifted. It was also reported this morning that Iran’s Revolutionary Guard said it must negotiate if it is in the “national interest to do so”. Perhaps US economic and military pressure is forcing Iran back to the negotiating table!
However, the likelihood the US and Iran may eventually reach a deal is still far from certain, which could keep the threat of higher rates across the curve alive for the foreseeable future. Note: President Trump is set to address the UN General Assembly in New York later today, and there are rumors swirling that he may seek to meet with his Iranian counterpart on the side. I expect we may see some news headlines generated from the UN gathering today.
Despite some “positive trends” developing in the Middle East, traders remain cautious, given the numerous “head fakes” they have experienced over the past few months – rates are lower this morning, but not materially. I still expect that rates will track the direction of oil prices for the near term. Make no mistake, should diplomatic efforts collapse or oil prices begin to rise, rates are likely to resume marching higher. I do not believe the ever-present fear of higher sustained inflation will diminish until oil prices move significantly lower. The best chance of that occurring is an end to hostilities in the Middle East and a return to “normal” energy markets.
CHART OF THE DAY:
A: Rates Edge Lower As Oil Prices Dip
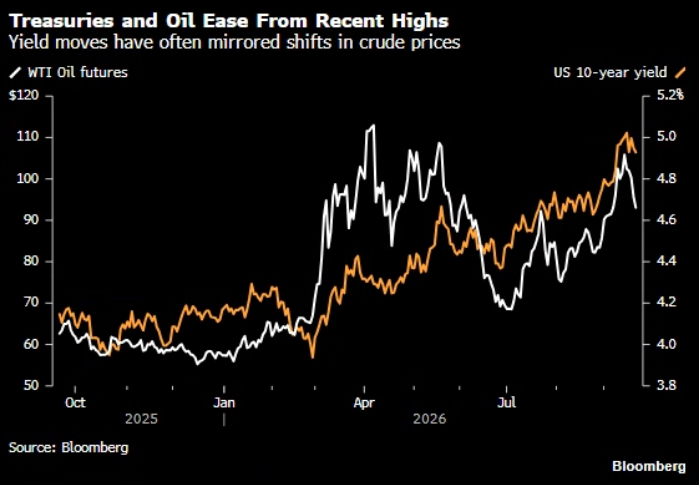
Source: Bloomberg, LLP | WTI OIL FUTURES AND US 10-YEAR TREASURY YIELDS – PRIOR 12-MONTHS
“Key News” the market is tracking includes:
Geopolitical developments continue to weigh on markets.Developments in the US/Iran “war” will continue to captivate the market’s attention. l
Lack of forward guidance from the Fed is forcing traders to pay more attention to economic data – this may fundamentally change the way markets position for and react to Fed rate decisions going forward.
Market participants continue to track developments in the US equities markets. There is still a sharp focus on the performance of the growing AI sector. Overall market sentiment, and perhaps even economic performance, may be impacted by tech-sector results for the foreseeable future.
Tariffs remain in focus, particularly the developing situation between the US and Canada. US/China relations are always in focus. On many levels, more tariffs are last thing global markets need right now – they are already grappling with massive inflation uncertainty due to the conflict in the Gulf.
The US Treasury Department’s recent bond market interventions set the stage for more to come. So far, the market is shrugging off the interventions and bond yields continue to tick higher.
FOMC Update:
Market implied odds for a 25 bp October Fed rate hike have drifted a touch lower this week and are currently at ~53.1%.
Warsh and the FOMC helped rebuild their “market” credibility last week by backing up hawkish talk with a 25 bp rate hike.
SOFR Swap Market - Quick Summary:
The 1Y SOFR swap rate is trading down ~1-2 bps this morning. 2Y and 3Y SOFR swap rates are currently trading down ~1-2 bps. 5Y and 10Y SOFR swap rates are trading down ~1-2 bps this morning. The very back-end of the swap curve (20Y and 30Y) is currently trading down ~1-2 bps from yesterday’s closing levels.
CHART 1:US RATES SNAPSHOT: 8:45 AM Eastern
Chart 1 Key:
Far Left Columns:US Treasury Yields & Change on Day (bps)
Center Columns:SOFR OIS Swap Spreads (bps) & Change on Day (bps)
Far Right Columns:SOFR OIS Swap Rates & Change on Day (bps)
Please note: Market levels can change rapidly – rate cap premiums are subject to a dynamic market that can change frequently.
UST YIELDS | SWAP SPREADS | SOFR SWAP RATES
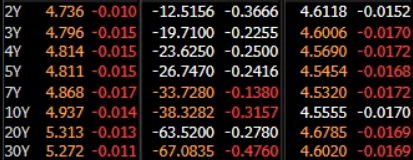
Source: Bloomberg, LLP | 8:45 AM NY Rates Snapshot
CHART 2, 2A & 2B: SOFR SWAP RATES TICK LOWER AS CRUDE OIL PRICES DIP
SOFR swap rates are ticking lower this morning on the back of a dip in oil prices overnight. I still feel strongly that swap rates are likely to continue to drift lower if the reduction in oil prices is sustained. However, make no mistake – sentiment is likely to shift quickly if oil prices move higher, or if progress towards peace remains elusive. I am certainly not ready to call for sustained lower rates; there is still too much uncertainty. As long as “the crisis” and high oil prices continue, the risk of higher rates and another Fed rate hike remain front and center for the market.
I would also say that the FOMC definitely grabbed some of the market spotlight last week, as an active Fed is now firmly back in play, creating further uncertainty about what’s next for rates. Based on what I heard from the Fed last week, the FOMC has a tightening bias – how long that lasts is the big question.
Today’s “positive” Middle East news may signal the beginning of a renewed diplomatic effort to end the war, or it may just be another temporary pause leading nowhere. Stay tuned! We could see some rate action today depending on what transpires at the UN summit. All ears will be on President Trump later today for clues to the “go forward” US approach to the conflict in the Middle East.
US-IRAN WAR IMPACT: Key SOFR Swap Rate Movements Since The US-Iran War Began
The 2-year SOFR swap rate closed at 3.21% on Friday 2/27/2026 – it is currently trading at ~4.612%(+140.2 bps)
The 3-year SOFR swap rate closed at 3.22% on Friday 2/27/2026 – it is currently trading at ~4.601%(+138.1 bps)
The 5-year SOFR swap rate closed at 3.22% on Friday 2/27/2026 – it is currently trading at ~4.545%(+132.5 bps)
The 10-year SOFR swap rate closed at 3.52% on Friday 2/27/2026 – it is currently trading at ~4.556%(+103.6 bps)
CHART 2:Short-End SOFR Swap Rates – Year-To-Date 2026
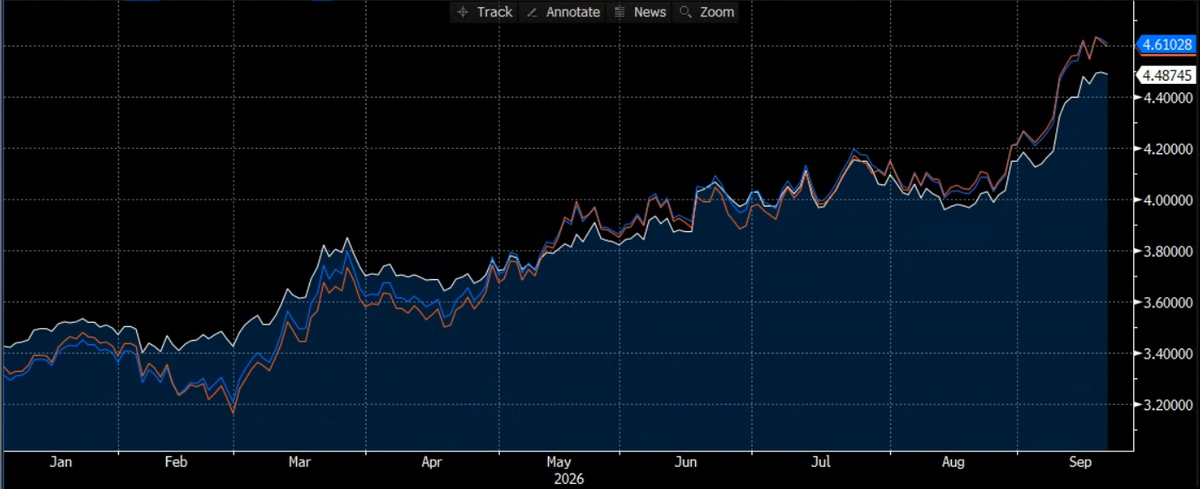
Source: Bloomberg, LLP | 1Y (white), 2Y (blue) & 3Y (orange) SOFR SWAP RATES; YTD
CHART 2A:Long-End SOFR Swap Rates – Year-To-Date 2026
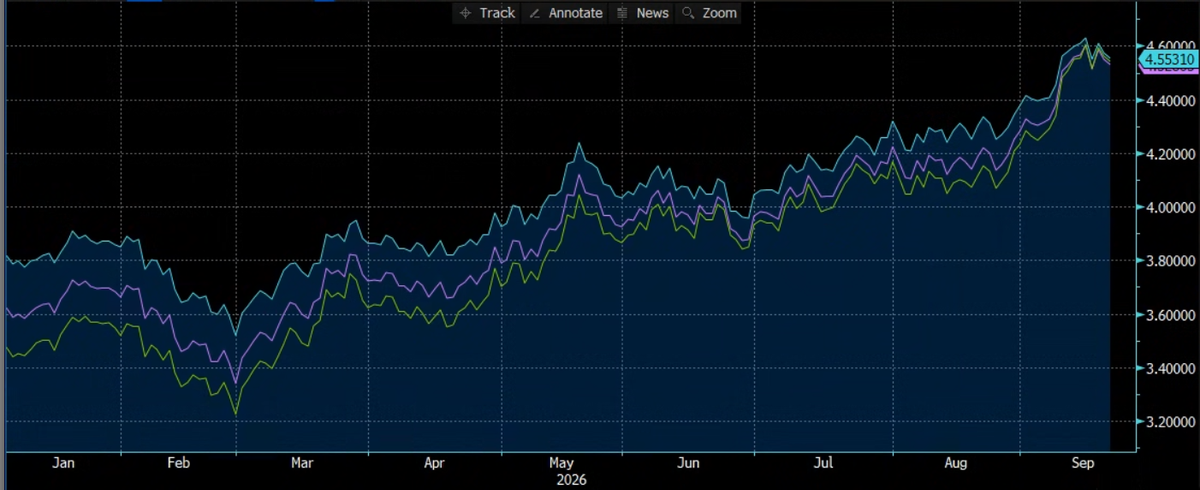
Source: Bloomberg, LLP | 5Y (green), 7Y (purple) & 10Y (light blue) SOFR SWAP RATES; YTD
CHART 2B: US Treasuries: Yield Overview – Prior Six Months
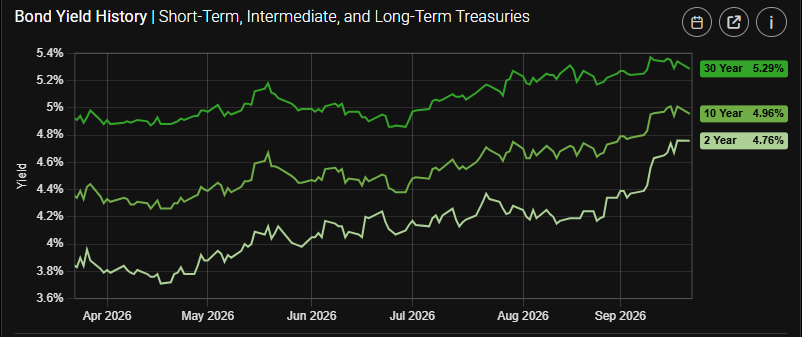
Source: StreetStats | US Treasury Yields – Prior Six Months
RCA Product & Pricing Update:
Product Spotlight: What We Are Seeing in the Rates & Derivatives Markets
The market is once again facing tremendous uncertainty surrounding the path forward for interest rates. Borrowers should be as nimble as possible in this market environment. Cap purchasers should onboard as quickly as possible – there is no cost to onboard. It is important to be in a position to take advantage of market opportunities quickly and efficiently.
There is an increasing interest in exploring interest rate swaps as a possible hedge alternative. IR Swaps lock in a synthetic fixed rate and do not require an upfront premium. Unlike an interest rate cap, however, swaps are secured derivatives, so the counterparty selection process is more challenging with a swap. It is often challenging to place a swap away from the lender or incumbent relationship bank. There are also additional variables that factor into the decision to pursue an interest rate swap, or to unwind an existing swap. With the uptick in swap rates recently, we are also seeing an increase in swap termination requests. Please let us know if you would like to learn more about interest rate swaps, or swap terminations. RCA offers a full range of Derivative Advisory services.
Given the high-level of uncertainty surrounding forward rates, many clients are grappling with when or if to extend. This is a difficult question – our advice has been to monitor the market closely and be on-boarded and ready to trade, should the market move in your favor. We also advise borrowers to check the market pricing for extensions. Market price discovery is a key component to any cap transaction – new caps, extensions, or terminations.
We are still seeing some residual demand for interest rate floor indications – to offset high loan floors or simply to benefit from declining variable rates. Borrowers who have “floors” embedded in their loans have been considering purchasing a separate, stand-alone interest rate floor to offset the loan floor.
Interest Rate Cap Hub: Pricing & Volatility Update for 9/22/2026
Current 1-Month SOFR = 3.89702%(Prior Day’s Reset: 3.89869%)
Rate volatility has ticked a touch higher since the FOMC rate decision and Chairman Warsh’s press conference last week
Market uncertainty surrounding the path forward for interest rates remains elevated
Cap Pricing Matrix:1-Month Term SOFR Cap Premiums: Week-On-Week
Notional Amount | Tenor | Strike Rate | ~Premium 9/15/26 | ~Premium 9/22/26 Open* |
$25,000,000 | 1-Year | 3.50% | ~$226k | ~$246k |
$25,000,000 | 1-Year | 4.50% | ~$63k | ~$70k |
$25,000,000 | 2-Year | 3.50% | ~$533k | ~$566k |
$25,000,000 | 2-year | 4.50% | ~$198k | ~$209k |
$25,000,000 | 3-Year | 3.50% | ~$834k | ~$867k |
$25,000,000 | 3-Year | 4.50% | ~$359k | ~$370k |
*Indications as of Market Open. Premium levels provided are indications only and subject to frequent change.
CHART 3:Historical Volatility: MOVE Composite US Treasury Yield Volatility Index - Year-To-Date 2026
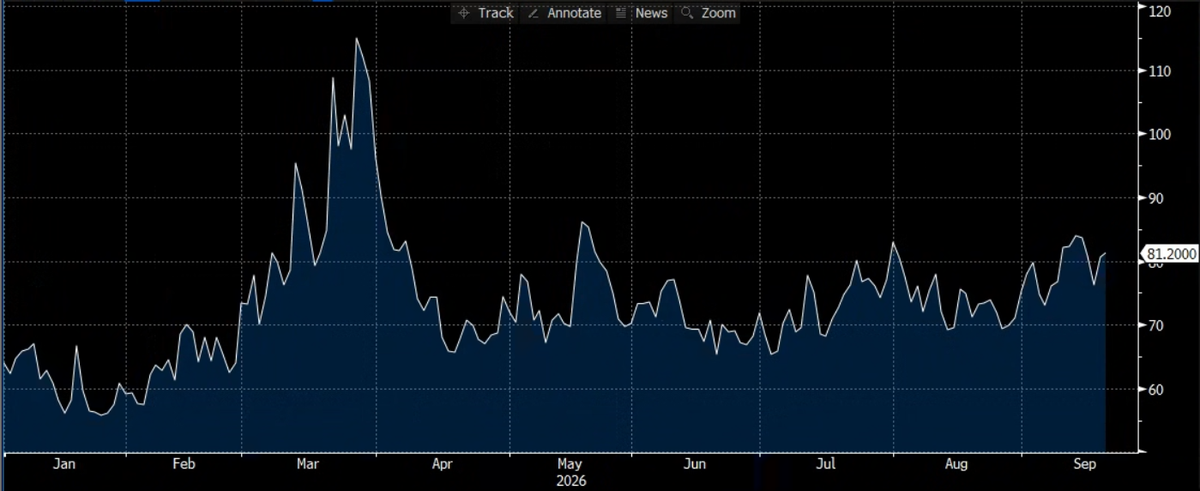
Source: Bloomberg, LLP | HISTORICAL US TREASURY YIELD VOLATILITY, “MOVE” INDEX – YTD 2026
^NOTE:RATE MARKETS CAN BE VOLATILE - MARKET DYNAMICS AND PRICING CAN CHANGE VERY QUICKLY IN THIS MARKET ENVIRONMENT.
**WE RECOMMEND YOU CALL US FOR ACCURATE, UP-TO-THE-MINUTE CAP INDICATIONS.**
Please contact us if you would like to discuss an upcoming rate cap or rate cap extension, explore ways to reduce or eliminate escrow deposits for replacement caps or learn more about interest rate Caps, Floors, Swaps or Swaptions. RCA can also assist you with the voluntary early termination of your cap or swap.
HedgeWithAnEdge-TheRCAEdge!
Disclaimer: The information provided in this communication is intended for discussion purposes only. Nothing presented in this communication should be taken as a recommendation or forecast. All market data shown is indicative only and subject to change depending on current market conditions. The information in this publication is confidential and is intended for the recipient only.