

Ast/rca Rates Market Flash Report · Friday, October 2, 2026
Rates Lower - Employment Report Misses Expectations
Good morning –
The September Employment Report was much weaker-than-expected, sending rates lower and reducing the odds for an October rate hike – odds are now sitting at 13.8%! Average hourly earnings also missed expectations to the downside. This may start to rebalance fear of higher inflation and fear of weaker economic growth. I do not think this will lead to a sustained dip in rates. Today’s move has more to do with shifting FOMC expectations. If anything, this complicates the Fed’s job – as we know, weak growth and high inflation are difficult for the Fed to manage via monetary policy adjustments. The conflict in the Middle East and high oil prices will remain the key market focus. It now appears that war-induced high rates are slowing down the jobs market and creating inflation angst. Prepare for increased rate volatility in the near term.
SOFR swap rates are currently down ~6-9 bps across the curve (See below), depending on tenor. Note: swap rates were down ~10-12 bps right after the number printed – markets have already retraced a touch. As I mentioned, I don’t think today’s jobs data green-lights lower rates – inflation is probably still the bigger market worry for now. It could, however, keep the Fed on hold in October. For the week, SOFR swap rates across the curve are currently down ~20-25 bps (See below).
There is another batch of data due at 10:00 AM today, Factory Orders, Durable Goods Orders and Capital Goods Orders – given the market’s increased sensitivity to data recently, we may see some additional volatility after the 10:00 AM data prints, but I think the “big show” today was the jobs data.
We could also see rates dip a touch lower this afternoon if traders decide to park assets in Treasuries for the weekend.
SOFR OIS SWAP RATES: 9:00 AM
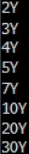
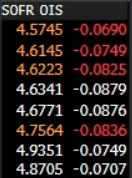
SOURCE: BLOOMBERG LLP
2-YEAR SOFR OIS SWAP RATE MOVEMENT THIS WEEK – Swap Rates Materially Lower Week-On-Week
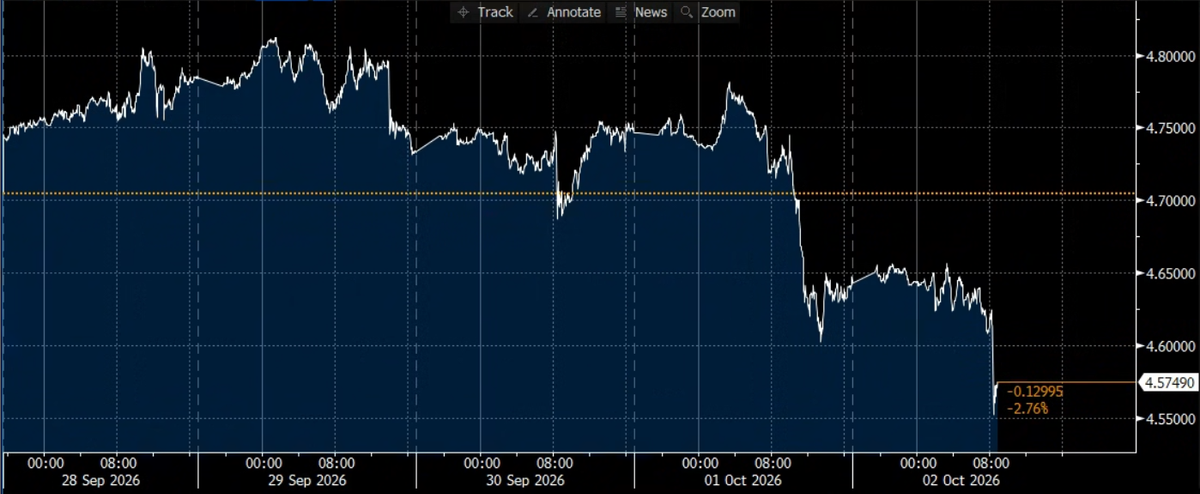
SOURCE: BLOOMBERG LLP
SEPTEMBER EMPLOYMENT REPORT RECAP:
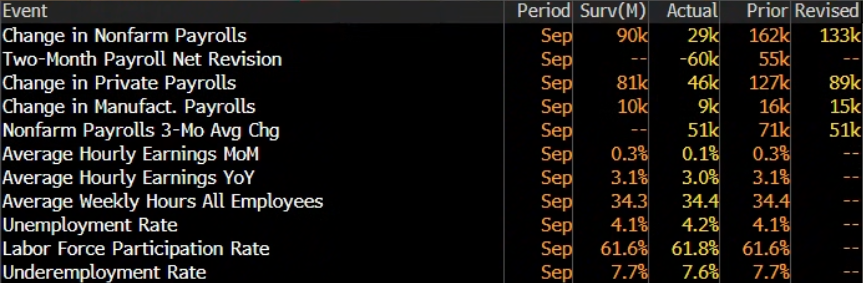
SOURCE: BLOOMBERG LLP
Disclaimer: The information provided in this communication is intended for discussion purposes only. Nothing presented in this communication should be taken as a recommendation or forecast. All market data shown is indicative only and subject to change depending on current market conditions. The information in this publication is confidential and is intended for the recipient only.